ISSUE 185, October 30, 2026 | | | |
|
DURUM
Ryan Statz, Merchant
| | |
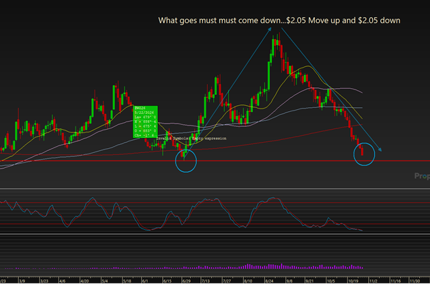
- Durum markets have softened some over the past few weeks, driven by a few things:
- Canadian production estimates have been revised higher due to impressive late-season yield upticks.
- Quality unknowns are becoming more transparent. In September, many participants knew issues would persist. No one knew how bad things would be, and thus, additional risk premiums were taken. Now that the crop has come off, there is more transparency on what and where things are. Thus, more are comfortable in offering and selling, and the large risk premiums that were present have waned.
-
Weaknesses in the overall commodity sector. Wheat, corn, and soybeans have all come off highs that were present in September.
- The sorting and segregation of quality remains focus number one. Deciphering Canadian grade distribution within and where it exists. We know abundant harvest rainfall rocked quality in pockets; the degree to which and its locations are the key pieces.
- CWAD #1, 2, and 3s will find their way to export outlets. The #4/5s likely will not, and that is what the market will hone in on. How much of the Canadian crop is not milling quality?
-
It will be the market’s job to find and manage this quality. Values will ultimately be determined by the market’s ability to resolve this situation.
-
Canadian durum exports are running more than 70% ahead of last year at this time.
-
If additional downgrading in quality is confirmed, stronger premiums could develop for higher-quality durum even if the total US/Canadian production remains adequate upfront. The lingering high-quality ‘tightness’ will play in the back of the participants’ minds for the back end of the year, and that will likely keep a premium on said quality throughout.
- As said in previous reports, there are a lot of factors pushing/pulling other commodities, which is playing into durum strength and/or weakness. These remain:
- Middle East turmoil, China trade ideas and agreements, higher fuel/freight costings, row crop harvest, US HRW plantings, etc.
| |
BARLEY
Matthew Schorn, Senior Merchant
| | | |
Malt Demand and Price Trends
-
Malt barley markets remain relatively steady, with sluggish demand and little urgency from buyers to secure additional coverage.
-
Quality remains variable following a wet harvest, with test weight, plumpness, protein, and sprout damage continuing to influence malt acceptance and premiums.
-
Weakness across the grain complex is limiting upside potential, with malt premiums dependent on quality and individual maltster demand.
-
Producers should have representative samples tested and confirm potential malt premiums before deciding whether to market barley as malt or feed.
Canadian Domestic Feed Market
-
Domestic feed barley values remain largely unchanged, with sluggish demand and limited buyer interest in extending coverage.
-
Weakness in corn and wheat futures is weighing on feed-grain markets and limiting upside potential for barley.
-
Producer selling remains relatively limited, but without stronger demand, the market is likely to remain sideways with a softer bias.
- Higher freight costs and limited carrier availability continue to influence delivered values and create regional price differences.
| | |
HARD RED WINTER / SPRING WHEAT
Ryan Statz, Merchant
| | |
- Big flat price breaks have commenced, mostly due to futures market weakness tied to a few factors:
- Middle East turmoil and its supply chain constraints have softened.
- Row crop weakness with harvest pressure.
-
Quality unknowns, particularly in the Spring Wheat sector, are becoming more transparent and known.
- In addition to futures being down, basis has softened some in HRS, mostly due to more participants having a bit more comfort in knowing what they have and having a plan in place on how to execute through it.
- HRW basis levels seem stuck, mixing a historically small crop that has the market leaning bullish with a demand problem that can’t find buyers because prices are still too high.
-
Both HRS and HRW are also, at the same time, dealing with a rail freight environment that is making for a less competitive picture.
-
As said in prior reports, domestic demand continues to showcase more HRS demand and less HRW demand due to price spreads that are incentivizing more HRS usage.
- Again, the HRW market has a demand problem and is working to find a solution. This is getting the market’s attention in the nearby, while HRS continues to be about quality and how to navigate through it.
| | |
|
Joe Foley,
Product Line Manager - Corn & Soybeans
CORN
|
| | |
Corn prices are not escaping the funds selling mentioned below in soybeans. Managed money sold a net of 81,000 contracts in the most recent reporting period, paring down their long positions to 164,000 contracts. The U.S. crop was unexpectedly raised in the October WASDE, which hastened the most recent move lower, and there has not been much bullish news to offset the larger U.S. production estimate.
Indeed, exports this crop year are lagging last year’s pace by nearly 12 MMT, as most of Asia has switched demand to Brazil and Argentina. Coupled with higher freight rates following the surge in diesel prices, cash premiums in ND are seasonally quite weak.
The much larger ND production over the last few years needs a consistent PNW outlet, without which grain gets piled up waiting for better export prospects after the first of the year. Hopefully, Korea will be back as a buyer, in addition to Japan, in January, but Brazil remains competitive so far.
Watch developments on this front as well as the next supply and demand report in November but expect lower prices in the near term.
| | |
|
Joe Foley,
Product Line Manager -
Corn & Soybeans
SOYBEANS
| | | |
Soybean prices are continuing to move lower, as managed money (funds) keeps shedding their accumulated length. The most recent CFTC Commitment of Traders report showed 28,000 contracts of selling in the period, reducing their length to a still significant 221,000 contracts. That has certainly been further trimmed back this week, as prices are down nearly 50 cents/bu since our last writing.
Harvest is wrapping up now in the U.S., especially in ND. Exports have remained a bright spot this year, with China continuing their purchases. More than 15 MMT of sales have been registered in their name this crop year vs. nothing last year. When the unknown category is added to the tally (as most will be switched to China as a destination), there will have been some 20 MMT of purchases, on the way to 25 MMT perhaps.
Interior basis levels are relatively weak, however, as the railroad-assessed fuel surcharges significantly raise the cost of shipping shuttles from ND to the PNW. Elsewhere, planting for the 2027 crop is well underway in Brazil, so there’s not much bullish input on the supply side as yet, but their weather over the next several months will need to be monitored, as is normal for this time of year.
| | |
The good news is that India has confirmed their latest tender for 60,000 MT of split tur/lentils, and as expected, the whole tender went into lentils. Unfortunately, the price Indian tender participants were able to confirm was below the current market offers from US and Canadian sellers. We were hoping to see some follow-through buying for deferred shipments such that the tender participants would have stocks for the next tender in 2027. However, given the tender price, we have not seen that come to fruition yet.
The lentil market has stabilized over the last couple of weeks. Destination buyers have realized they need to pay current values and that the market will not drop back down to harvest levels. The grower seems to be supporting current pricing levels as well.
India has released another green lentil/tur tender for 60,000 MT of split product, and we expect the tender to be satisfied with green lentils (not tur from India/Africa), which has improved buying sentiment in the India market. Buyers have enough green lentils in India to cover this tender and some of the next tender, which is good, as container transit times are now 4 months, which is very long.
Sales can be made overseas, but markets seem rangebound as buyers are taking big risks, as anything bought today won't arrive for 6-7 months.
From a local perspective, many of CGI's lentil processing facilities are now booking into the 2027 calendar year for next available shipment windows, so please make sure to talk to your grain buyers if you are looking for pricing/movement/cash flow in that window to ensure you do not miss the capacity.
| |
YELLOW PEAS:
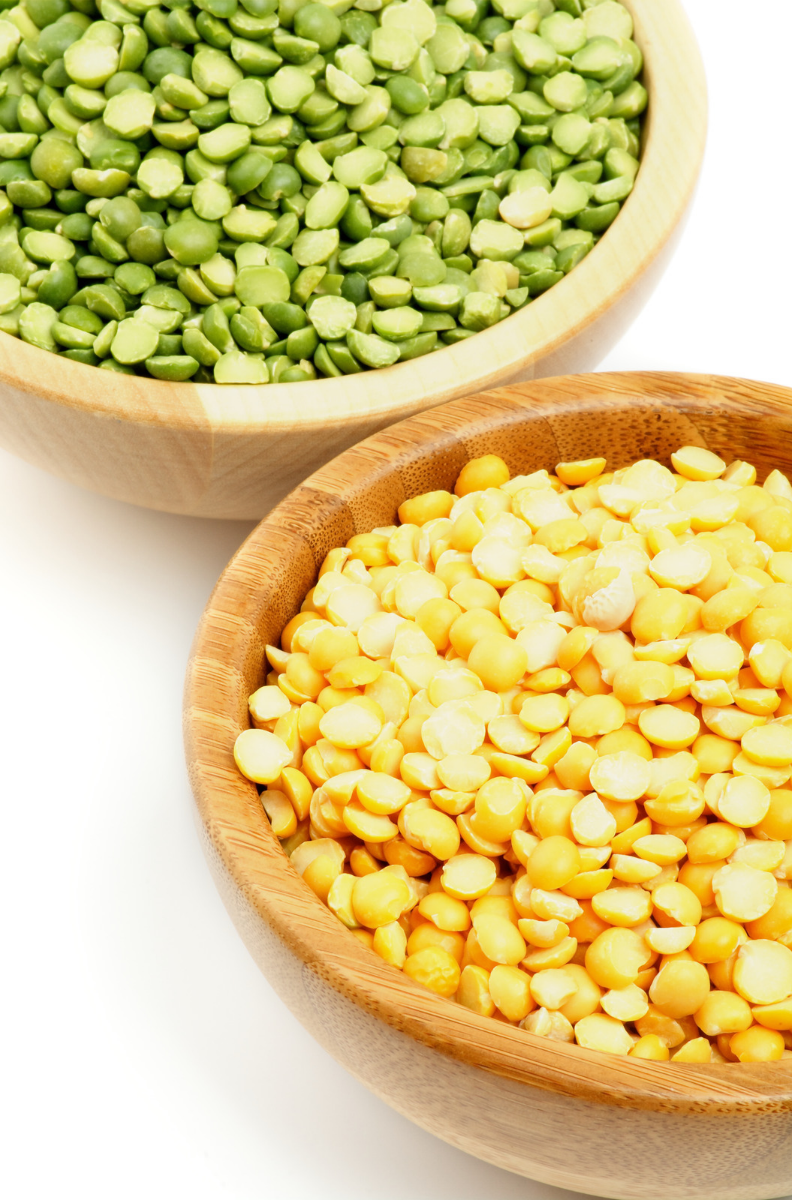
The U.S. yellow pea market continues to trend sideways. Pea protein companies continue to lead interior bids to keep operations running while the rest of the market remains stagnant. Large destination markets like India, Pakistan, and China continue to buy bulk yellow pea cargos from cheaper origins, like Canada.
Global export demand for yellow peas has remained firm since harvest. However, U.S. yellow peas are uncompetitive at the producer level for any export demand to trade in meaningful volume. The prolonged absence of USAID yellow pea food aid has left a large void for U.S. demand.
2026 U.S. field pea (both green and yellow) stocks are estimated to be the biggest total stocks in the last 5 years, potentially 200,000 MT larger than last year. If USAID food aid demand does not return this year, U.S. field peas will likely achieve the biggest carryout of field peas in the last 5 years.
GREEN PEAS:
Two weeks ago, we reported that while we expected USA tariffs on peas to China would be the same as Canadian and Argentinian competition, so far, the Chinese customers have not updated their import system.
About green peas, two weeks ago, we reported the good news that there was a high probability that additional tariffs on USA peas to China would be lifted, and tariffs would be in line with competition from other origins. To this point, unfortunately, the Chinese system has not lifted the tariffs, and so we have not seen much buying lately from our largest market.
Markets have had some firmness on the back of the green split pea tender in the USA, but this is viewed largely as a selling opportunity given volumes are still limited and carryout stocks remain burdensome.
| | |
Matt Schorn, Senior Merchant
Geopolitical and trade uncertainty continue to influence grain markets, but the dominant theme heading into late October has shifted toward harvest pressure with larger-than-expected U.S. production, and declining futures prices. Wheat, soybeans, and corn have all come under pressure as harvest progresses, yields remain strong, and ample supplies weigh on the market. Futures have retreated to multi-month lows with limited bullish news to offset seasonal selling pressure.
Corn: December corn futures fell to approximately $4.49/bushel on October 27, their lowest close since July. USDA's October outlook projected a record U.S. crop of approximately 16.0 billion bushels and ending stocks of 1.849 billion bushels. Improving harvest conditions, expectations for strong yields, and concerns about export demand are weighing on prices. With harvest still progressing and substantial supplies entering the market, rallies may face resistance unless demand strengthens or production estimates decline.
Soybeans: Soybean futures have weakened as the U.S. harvest advances and competition from South America increases. November futures traded near $12.29/bushel on October 28, down from earlier October levels. Chinese purchases have offered some support, but questions remain around sustained demand for U.S. supplies and currency-driven export competition from Brazil after the election results.
Wheat: Wheat futures have also moved lower, pressured by sluggish export demand, ample global competition, and broader weakness across the ag complex. December Chicago wheat closed near $6.10/bushel on October 27, down approximately 5% from the previous week and at its lowest level since early July.
With price levels under pressure, producers should review cash-flow needs, storage capacity, and pricing targets rather than relying solely on a market recovery. Marketing tools can help establish values, manage basis exposure, and maintain flexibility should opportunities emerge.
| | |
Columbia Producer Solutions Tools:
- Good-till-Cancelled (GTC)
- Basis Contracts
- Accumulator Contracts
- Cash +
- Average Price Contracts
- Ratchet Order
- Collar Orders
Reach out to your local buyers and managers to review these options, or others, on our Columbia Producer Solutions platform of marketing tools.
| | |
INTERNATIONAL BUSINESS
Yuya Takano and Wiley Wang
International Merchants
| | |
CORN
- Japanese buyers have covered their December and January shipments from PNW, and demand from Japan remains steady. Meanwhile, South Korea and Taiwan have purchased corn from both PNW and South America.
- Brazilian corn exports are limited by strong domestic demand for feed and ethanol. However, the smaller ocean freight difference between PNW and Brazil has helped Brazilian corn stay competitive in Asian markets.
- Asian buyers have started buying corn for January shipments. Japan is expected to continue buying from the PNW, while South Korea and Taiwan will choose between PNW and Brazil depending on ocean freight rates.
- Other Southeast Asian countries are expected to continue buying mainly from South America. Overall, the buying pattern in Asia is expected to remain similar to December.
SOYBEANS
- Chinese state-owned companies continue to buy U.S. soybeans. USDA reported about 1.62 MMT of large sales to China between October 16 and 22. Total Chinese purchases of U.S. soybeans are estimated at around 16.6–17.0 MMT, supported by the political agreement between the U.S. and China.
- Chinese private crushers still prefer Brazilian soybeans due to their lower prices. Most U.S. soybean purchases are being made by Chinese state-owned companies.
- Planting of Brazil's 2026/27 soybean crop is progressing, and buyers are already looking at new-crop supplies. Soybean and soybean meal stocks in China remain high, which is limiting new buying interest.
- Most recent U.S. soybean sales have been for US Gulf shipments rather than PNW. The key point going forward is whether Chinese private crushers will start buying more U.S. soybeans, which could support demand from PNW.
WHEAT
- PNW had a moment in the past two weeks when we saw all three types of wheat not only connected to core demand but also to some elastic demand.
- Since then, all prices have rebounded, especially SWW. So now we all wait and see.
- The ceasefire and resumption of grain exports from the Black Sea are welcomed by all parties. Now we need to see to what extent they will be delivered.
- Some end users are receiving high-priced supplies that were secured in the last while. All of these need time to digest.
| | | | |