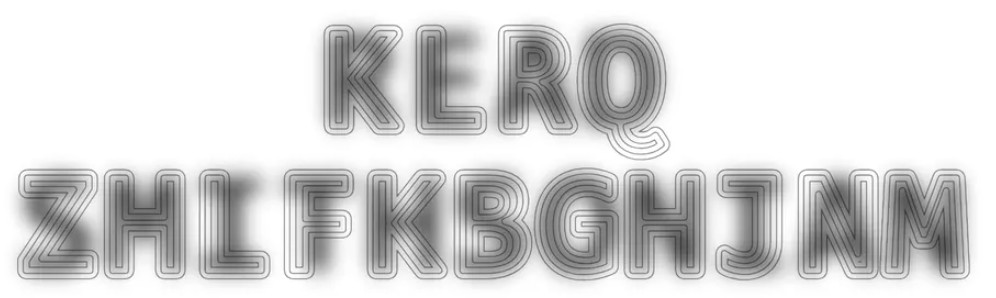| | |
Weekly Update
September 25th, 2026 - #574
| |
|
Get In Touch: 205.705.1655
| | | |
Welcome to the 574th Weekly Mortgage Update and Happy Dolly Parton Day 9-25 ...get it? Before we get to the rest of the update, I wanted to put our reminder in here again about our network of AWESOME, trusted, locally owned and operated companies to connect you to in order to help with your house. Whether you need help with a home inspection, a handy man project, HVAC help (fall equinox evidently didn’t change things much), or you need a dumpster to help your parents clean out 40 years of National Geographics and the World Book Encyclopedias circa 1987-88, reach out to us so that you don't have to worry... just give us a call! Don't risk just calling a random provider, who may ghost you or seem unreliable EVEN IF they come thru in the end… it can be frustrating.
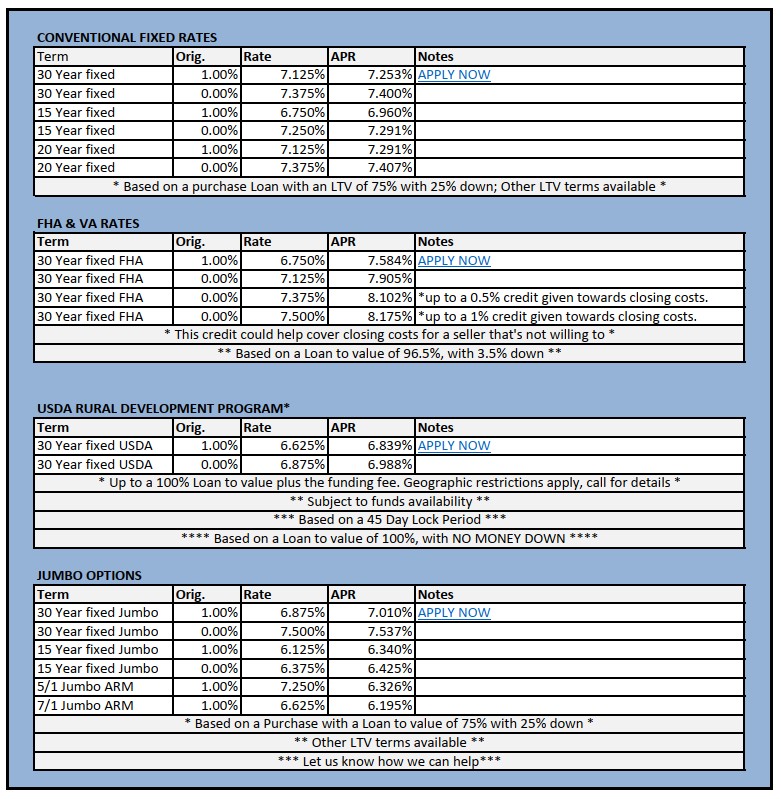
Now, back to the update. This week, rates worsened, but we're hoping that the improvement we saw today continues in the coming weeks. The rates are shown just above the trivia question. If you have questions about how these rates apply to your situation, let's talk. But gang as usual, there is LOTS GOING ON, SO LET'S GET STARTED!
| | |
CRAZY STORIES
Last week we learned that SEVERAL new words were being added to the dictionary as Merriam-Webster just added 1,400 new words and definitions, and it kinda reads like a fun scroll through social media in 2026. Words like vibe coding, parasocial, meme coin, and cuffing season are now officially official. There's also promposal, crashout, copium, and everyone's favorite backyard bandit (and Huntsville Baseball mascot), trash panda. Our favorite new entry might be AGI, which stands for artificial general intelligence, because nothing says "we live in the future" quite like the new and improved dictionary trying to catch up to the robots. If you want to feel old, yacht rock and glow-up are also now dictionary approved. Speaking of older rock, it’s like the great 80s and 90s poet, Steve Miller said that “time keeps on slipping (slipping, slipping) into the future…” whether we're ready or not. Our editors are unified in looking at the additional words to use in updates in the future AND to have the opportunity to REALLY REALLY impress some youngsters at Thanksgiving with your new HIP* vocabulary. (*PLEASE NOTE: to be hip, don’t use the word hip.)
Talk about “new dictionary, who dis?”
| | |
It’s not just the words in the dictionary that matter, it’s the words that AI can “read” in the dictionary. I’ve heard the joke that if we want to write in code that the youngest generation can’t read, we can use the cursive we learned in Mrs. Ross and Mrs. Denison’s 1st and 2nd grade writing classes. But evidently, we’re not trying to create codes Gen Z can’t crack, but how about codes that AI can’t crack?
Designers at a company called MixFont created "Decoy Font," which layers two messages on top of each other, so humans see one thing while AI reads something else entirely. Another design team released "ShieldFont," which swaps out roughly half the important words in a sentence so any AI trying to scoop up the text gets total nonsense instead. The goal is protecting human writing from being scraped and used to train AI without permission. It is a bit of digital camouflage, kind of like those magic eye pictures from way back in the day (which our head editor could never quite see) but the goal of this new version isn’t to see a magic picture of a horse or a sailboat, it's to keep chatbots confused. Technology fighting technology. Gang, what a time to be alive. Click KLRQ ZHLFKBGHJNM below to read more.
| | |
ANIMAL FUN (PART 2)
Last week we featured an Emu police chase and OF COURSE, the fan favorite and editor favorite, FAT BEAR WEEK, so wanted to include some new animal stories.
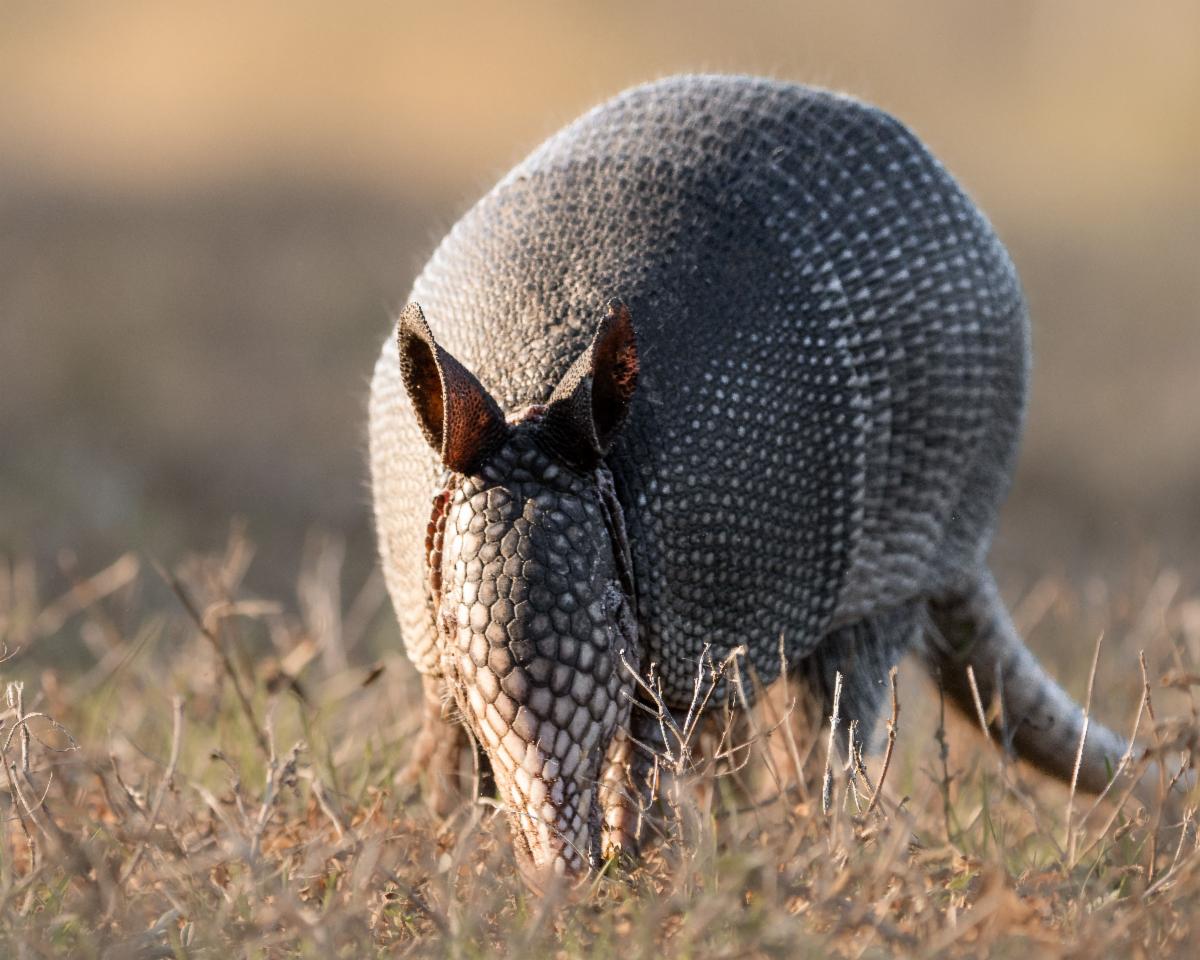
Armadillo would be a heck of a spelling bee word (I still remember getting out on QUOTIENT in 3rd or 4th grade after the kid next to me had to spell something like backpack, but I digress…) Anyway, armadillos are showing up in places they have never been before, including Ohio, where one was just found, making it the state's first ever naturally occurring armadillo. Experts say warmer winters are letting these armored critters creep north and east out of the South. They are already established in 17 states, and researchers expect Michigan, Wisconsin, and Virginia to be next. Evidently, armadillos are expanding what conferences they’re in to Big 10 and ACC country. A fun fact to file away: armadillos can jump more than four feet straight up when startled, so do not assume that shell slows them down. Click below to read more.
| |
| |
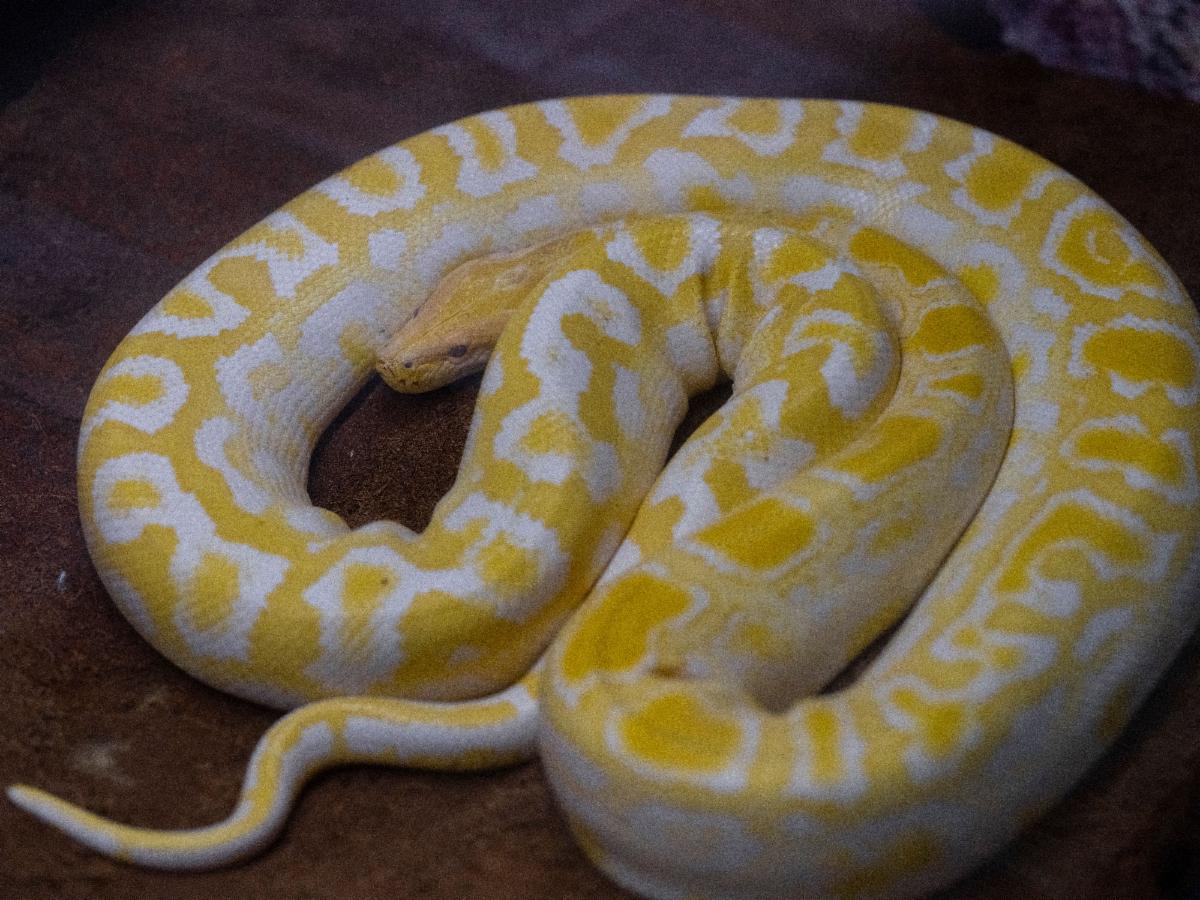
Armadillos can be a nuisance (did I mention they can JUMP four+ feet?) but this next one could be a menace if it got loose. I know many of you had to try out for a sports team as a kid, or audition for a play, or for a chair in a band or orchestra. Your competition was a kid you sat next to in homeroom or who lived down the street, sooooo… what if it was a giant boa constrictor?
At the Metropolitan Opera, for its new production of Mozart's "Cosi fan tutte," set at a 1950s Coney Island carnival, the Met needed a boa constrictor who could handle bright lights and a crowd, preferably, WITHOUT FREAKING OUT. After a formal audition process, a sun-colored boa named Princess landed the starring role, with a smaller boa named Nala cast as her understudy. Somewhere, a jilted snake’s villain origin story is starting to percolate… LOOK OUT!
| | |
REAL ESTATE TO BEHOLD
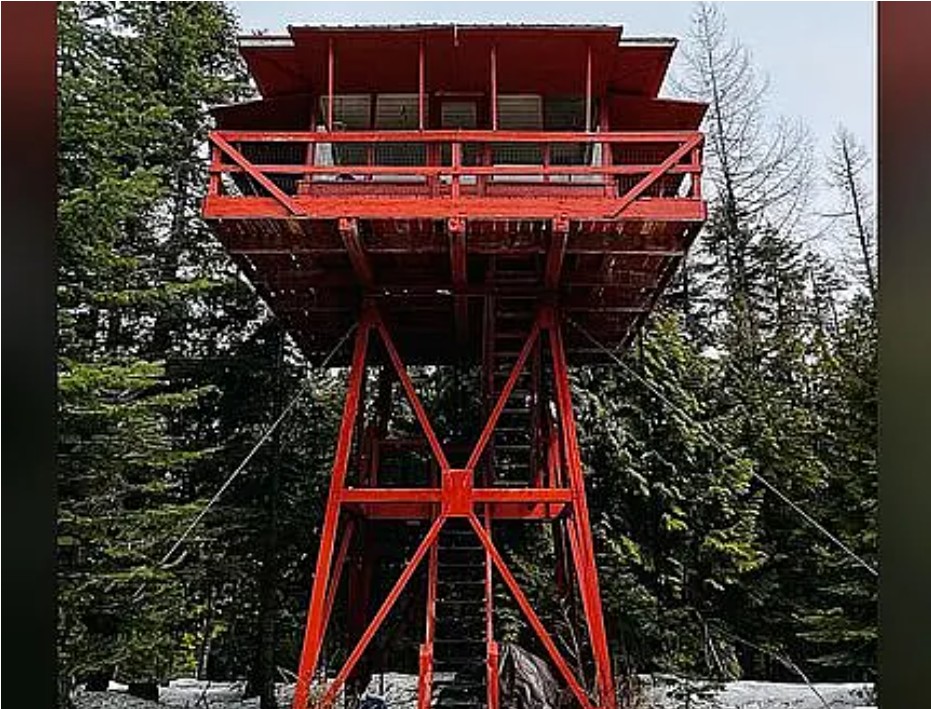
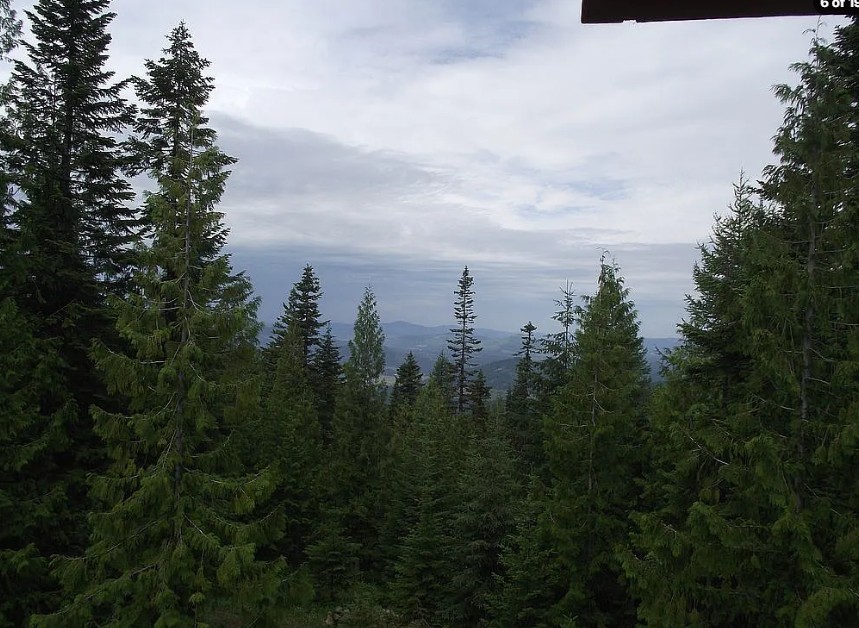
We’ve got some unique properties this week. First one REALLY appeals to our head editor after spending some time in Atlanta earlier this week enjoying the FINEST traffic along 285 and GA 400. So, this isolated QUIET lookout post was right up our alley. Perched on 12 private acres in North Idaho, this 1959 fire lookout tower comes with just one bedroom and 200 square feet of space, but it makes up for size with story. It has spent the last seven years as a short-term rental, pulling in about $75,000 a year with 790 reviews and a 4.89-star rating, so it could be a super cool rental to add to your property portfolio. The $480,000 price tag also includes a second lot, so the new owner could build a proper cabin and use the tower as their own personal crow's nest. It is proof that in real estate, interesting character and a killer view can be worth just as much as square footage.
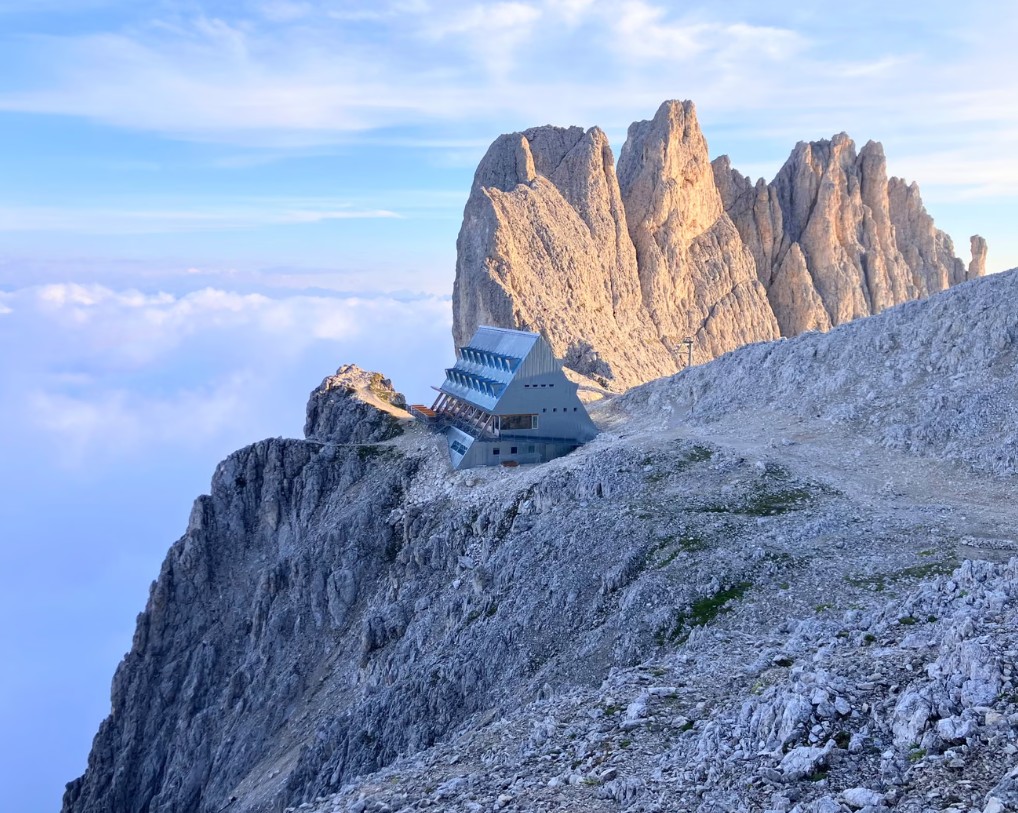
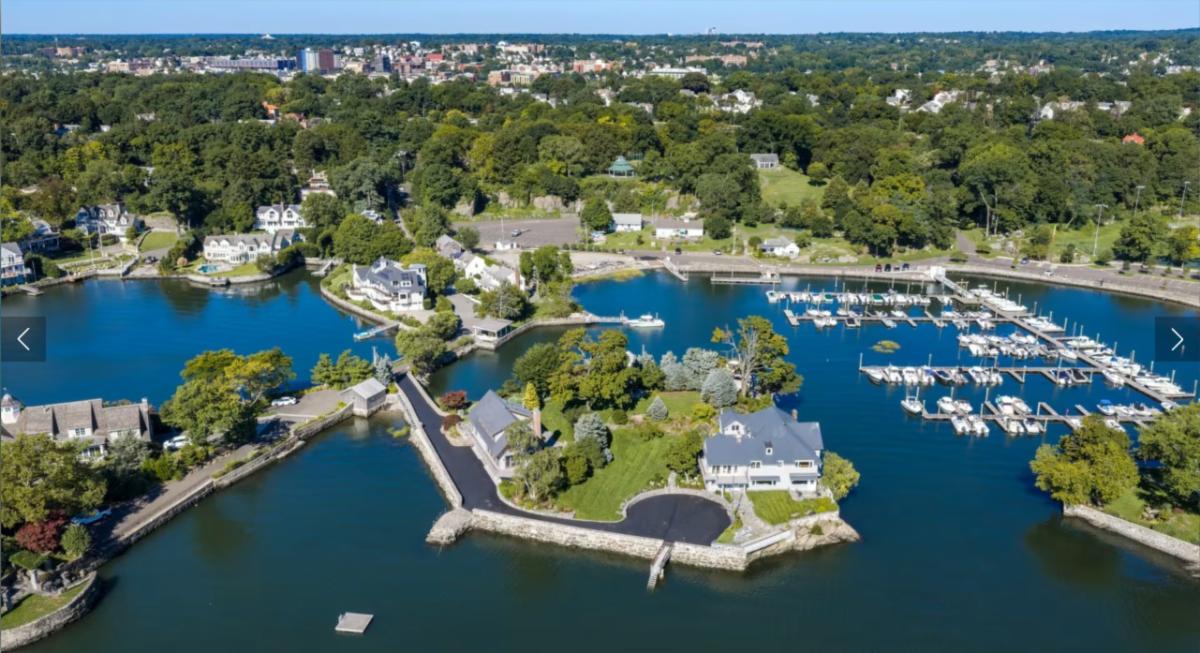
| | This next one technically isn’t for sale, but might be, for the right price, ESPECIALLY if you’re a bond villain... The Santnerpass Hut sits 2,734 meters up in Italy's Dolomite mountains, and you cannot drive to it, take an elevator to it, or helicopter in for a casual visit. You earn it with a three-hour hike. Once you arrive, you will find a striking A-frame structure wrapped in galvanized steel, looking like it was airlifted in from a spy movie set. Inside, hikers get cozy wood interiors, hearty South Tyrolean meals, and jaw dropping views in every direction. It is basically a bond villain's dream lair, minus the sharks with lasers. If you are looking for a real estate flex nobody else can match, "I own a mountain fortress" is hard to beat. | | If a fire tower and a mountain fortress are a little TOO isolated, how about your own island that is still commutable to the city? Farwells Island sits just off Greenwich, Connecticut, about an hour's drive from Midtown Manhattan, and it just returned to the market at $19.5 million. The 1.15-acre island has its own bridge to the mainland, a seven-bedroom main house from 1936, and a separate three-bedroom guest house sitting atop a five-car garage. The same family has owned it for almost 46 years, and the listing includes a clambake area, a private beach, a boathouse, and swimming piers you can walk right out to. The listing agent calls it a private Nantucket just 45 minutes from the city, and honestly, that is a pretty accurate pitch. It last hit the market in 2024 asking $25 million, so this is actually a bit of a deal… ish. | | |
THE ECONOMY AND REAL ESTATE
Let’s start with some good news. We got ADP's weekly jobs data Tuesday morning, and it is worth a look. This report tracks the average number of jobs added per week over a four week stretch, and for the four weeks ending September 5th, private employers added an average of 20,000 jobs per week. Stretch that out over a full month and you are looking at roughly 87,000 jobs created.
Now, we are still not talking blockbuster numbers compared to earlier this year, but the trend is what matters here. Back in early August, that same monthly pace was sitting around 40,000 jobs. Hiring has more than doubled since then, and this marks the third straight week of acceleration. For a job market that has felt sluggish for a while, steady improvement like this is a good sign. More hiring means more buyers with steady paychecks feeling confident enough to jump into the housing market, which is exactly the kind of momentum we like to see heading into fall.
| | |
And some rate news, which unfortunately wasn't good news this week. Let’s rip the band aid off, rates increased by almost a half a point over the past week, with the 30-year fixed hitting an average of 7.45% across the nation this week, the highest level in almost two and a half years.
Four things drove the spike. First, a surprisingly strong economic report on manufacturing and services from the S&P Global Report came out midweek well above expectations, and it flagged the highest inflation readings we have seen since 2022, contributing to thoughts that the Fed may need to increase rates further. Second, weak 5 and 7-year Treasury auctions further spooked fixed income investors. Third, Iran's president made pointed comments at the UN, ruling out any limits on the country's nuclear program, which further rattled markets already on edge. Finally, a Federal Reserve governor said he expects more rate hikes ahead and is not too worried about the job market, focusing instead on inflation. Put together, it was a recipe for increasing rates, but we will keep watching closely. Click below to read more.
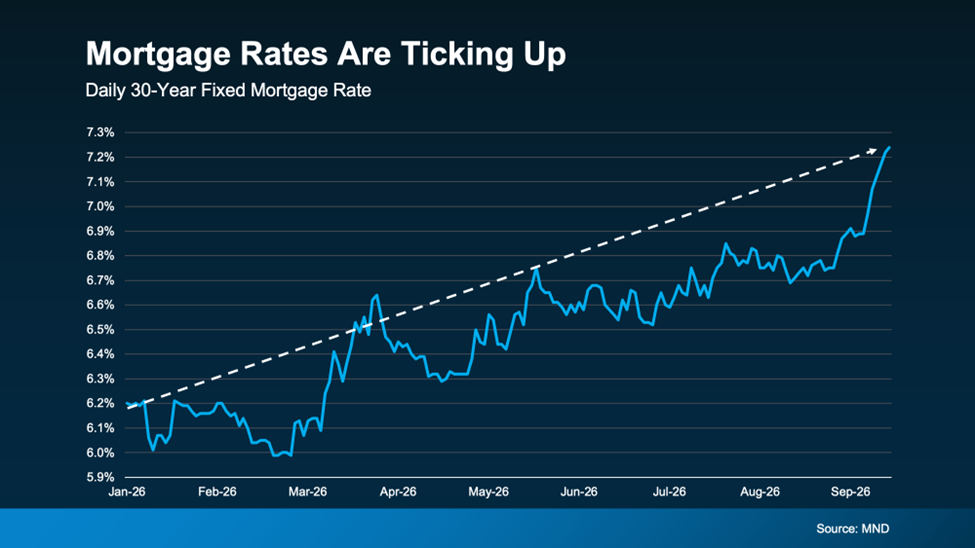
| | Obviously we let the cat out of the bag about rates above, as they have worsened some over the past few days (check out below the Keeping Current Matters article to see the full effect of the increase.) BUT, our friends over at KCM put together several things that you can impact to help your interest rate be the best it can be. To quote Jerry Maguire, “Help Me Help You!” Keep reading this week’s blog from KCM titled, “3 Things You Can Actually Control About Your Mortgage Rate.” | | If you're trying to buy a home, affordability is probably what keeps you up at night, and mortgage rates ticking back up lately does not help. Mortgage News Daily data shows how rates have climbed this year (see graph below): | |
Rates are being pushed higher by overseas events, economic data, inflation, oil prices, and recent Fed moves. As Danielle Hale, Chief Economist at Realtor.com, explains:
“The pressure on mortgage rates was here even before the Fed rate hike, and it doesn’t show signs of relenting. . .”
The good news is while you can't control where rates go, you can control several things that shape the rate you actually get.
Work on Your Credit Score
Your credit score plays a big role in your rate, and even a small bump can make a real difference in your payment. Freddie Mac puts it this way:
"Generally, the higher your credit score the more options will be available to you, including better loan terms and a lower interest rate."
If you're not sure where your score stands, talk to one of our trusted loan officer here at Method.
Explore Your Loan Options
The type and term of your loan both affect your rate. Conventional, FHA, VA, and USDA loans each have their own requirements, and your term, 15, 20, or 30 years, changes your payment and total interest. Fixed-rate loans hold steady, while adjustable-rate loans often start lower but can move later. As Bankrate explains:
". . . rates on fixed-rate loans are typically higher than introductory rates on adjustable-rate loans because the fixed-rate lender takes on the risk that rates could increase during the loan’s term. Likewise, government-backed FHA, VA and USDA loans sometimes have lower rates because they have a government guarantee or insurance that cuts the lender’s risk."
It’s important to explore your options with a lender to see what makes the most sense for you. Just be sure to balance your goals, your possible rate, and any potential tradeoffs before making any decision.
Consider a Newly Built Home
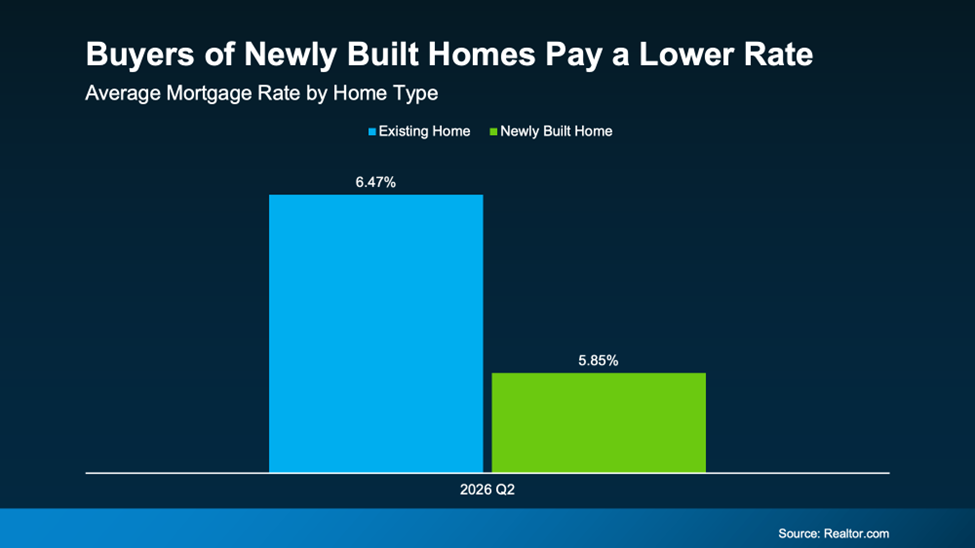
Another path to a lower rate comes down to the kind of home you buy. Many builders are buying down rates to help sell homes faster, which lowers your payment. Buyers of newly built homes landed a lower average rate last quarter than buyers of existing homes (see graph below):
| | |
Bottom Line
You can't control where mortgage rates go, but you can control your credit, your loan, and the kind of home you buy. Working with a trusted lender can help you lock in the best rate you qualify for.
When you're ready to make a move that fits your budget, let's connect.
| | |
RATES:
Pricing and rates remain erratic and volatile. Confirm rates & pricing directly with your loan officer.
| | Check out the trivia below and remember, there is a drawing to enter to win a gift card. This is your chance to enter for a chance to win the gift card awarded every other month. This trivia question is for the September & October drawing/card. | | |
TRIVIA QUESTION
TRIVIA QUESTION:
The fine folks at the Acquired podcast have dropped their most recent episode covering the history and financial metrics of The Home Depot. No other company has been as influential in the home improvement space, and Ross Perot PROBABLY regrets not keeping a deal together to own 75% of Home Depot (that and other fun facts available in the episode!) In spite of that deal not going through, I think Perot, Bernie Marcus and Arthur Blank all ended up just fine.
One of the OG founders of Home Depot, Bernie Marcus wrote an autobiography called ‘Kick Up Some Dust.’ What friend of Bernie’s wrote the foreword, introducing the book?
A. Pitbull
B. Ricky Martin
C. Eminem
D. Boutros Boutros-Ghali
E. Warren Buffett
Click here to EMAIL ME YOUR ANSWER.
**Email your answer to me to have your name entered in a drawing for a gift card at the beginning of even months and YES you can go back and answer previous weeks’ questions if you have not answered them already AND if we have not unveiled the answer yet***
| |
NMLS# 85408
601 Vestavia Parkway, Suite 300
Birmingham, AL 35216
205.705.1655
| |
| | | |