|
|
2024 • Quarter 2 • Issue 10 |
|
Robert Dumais
Principal, LBA
|
|
Friend,
I will begin the second quarter newsletter of 2024 with an apology - I’m sorry it’s late! If you have been holding your breath since the last one, please take a deep breath now. While I take no blame for the Washington Bridge disaster, the newsletter is on me!
In November it will be 9 years since I started LBA. What started small is now a real business that is really making a difference and I’m very thankful for all the folks that have put their faith in me and in the amazing team that we have assembled.
I would also be remiss without a special shout out to my friends in the RI Labor Community, we appreciate and never take your support for granted.
At LBA we take the retirement process very seriously. There are many opportunities for errors that unfortunately might be irreversible.
I recall a gentleman that I spoke to several years ago. He was in his mid-70s, said he was not married, had no children and has wanted to retire for a while but “he didn’t know how”. When I think about that discussion, I think that there are lots of reasons why someone may delay retirement, but knowledge should not be one of them.
If you want to retire and you’re not sure how, we are just a phone call away!
Be well,
Bob Dumais
Principal, LBA
|
|
|
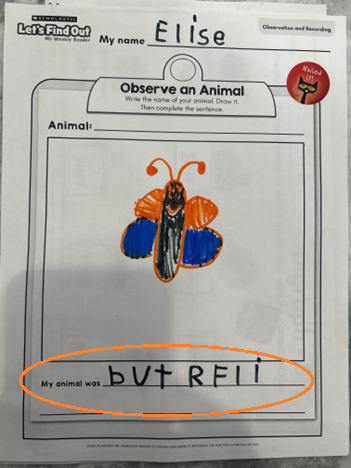
My granddaughter is 5 and her logic makes complete sense to me.
No need for a glossary or a "how-to" guide.
Why do the adults make things so complicated?
|
|
|
|
LBA 911
Your Medicare Selection Is THAT Important
|
|
Choosing the right Medicare plan is a crucial decision that impacts individuals in various ways, encompassing health, lifestyle, and budget considerations. Various Medicare plans offer coverage at different levels, each with varying co-pays and deductibles. However, the significance extends beyond the financial aspects.
Another critical aspect to consider is the network of healthcare providers accessible to you with each plan. In the event of an emergency, most plans provide very good coverage, regardless of where you get the care. However, when medical procedures are elective, different plans may have distinct networks, affecting where and how individuals can access healthcare services. This aspect is particularly vital for individuals with specific healthcare needs or preferences for certain doctors or hospitals. Limited networks can pose challenges and potentially restrict access to preferred healthcare providers or facilities. If for example, the most renowned physician or hospital to deal with your medical condition is out of your plan’s network, you may face the difficult decision of going to an alternate next-best provider, or paying the bill out of pocket.
Another important consideration is the formulary of medications covered by each Medicare plan. Formularies vary between plans and may limit or financially burden individuals in accessing the medications they require. This can be particularly concerning for those with chronic conditions or complex medication regimens. In other cases, your particular medication may be covered within the formulary, however, it may be in a different tier with one carrier versus another, making your cost for the medication significantly different.
Ultimately, the right Medicare plan aligns with an individual's health, lifestyle, and budget. It's essential to thoroughly evaluate and compare different plans to make an informed decision that optimizes healthcare access and affordability, while meeting specific health and lifestyle requirements.
The advisers at LBA are licensed, certified, insured, and independent, making them very equipped to address your specific needs.
|
|
|
These exceptions are subject to specific conditions and eligibility criteria. Talk with an LBA advisor for the most accurate and up-to-date information tailored to your individual circumstances. |
|
AVOIDABLE RETIREMENT MISTAKES |
|
Underestimating Expenses
Failing to accurately estimate retirement expenses, including healthcare costs, travel, leisure activities, and unexpected expenses, leading to financial strain during retirement.
Inadequate Savings
Not saving enough for retirement or starting retirement planning late, resulting in a shortfall in retirement funds and reliance on limited income sources.
Ignoring Inflation
Neglecting to account for inflation's impact on purchasing power over time, which can erode the value of savings and affect retirement lifestyle.
Poor Investment Decisions
Making risky or uninformed investment decisions, such as chasing high returns or not diversifying investments, which can lead to losses and lower retirement income. We call it “Age-Appropriate Investing”.
Early Withdrawals
Withdrawing too much of your retirement savings too early; you’re in it for the long haul and you don’t want to deplete your savings too soon.
Delaying Healthcare Planning
Not adequately planning for healthcare costs, including long-term care needs, insurance coverage, and potential medical emergencies, can strain finances in retirement.
Ignoring Tax Implications
Failing to understand the tax implications of retirement income sources, taking withdrawals from retirement accounts, and poor estate planning can all lead to unnecessary taxes and reduced income.
Overestimating Social Security
Relying too heavily on Social Security benefits without considering other income sources or potential changes to Social Security funding or benefits.
Not Having a Plan
Lack of a comprehensive retirement plan, including budgeting, income sources, investment strategy, estate planning, and contingency plans, can lead to financial insecurity and uncertainty in retirement.
|
|
At LBA we suggest that you hope for the best,
but prepare for the worst!
|
|
Uncle Sam, Are You Listening |
If you wondered, how broke Social Security is, the experts say “very broke”. After 2034 the near $3 trillion trust fund will be depleted if no legislative action is taken. |
|
|
The good news is that there are some proposed policy changes that voters on both sides of the aisle support. Arranged by their level of support, they are as follows:
- Raising the payroll tax cap. (81% support)
- Reducing benefits for high earners. (81% support)
- Raising the retirement age. (75% support)
- Increasing the payroll tax rate. (73% support)
- Raising the minimum benefit. (64% support)
- Changing the cost-of-living adjustment. (55% support)
- Increasing benefits for the very old (53% support)
When you look at the list, note that the last 3 actually suggest payout increases to certain beneficiaries.
We will keep a close watch to see where the discussion goes, but it is good to see that discussions are actually taking place.
|
|
|
|
Unfortunately, no one is exempt from the pressure inflation is putting on their lives. Whether it’s paying for groceries, or gasoline, or paying utility bills, inflation is a persistent problem with no end in sight. While there’s lots of reasons for inflation, all we can control is how we deal with it.
Here are some financial strategies to help deal with inflation:
|
|
Diversify your investment portfolio
Diversification across asset classes can help mitigate the impact of inflation during inflationary periods.
Review and adjust your budget
Regularly review your budget to identify areas where you can cut back or optimize spending. Focus on essentials while being mindful of rising costs in sectors like healthcare and utilities.
Consider delaying Social Security
Delaying Social Security benefits as long as possible can increase your monthly payments when you eventually claim them.
Invest in inflation-protected securities
Consider allocating a portion of your portfolio to securities like Treasury Inflation-Protected Securities (TIPS). These investments adjust their principal value based on changes in the Consumer Price Index (CPI).
Explore supplemental income options
Consider generating supplemental income through part-time work, freelance opportunities, or rental income from properties.
Consult with a financial advisor:
A second opinion is always helpful. Seek guidance from a qualified advisor who can assess your specific financial situation, goals, and risk tolerance.
|
|
By implementing these strategies and staying vigilant about your financial planning, you can better prepare for and manage the impact of inflation. A consultation with an LBA advisor is free, let’s talk! |
|
LBA consultants aremembers of
OPEIU Local 25
|
|
Robert Dumais, Principal
275 West Natick Road
Suite 450
Warwick, RI 02886
401-868-1400 (O)
774-991-3369 (M)
401-737-0330 (F)
|
|
|
P.S. Add me to your contacts so we can continue to keep you in the know and don't hesitate to hit "reply" to contact us. |
|
|
|
|
|
|