The Pensioner: Looking Forward
|
|
Welcome to the digital MPERS newsletter! The Pensioner: Looking Forward contains news, updates, and important information for active employees of the Missouri Department of Transportation, the Missouri State Highway Patrol, and MPERS.
|
|
The Pensioner: Looking Forward Turns One!
|
|
One year ago, MPERS decided to take a different approach to inform our members of upcoming events, notable achievements, informational articles, investment updates, benefit information, and much more. How could we accomplish this and make it easy for our members to receive this information quickly and without taking too much of their time?
The digital version of The Pensioner: Looking Forward was born!
We hope that you have enjoyed receiving this monthly newsletter and look forward to many editions to come!
In honor of the one-year anniversary, we would like to take a moment to thank you for your readership as well as request that you take the short poll below.
|
|
|
Do you find the content of The Pensioner: Looking Forward relevant to active employees?
|
|
|
|
Is there a topic you would like to see covered in The Pensioner: Looking Forward? Send a quick email to Julie.West@mpers.org and share your ideas!
|
|
2021 Financial Status Update |
|
How did the System fare during the 2021 fiscal year? Watch the 2021 Financial Status Update to find out! |
|
MPERS Receives Two Awards! |
|
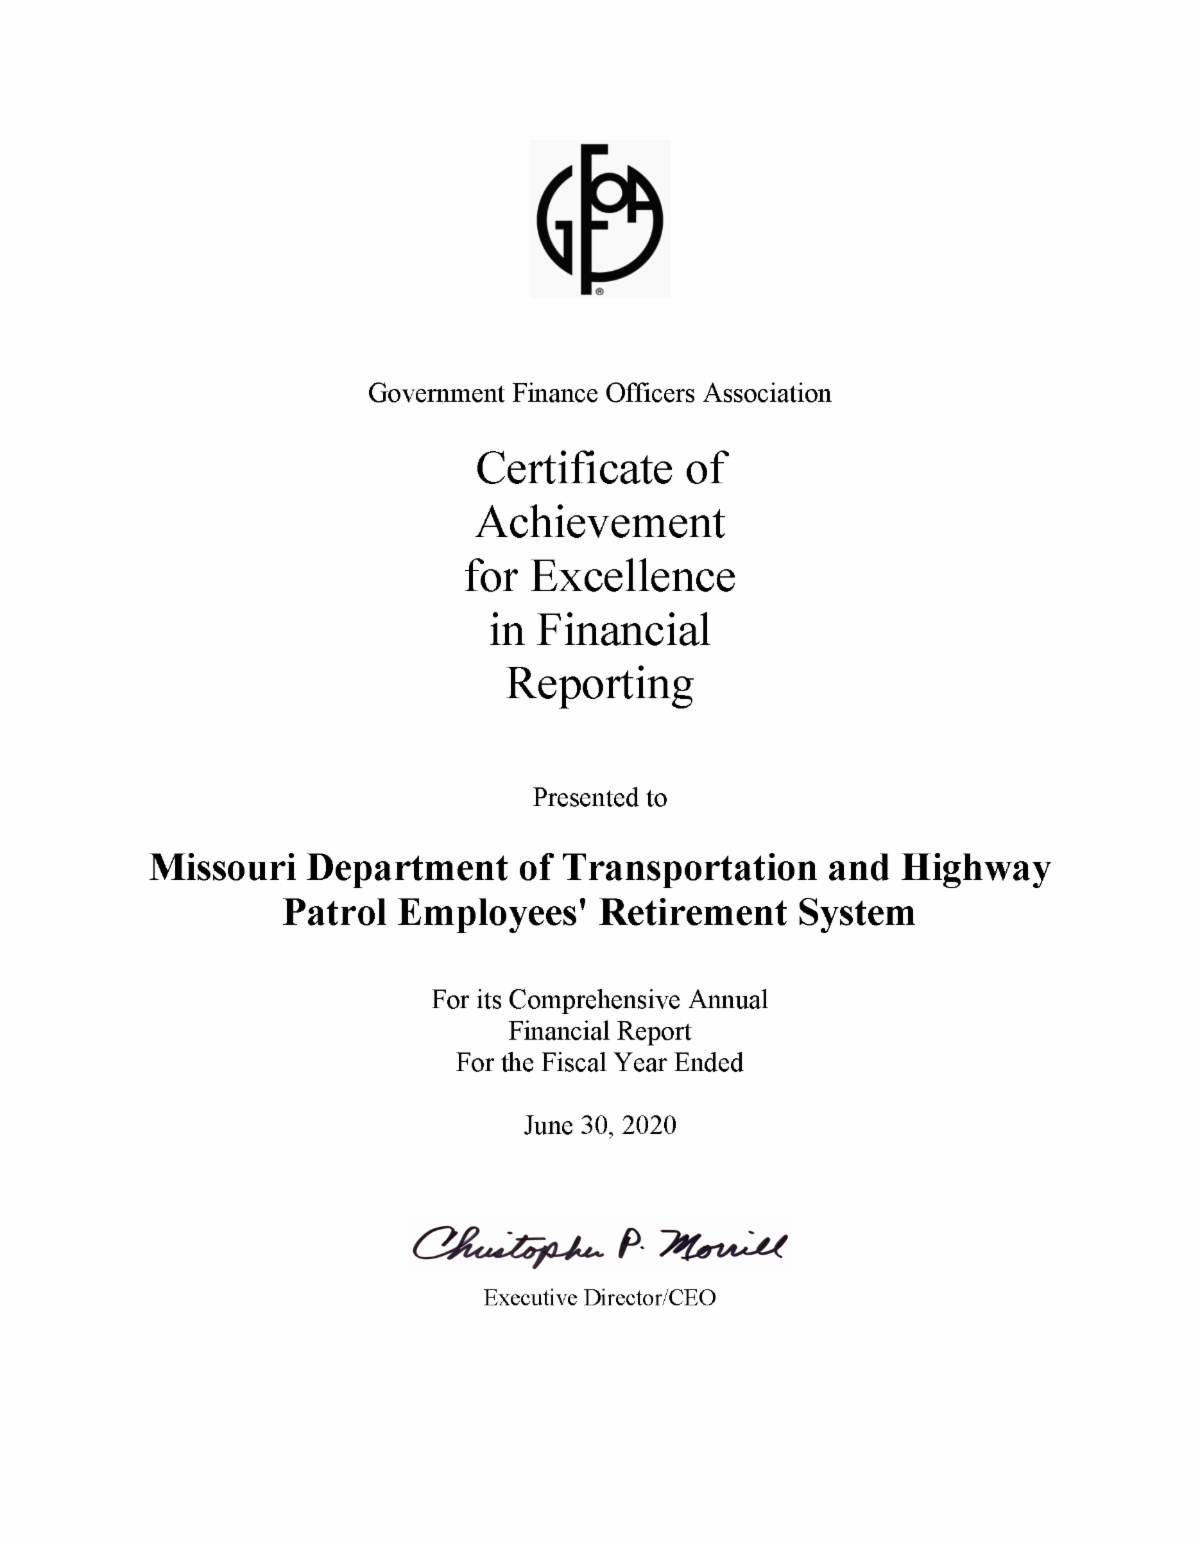
Certificate of Achievement for Excellence in Financial Reporting |
|
|
|
This Certificate of Achievement is the highest form of recognition in the area of governmental accounting and financial reporting, and its attainment represents a significant accomplishment for MPERS' management and staff.
|
|
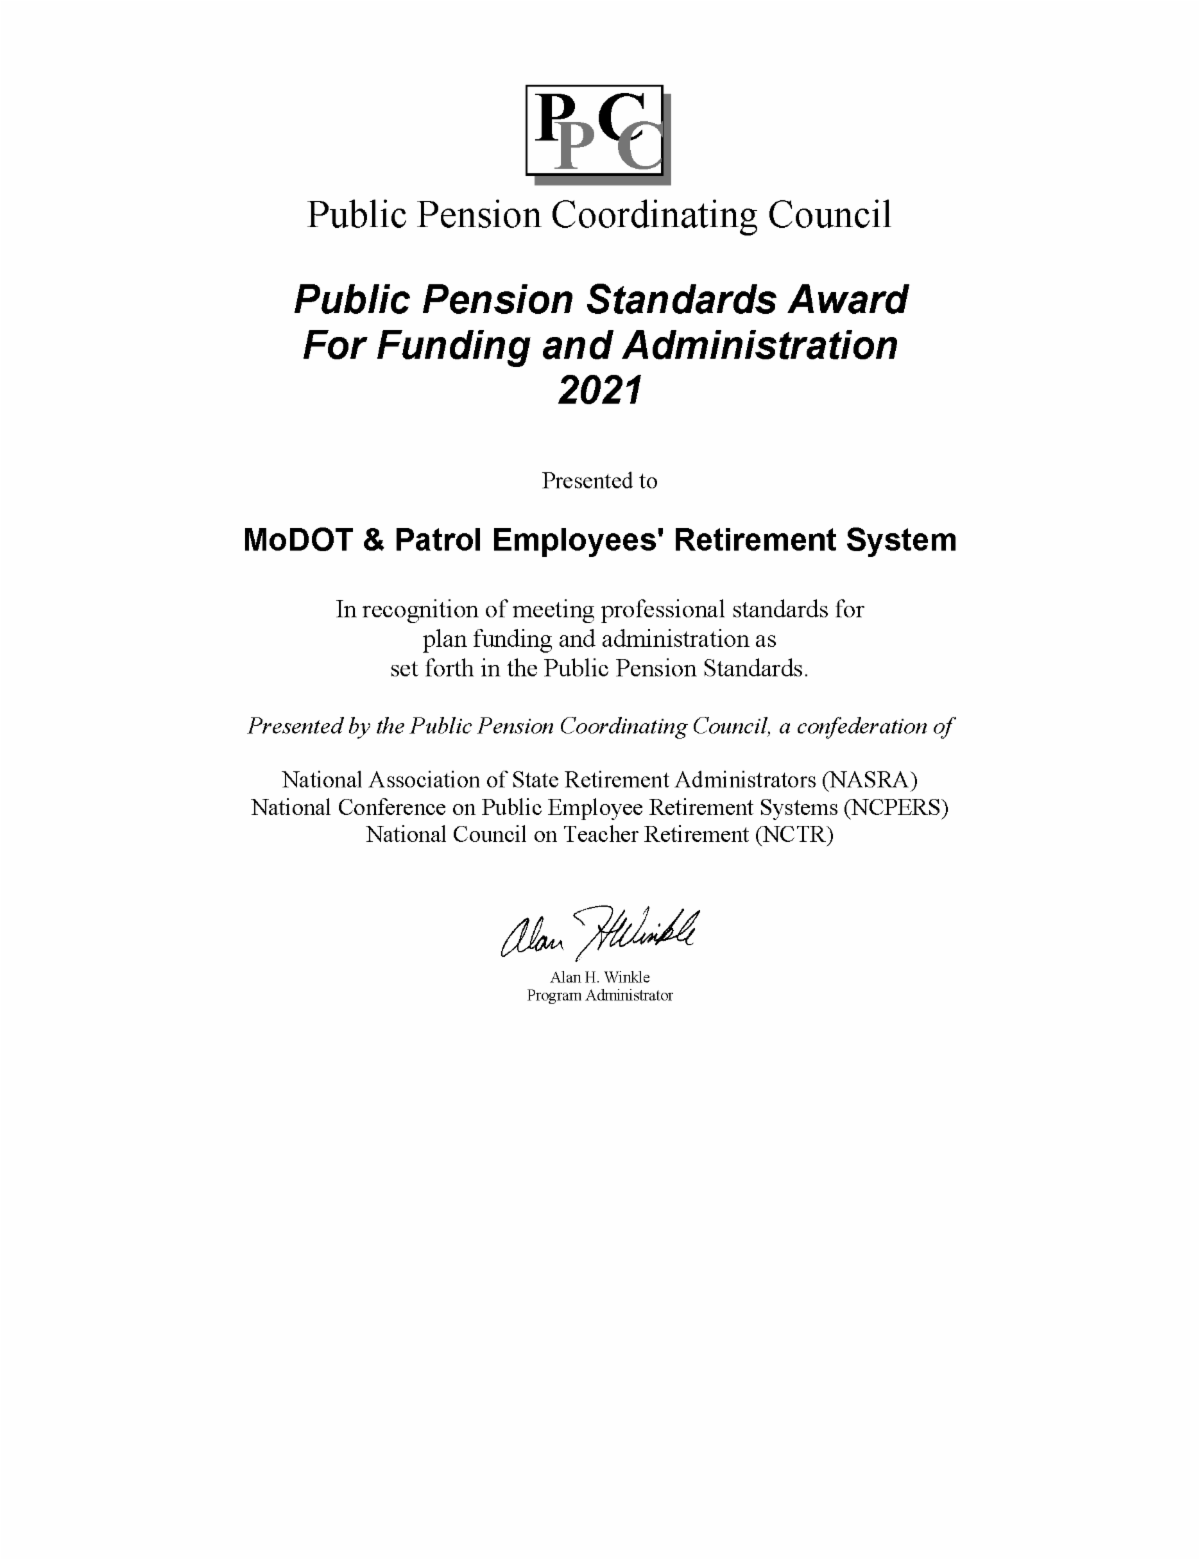
Public Pension Standards Award for Funding and Administration |
|
|
|
MPERS received the Public Pension Coordinating Council’s Public Pension Standards Award each year since 2004. The award is given in recognition of meeting professional plan design and administration standards.
The Public Pension Coordinating Council is a confederation of the National Association of State Retirement Administrators (NASRA), the National Conference on Public Employee Retirement Systems (NCPERS), and the National Council on Teacher Retirement (NCTR).
|
|
In the March edition of The Pensioner: Looking Forward, the oversight formula was introduced: |
|
In the oversight formula, contributions plus investments equals benefits plus expenses. Over the upcoming months, we will be looking at the benefit portion of the formula.
While MPERS pays monthly, lifetime retirement benefits to retirees and survivors, it also pays disability and death benefits.
MPERS administers three plans: the Closed Plan, the Year 2000 Plan, and the 2011 Tier.
|
|
The Closed Plan and the Year 2000 Plan are non-contributory, which means that the employee doesn’t financially contribute to the MPERS retirement benefit. Once eligible for retirement, vested members will receive a benefit for their lifetime. During the retirement process, members can choose among various payment options to provide survivor benefits to a spouse or another individual. In addition, eligible members may elect BackDROP, which will provide a lump sum in addition to a reduced monthly payment. Regardless of the payment option selected, vested members will receive a benefit for their lifetime. |
|
The 2011 Tier is very similar to the Closed and Year 2000 plan except that it is a contributory plan. Members of this tier are required to contribute 4% of their salary to the MPERS trust fund to help fund their future retirement benefit. Like the other plans, upon retirement, a vested member may elect from a number of payment options that will provide survivor benefits to a spouse or another individual. There is no option for a lump sum payment for this tier. Individuals who do not vest or who terminate employment prior to reaching retirement eligibility may request a refund of their contributions.
In the event a member is unable to work and is approved for work-related or long-term disability, MPERS (or the designated disability insurer) will pay disability benefits until the individual is eligible to retire, then in most cases, the member will choose to “retire” and then receive retiree benefit payments.
Another benefit MPERS pays is the $5,000 death benefit. This benefit is paid to a designated beneficiary after the member has passed away. This benefit is only available to those who have retired directly from active service or became normal or work-related disability recipients after 9/28/1995. This benefit does not carry over to the survivor.
Below is a snapshot of some of the benefits paid in the 2021 fiscal year.
|
|
Retiree and survivor benefits paid
$ 250,420,018
|
|
BackDROP payments
$13,585,357
|
|
Death benefits
$1,255,000
|
|
Next month we will explore the cost of the benefits component of the oversight formula. |
|
Check Out This Month's Benefit Bite!
|
|
|
|
Defined Benefit vs. Defined Contribution
What Does it All Mean????
|
You have probably heard us say that MPERS is a defined benefit plan more than once. Why do we frequently mention that tidbit? Because it is important! |
|
In the pension universe there are two main types of retirement plans: defined benefit and defined contribution. |
|
In a defined benefit plan, once employees meet certain age and service requirements, they may retire and receive a lifetime benefit. The benefit is determined by a formula that includes components such as credited service, a multiplier, and final average pay. This benefit is paid for the lifetime of the retiree and in some cases, the lifetime of a surviving spouse.
Typically in a defined benefit plan, lifetime benefit payments will be made regardless if employee contributions are involved.
|
|
In a defined contribution plan, such as a 401(k), the employer may contribute a certain amount to each employee's retirement, and in some cases, they may even match the amount the employee contributes. As the employee's career progresses, the account continues to build through employee/employer contributions and investment earnings on the account. When the employee retires, he/she can then draw the retirement benefit out of the account.
Once all funds have been paid out and the account depleted, the benefit will stop.
|
|
All three of MPERS plans (the Closed Plan, the Year 2000 Plan, and the 2011 Tier) are defined benefit plans and once you meet certain age and service eligibility requirements, you may choose to retire and begin receiving your monthly benefit for LIFE.
The 2011 Tier is slightly different because there is an employee contribution component to the plan. Employees in the 2011 Tier are required to contribute 4% of their salary towards their future retirement benefit; however, the benefit is still payable for LIFE regardless of the balance in the contribution account.
|
|
If you would like to participate in a defined contribution that can help supplement your MPERS pension in the future, the MO Deferred Comp plan is an excellent way to save more for retirement. |
|
myMPERS Secure Member Access
Multi-Factor Authentication
|
|
The safety and security of member and stakeholder personal information is something we take seriously at MPERS. In the coming months we will be implementing an additional security measure called multi-factor authentication to the myMPERS (secure member access) login process. This is in response to the ever-changing internet security environment.
In the coming months, upon logging in to your myMPERS account, you will be prompted to choose your preference(s) for MFA.
Please remember, it has not taken effect just yet, so proceed as normal. Once it has been fully implemented, we will be available to assist with the transition and any questions you may have.
|
|
- 4 - Pre-Retirement Webinar for Closed Plan and Year 2000 Plan members - Register here
- 11 - Veterans Day-office closed
- 16 - Pre-Retirement Webinar for 2011 Tier members - Register here
- 18 - Board meeting
- 26 - Thanksgiving-office closed
-
30 - Deadline to submit step 1 - Notice of Retirement for January1 retirement
|
|
We value your feedback!
What would you like to see in The Pensioner: Looking Forward?
|
|
|
|
|
|
|