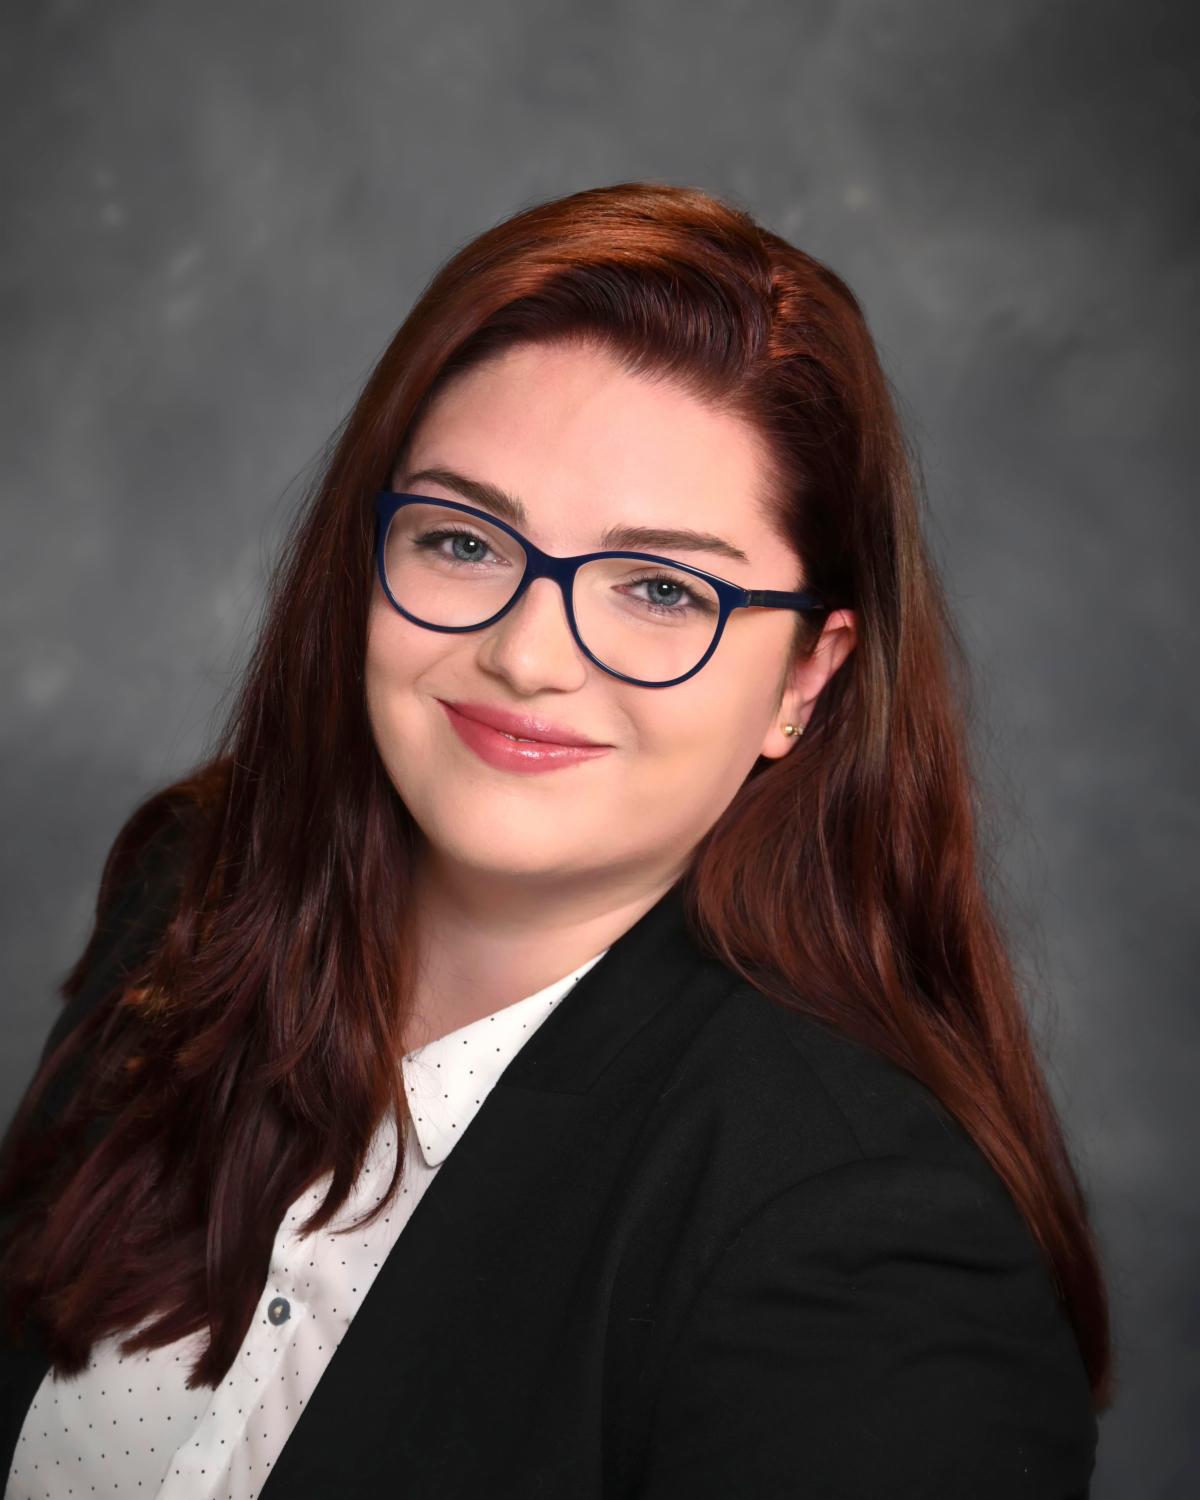
Willa Mankins is a litigation associate with Corey, Luzaich, de Ghetaldi & Riddle LLP. Ms. Mankins’ practice includes business litigation, employment litigation, complex and mass tort litigation, and trust and estate litigation.
Ms. Mankins graduated with a B.A. in English Literature and B.S. in Biopsychology during her four years at Mills College. She earned her Juris Doctorate from the Santa Clara University School of Law.
Since graduating from college, Ms. Mankins has published multiple scientific research papers and plans to publish in the legal field as well. She is currently a Board Member of the San Mateo County Trial Lawyers Association.
|
|
New Year, New CA Minimum Wage
With the new year comes new California minimum wage increases. These increases will affect both the pay rate of non-exempt hourly employees and the minimum salary of overtime-exempt employees. Starting January 1, 2023, the new state minimum wage for non-exempt employees will be raised to $15.50, and the minimum annual salary for overtime-exempt employees will be raised to $64,480.
Some cities and counties within the state have their own local minimum wages ordinances which are higher than the state minimum. It is important for both employers and employees to check local minimum wage laws to ensure proper wages are being paid. While these local minimum wage rates may give non-exempt employees a rate of pay higher than the state minimum, overtime-exempt employees do not need to be paid a salary higher than the state minimum of $64,480. Specific local minimum wage rates can be found online on your respective city or county website. For convenience, UC Berkely maintains a list of city and county minimum wages in California which can be found at this link: California City & County Minimum Wage.
Additionally, California has done away with the two-tiered minimum wage classification policy which previously allowed employers with 25 employees or less to pay a lower state minimum wage. Effective January 1, 2023, all employers will be required to comply with the new state minimum wage rate regardless of size. Some cities and counties have opted to keep tiered minimum wage classification policies based on the size of the employer. These policies comply with the new state laws if the lowest wage tier is at least the state minimum of $15.50.
California's New Pay Transparency Law
On January 1, 2023, California's new pay transparency law will affect applicants, employees and employers alike. The new law requires employers with 15 or more employees to include the pay scale (defined as salary or hourly wage) for a position in any job posting. The law also applies to employers with 15 or more employees that engages a third party to make job postings. Existing law already required an employer to provide this information, upon reasonable request, to an applicant applying for employment. The new law would also require an employer, upon request, to provide an employee the pay scale for the position in which they are currently employed. Under SB 1162, employers are now required to maintain records of a job title and wage rate history for each employee. Failure to keep these records is considered a violation but most notably the new law creates a rebuttable presumption in favor of the employee's claim.
California law already requires a private employer with 100 or more employees to submit a pay data report to the California Department of Fair Employment and Housing (DFEH). The new requirement now expands to cover employers that have hired 100 or more individuals through labor contractors in the Reporting Year. Labor contractor in this case meaning, an individual or entity that supplies a contract employer with workers to perform labor within the client employer's usual course of business. Additionally, SB 1162 requires the pay data reports to now include the median and mean hourly rate for each combination of race, ethnicity, and sex within each job category. The employer's failure to submit the required report may result in a $100 penalty per employee and not to exceed $200 for a subsequent failure to submit the required report.
What this means for the prospective California job applicant is that she may request the hourly wage of the position she is applying to, and the employer must be ready to produce that information. If she is job searching on a website such as Indeed.com, and the job posting comes from an employer with 15 or more employees, that job posting must have the salary or hourly wage. This also means all current employees may now request the pay scale range for their held position and their employer must provide it. Finally, with all these changes, employers may want to take the appropriate steps to be in compliance with the law whether that means ensuring their pay data is up to date or including the salary on a job posting.
Employers can take several steps to protect themselves from liability in this area. For questions regarding minimum wage and employee compensation, or other employment law issues, contact a member of our employment law team: Amanda L. Riddle, Steven M. Berki or Sumble Manzoor.
|
|
New IRS Rule Allows Some Estates to Save on Estate Tax
The IRS has adopted a new rule that will allow some widowed taxpayers to transfer larger estates to their children and other beneficiaries without having to pay estate tax. If you believe your estate may be valued in excess of $6 million by the time of your eventual passing, and if you have a predeceased spouse who died less than five years ago, this rule change could potentially save you a lot of money.
Existing Rules
U.S. citizens and residents are allowed to pass a certain amount of assets to non-charitable beneficiaries, either during their lifetimes or upon their deaths, without paying estate or gift tax. This amount is called the “basic exclusion amount.” A 2017 law doubled the exclusion amount from $5 million to $10 million, and the amount is indexed for inflation. For taxpayers dying in 2022, this amount is $12,060,000. (There is an unlimited marital exemption for such gifts, so transfers of any size can be made between spouses without triggering a tax obligation).
At the end of 2025, however, a “sunset” provision in the 2017 law will cause the exclusion amount to drop to what it would have been if the 2017 law had never been passed. By most estimates, the new exclusion amount for 2026 will likely be a little over $6 million, which means it will affect a lot more families than it does now at $12 million.
There is another law that allows the estate of a widowed taxpayer to take advantage of any unused portion of their predeceased spouse’s basic exclusion amount. This is called a “portability election,” and the election is made by filing an estate tax return (IRS Form 706) for the predeceased spouse. For example, if the first spouse died in 2020, when the basic exclusion amount was $11,580,000 and none of the exclusion was used because that spouse’s entire estate passed to his or her surviving spouse, that entire exclusion amount would be available when the surviving spouse eventually died, but only if an estate tax return (IRS Form 706) was timely filed.
If the surviving spouse died after the end of 2025, when the basic exclusion amount might be, for example, $6 million, and if the surviving spouse’s estate was worth, for example, $7 million, the estate would have to pay estate tax on the $1 million excess over the exclusion amount. Under current law, the applicable tax rate would be 40%, so the tax would be $400,000. In the same example, if a timely portability election had been made on an estate tax return for the predeceased spouse, the tax would be zero, because the exclusion available to the surviving spouse’s estate would be $17,580,000, which is the surviving spouse’s basic exclusion amount ($6,000,000) plus the predeceased spouses’ basic exclusion amount ($11,580,000) which was “ported” or transferred to the surviving spouse.
The New Rule – Extending Deadline to File from Nine Months to Five Years
The key to taking advantage of the predeceased spouse’s exclusion amount is making a timely portability election by filing an estate tax return for the predeceased spouse. Until the new rule was adopted, that estate tax return would have to have been filed within nine months of the predeceased spouse’s date of death. The new rule extends that deadline date to five years after the predeceased spouse’s death, so long as the only reason the return is being filed is to make the portability election. (If, however, the estate of the predeceased spouse is required to file an estate tax return for any reason, the deadline is still nine months after the date of death, although a six-month extension is generally available).
Although the deadline might be long past for filing a required federal estate tax return, any widow or widower whose spouse died in 2018 or later still has an opportunity to file such a return for the purpose of making a portability election that could potentially save a substantial amount of estate tax.
|
|
Community Spotlight
Corey, Luzaich, de Ghetaldi & Riddle LLP actively supports many non-profit organizations in the Bay Area. In this edition, we want to draw readers’ attention to the Millbrae Community Foundation. The Millbrae Community Foundation was created to enhance the lives of all who live in the community. They are a volunteer organization that raises money for and gives grants to projects that fulfill the unmet needs of the community's citizens. They work independently of government, and collaboratively with organizations that serve Millbrae and its people.
|
|
Employment Law Litigation
When issues arise, our attorneys focus on early intervention to resolve problems within the business before the issue escalates ...
|
|
Business & Commercial Transactions
Since 1964, our firm has provided tailored advice to business clients of all sizes. From sole proprietorships to Fortune 500 companies ...
|
|
Probate & Trust Litigation
Along with the provision of estate planning legal services, we have extensive experience litigating matters resulting from estate disputes involving ...
|
|
Millbrae Office
700 El Camino Real
Millbrae, CA 94030
Phone: (650) 871-5666
Email: info@coreylaw.com
|
|
Half Moon Bay Office
625 Miramontes Street, Suite 106
Half Moon Bay, CA 94019
Phone: (650) 726-7578
Email: info@coreylaw.com
|
|
|
|
|
|
|