|
Weaker Jobs Could Restrain the Fed
Greetings!
Nobody likes to hear that the economy created far fewer jobs than expected. The Bureau of Labor Statistics reported that employers added only 29,000 jobs in September, while July and August were revised down by a combined 60,000. Average hourly earnings rose just 0.1% for the month and 3.0% from a year earlier, the smallest annual gain since May 2021. Put together, the numbers show a labor market that is clearly losing some momentum.
With inflation still running slightly ahead of wage growth, more people may be feeling pressure to enter or re-enter the workforce. The labor-force participation rate rose 0.2 percentage points to 61.8%, its highest level since May. But hiring was weak across most major industries, so there were not enough new jobs to absorb everyone entering the workforce. As a result, the unemployment rate ticked up to 4.2%.
While a weaker job market is concerning, it could have one potentially helpful side effect for borrowers. A softer labor market may reduce the pressure on the Federal Reserve to raise its benchmark rate again at its October 27–28 meeting. That could help limit some of the upward pressure on borrowing costs, although it does not mean mortgage rates will suddenly fall.
Working Around Higher Rates
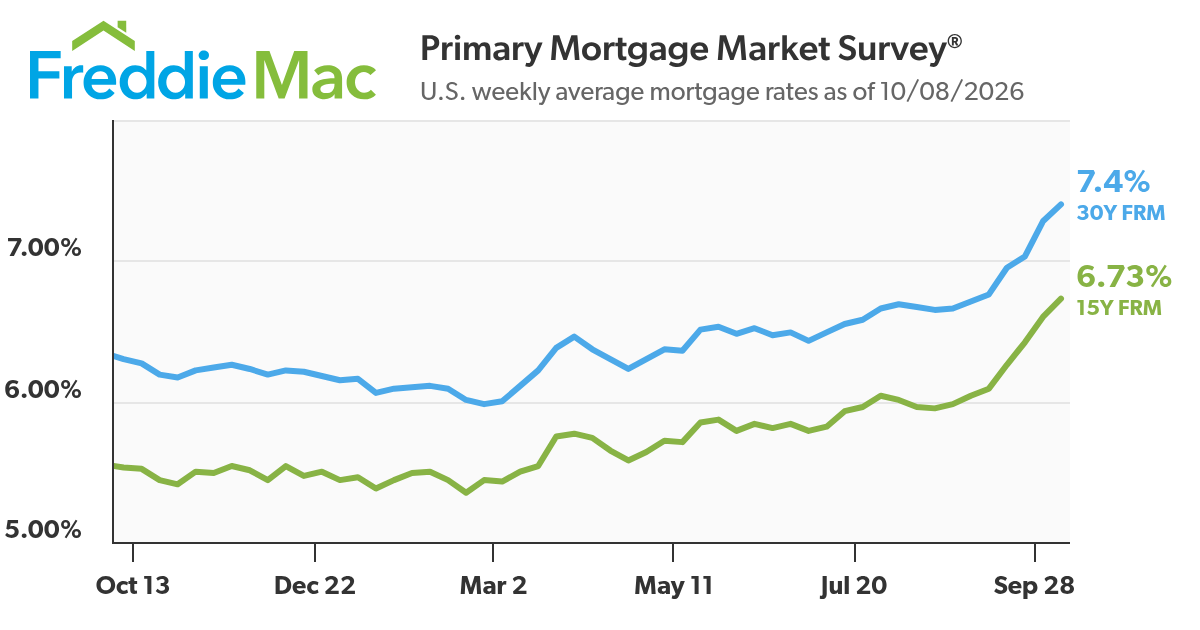
For now, those who need or want to buy still have to deal with a challenging rate environment. Last week, mortgage rates—influenced by rising Treasury yields—climbed to their highest level in three years. And with nearly 88% of existing homeowners carrying mortgage rates below 6%, many are understandably reluctant to sell and give up those low rates, which continues to constrain housing inventory.
That makes it especially important for buyers to look for opportunities where they can find them. New-construction homes, for example, may offer a more affordable alternative because builders are highly motivated to sell and rely heavily on incentives to attract buyers. Nearly 1 in 5 newly built homes advertised some type of incentive in August, with mortgage-rate reductions by far the most common, offered on 13.8% of new-home listing nationwide.
Buyers can also improve their position by keeping their finances in good shape. Paying bills on time, reducing credit-card balances and protecting a strong credit score can help borrowers qualify for better loan terms when the right home comes along.
The September jobs report may give the Fed more reason to be patient, but buyers still need to navigate today’s higher-rate market carefully. We’re here to help you make sense of the options and what they could mean for your plans to buy, sell, or refinance.
|