Fire damage and connected homes
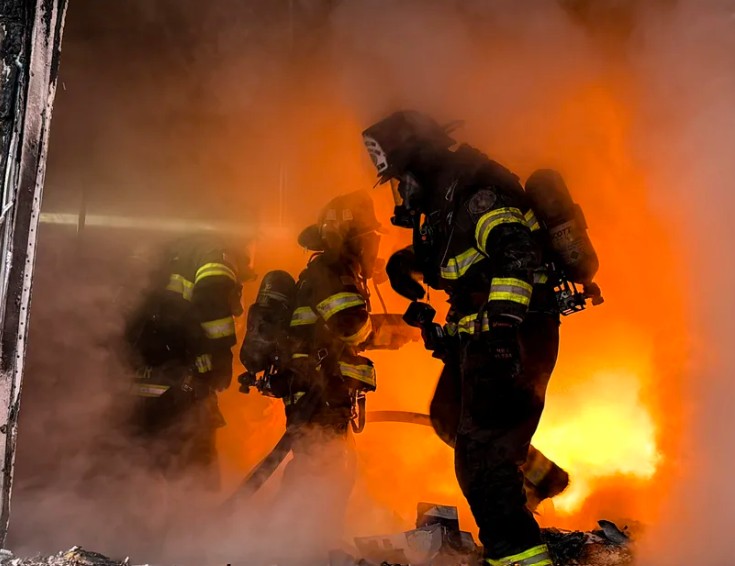
You live in a townhouse that is part of four connected units. The middle unit sparks a fire. What about the units on either side. Modern building codes would have required a firewall between each unit. This way the fire does not easily spread next door. However, there are other perils such as smoke, water, damage caused by the fire company. Are you covered for that as well.
Generally, standard homeowners insurance policies provide open-peril coverage for the dwelling, meaning losses are covered unless specifically excluded. Fire is a covered cause of loss under these policies, so long as it was not intentionally caused by or at the direction of the person who bought the insurance policy.
But, what about the housing units that may have been tangentially damaged by the fire on either side of the affected unit? In cases like this, the homeowners or renters policies for the adjoining units typically would respond if those homes sustained direct physical damage from the fire, smoke, heat or firefighting efforts. Which begs the question: What happens to the homeowners whose houses did not have the original damage?
If another party is found to be legally responsible for the fire, the insurance companies for the adjoining units may pursue subrogation—when, after paying a loss, an insurance company works to recover the amount of the loss from another party that is legally liable for it—against that party (and that party’s insurance company, if applicable).
If subrogation is successful, or if the claim is not charged as an at-fault loss, there is a greater likelihood that the neighboring homeowners’ insurance rates will not be affected—but this varies by insurance company.
|