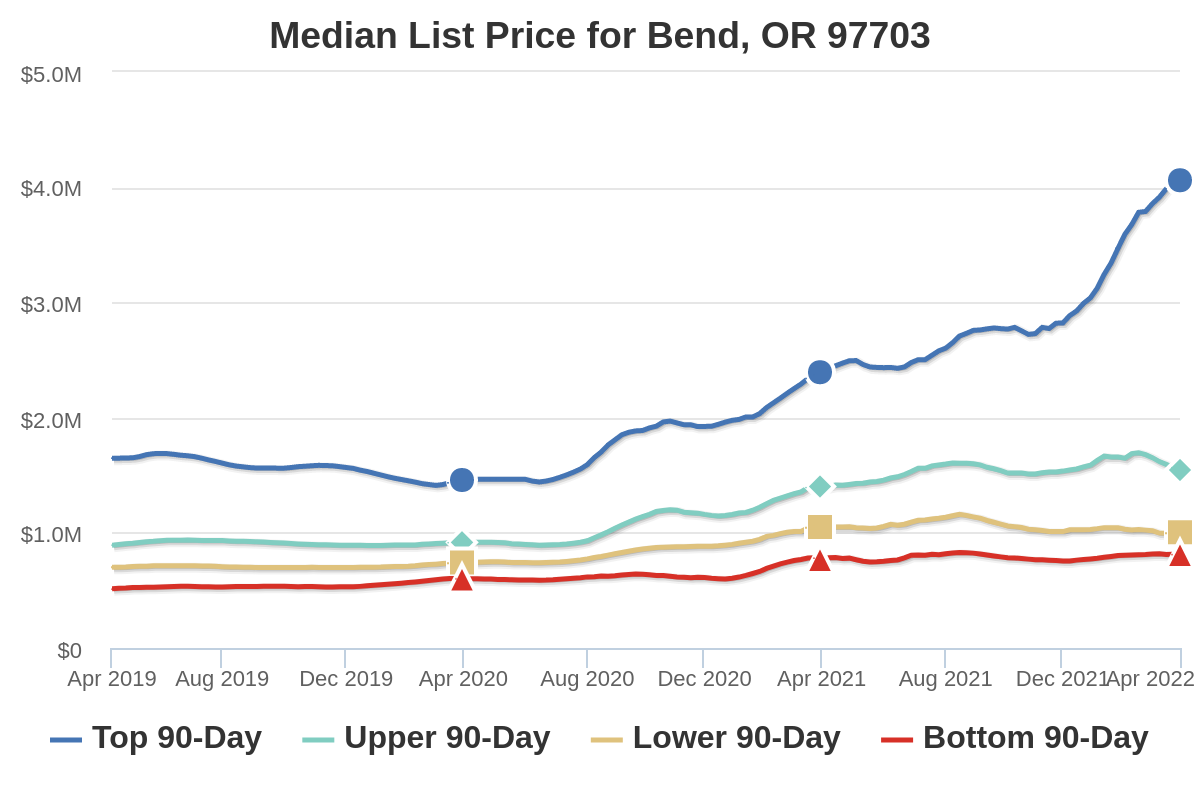
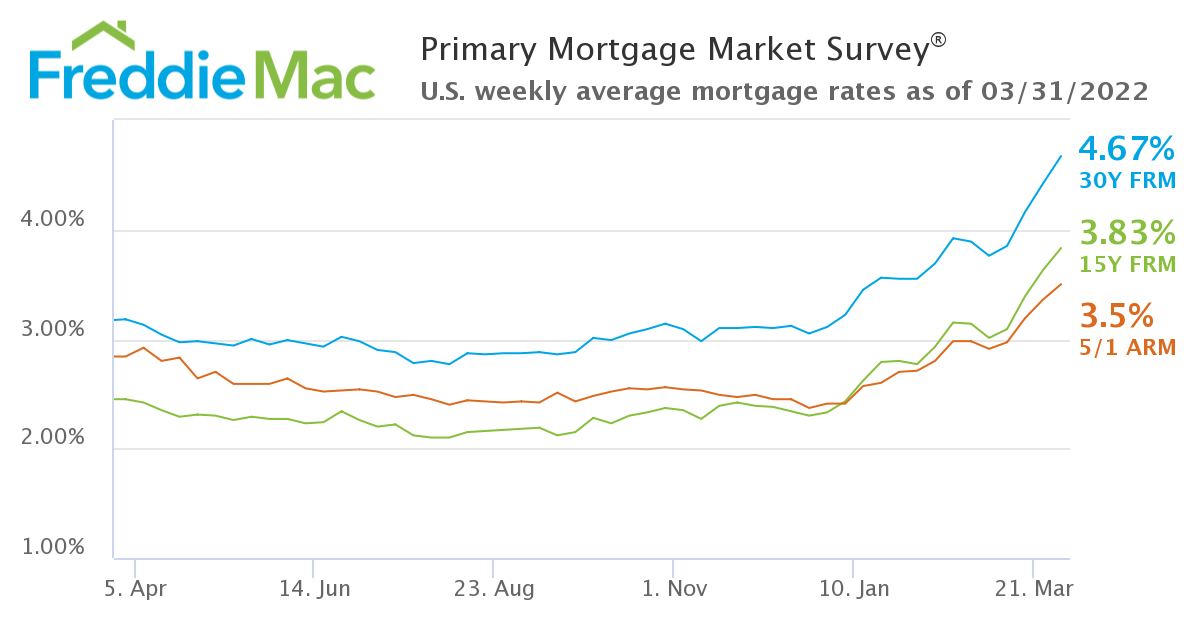
The two charts below show the median list price for Bend 97703 and the Freddie Mac 30 year fixed-rate mortgage interest rates. Conventional wisdom would indicate that housing prices soften while rates accelerate. While that may happen eventually, the charts show that buyer demand (home prices) has increased with rates. What gives? First, while rates are nearing five percent, they are still low from a historical perspective. Second, while the official CPI numbers show inflation tracking at 7.9% since February 2021, as consumers, we know firsthand that actual inflation is trending higher. Third, the real interest rate paid is the rate minus inflation, making the real rate paid still negative three percent using the most conservative numbers. Granted, most people don't purchase homes based on the actual interest rate paid, although many buyers in the higher price points consider these factors.
The flip side of the real interest rate conversation is the lost buying power of buyers at lower price points that rely on financing. This week's Deschutes County Single-family home market statistics illustrate this dynamic. As of this morning, there are 297 single-family homes listed at a median sale price of 850k. In addition, the active listings' median days on the market is 23, with the longer listing times restricted to high-end properties and entry-level homes at the lowest price points. Ninety-three homes were pending last week with four days listed and 689k median list price. Ninety-eight homes sold last week at a median of 720k and five days listed. With two-thirds of available inventory selling or pending in the previous week, there seems to be no backing off from buyers.
In late 1980, Fed Chairman Paul Volker raised interest rates to 20% to fight inflation, tracking at 12.5%. Volcker knew that rates higher than inflation were necessary to tamp down demand and rebalance the economy after years of misguided monetary policy. Compare that to "the most significant and least significant rate hike ever," bringing the Fed overnight rate to .32%, and it is clear Chairman Powell is fighting a forest fire with a garden hose. Ultimately, the mortgage interest rate is only one consideration in purchasing a home. While many experts believe rising rates will be short-lived, if the Fed backs away from rate hikes, it will be because of recession, not from successfully tamping down the inflation caused by recklessly injecting fiat currency into the economy. So buckle up, folks; the second half of 2022 will be a bumpy ride!