BLUME'S BULLS & BEARS
By: Jake Blumenthal
July 24th, 2026
#135
| |
Weekly Recap
This week, all of the major market indexes were relatively flat. The Nasdaq was the weakest performer, slipping about 0.5%, while the Russell 2000, Dow Jones, and S&P 500 all finished the week relatively unchanged. Energy was once again the top-performing sector as oil prices continued their gradual climb amid renewed tensions in the Middle East. On the other hand, Consumer Discretionary was the worst-performing sector, largely dragged down by Tesla, which makes up nearly 20% of the sector ETF.
Alright, there were a ton of earnings movers this week, so try to keep up.
Tesla was one of the biggest losers, dropping more than 13% after a weak earnings report, higher CAPEX guidance, and mixed commentary on the future. That said, I personally liked the company's production capacity numbers. GEV also fell nearly 10% this week, more thoughts on that below. Google dropped more than 6% after raising its CAPEX guidance yet again, as investors seemed to completely ignore the otherwise outstanding results in the earnings report. IBM also continued its decline after lowering its full-year revenue guidance.
On the upside, we saw very strong reports from defense companies (shocker), with RTX and Lockheed Martin jumping 8% and 10%, respectively. Their results helped lift the entire defense sector. United Rentals (a more detailed company review is coming next week) surged 12% after the industrial company delivered a triple beat, exceeding revenue and earnings expectations while also raising full-year guidance. Digital Realty jumped 15% to end the week after reporting a very strong quarter that showed its data center business is firing on all cylinders. Lastly, Thermo Fisher, the life sciences and biopharma company, also gained nearly 9% after delivering a triple beat of its own.
|
|
Hot Topic:
"Earnings Season Preview"
| |
Earnings season is always a very busy time for me and other analysts as we try to keep up with hundreds—sometimes thousands—of earnings reports, data points, and CEO commentary. But it's also one of the most fun and exciting times of the year. Just two weeks into earnings season, I'm already starting to notice a trend that I don't really have a word to describe: erratic, foolish, pessimistic, justified... I'm not quite sure.
To start, we're still seeing companies spend heavily on CAPEX, with the majority of that money flowing into hardware and infrastructure. Semiconductors, electrical equipment, and power generation are where the dollars continue to go. We've also seen that software isn't the primary beneficiary yet, as evidenced by IBM's preliminary report and its 20%+ sell-off, although ServiceNow did report a solid quarter. GEV also continued to show impressive growth, and I liked what I saw despite the stock selling off.
Now, the most interesting earnings report so far, and what I think could be a preview of what's to come, was Google. It was a phenomenal quarter. EPS came in more than 200% above estimates, Google Cloud revenue grew 82% year over year, and the company now has more than $514 billion in backlog. Management also said existing customers are consuming more than 50% above their original commitments, while new customer acquisitions have more than doubled year over year. Revenue growth is accelerating while margins continue to expand, which is exactly what investors should want to see.
Yet despite all of that, investors seem to be focused on one thing: Google announced it will spend even more than originally expected on CAPEX to invest in its future growth. Management raised its CAPEX guidance from $180–190 billion to more than $200 billion.
Guys, Google having a $200 billion CAPEX budget is larger than the entire market capitalization of all but roughly 85 companies in the world.
I believe we are witnessing a technological revolution. Think about it in sports terms. The Yankees and Dodgers continue to be among the best because they have the most money and consistently invest in their teams. In soccer, clubs like Real Madrid and Manchester City spend the most and, as a result, remain among the biggest and most successful clubs in the world. Do we really think these hyperscalers—the Magnificent Seven—spending a combined trillion-plus dollars on CAPEX won't continue to strengthen their competitive advantages and maintain dominant market share?
I think it is important to not be so short-sighted that we're only thinking six months ahead. Startups or companies investing a few million dollars in AI shouldn't come close to competing with companies investing hundreds of billions. To me, many of these post-earnings sell-offs may be creating buying opportunities for long-term investors.
| | |
I believe next week will be a big one as we'll hear from the Fed Chair and get a decision on whether interest rates will change. Rates currently stand between 3.5% and 3.75%, and market futures are pricing in a 64% chance that rates remain unchanged and a 36% chance of a rate hike. Personally, I think rates will stay the same, but I do expect the Fed Chair to strike a more aggressive and hawkish tone regarding inflation, again, which remains elevated at 3.5%.
Earnings to Watch:
- Monday: Nucor & Cadence Design Systems
- Tuesday: Visa, Coca-Cola, KLA, Boeing, Corning, UPS, Waste Management, Mondelez, Sherwin Williams, Hilton, Bloom Energy, Teradyne, Paypal, FirstEnergy, & More
- Wednesday: Microsoft, Meta, Lam Research, Procter & Gamble, Qualcomm, Starbucks, Vertiv, Fortinet, General Dynamics, ADP, Robinhood, Carvana, L3Harris, Chipotle, SoFi, Generac, & More
- Thursday: Apple, Amazon, Mastercard, Bristol-Meyers, Quanta Services, AEP, Coinbase, Live Nation, Yum! Brnads, Reddit, & More
- Friday (Pre Market): ExxonMobil, Abbvie, Chevron, Linde, Eaton, & Dominion Energy
The busiest week of earnings season is next week. Let me touch on a few names I'm excited to watch throughout the week. Tuesday: I expect strong quarters from the chip equipment and hardware names, particularly KLA and Corning (GLW). I'll also be watching Bloom Energy closely. The stock has gone from $120 to $350 and back to around $200 all in the same year. Despite the volatility, I expect a solid quarter, as the company has been powering many AI-related projects.
Wednesday will be the most packed day of the week. While I expect both Microsoft and Meta to report strong quarters, I also think they'll continue raising their CAPEX guidance, which could lead to a sell-off despite good results. For Microsoft, I'll be watching to see if Azure cloud growth remains around 40%. Like KLA and GLW, I also have high expectations for Vertiv. The other two names I'll be watching closely are Robinhood, which has had a strong rebound from its year-to-date lows, and Chipotle, which I still believe is trading too cheaply.
Thursday, I expect Apple to report largely in line with expectations, so I don't anticipate much movement in the stock. I expect a similar setup for Amazon as I do for Microsoft and Meta. Quanta Services will also be an interesting one to watch. I don't expect a GEV-like sell-off, but I would be a buyer on any meaningful dip. Reddit is another name I'll be watching closely.
Friday, the main name I'll be focused on is AbbVie. I expect another strong quarter and think it could send the stock to new highs. They've been on an absolute tear. I also expect very strong quarters from XOM and CVX, the oil giants!
| |
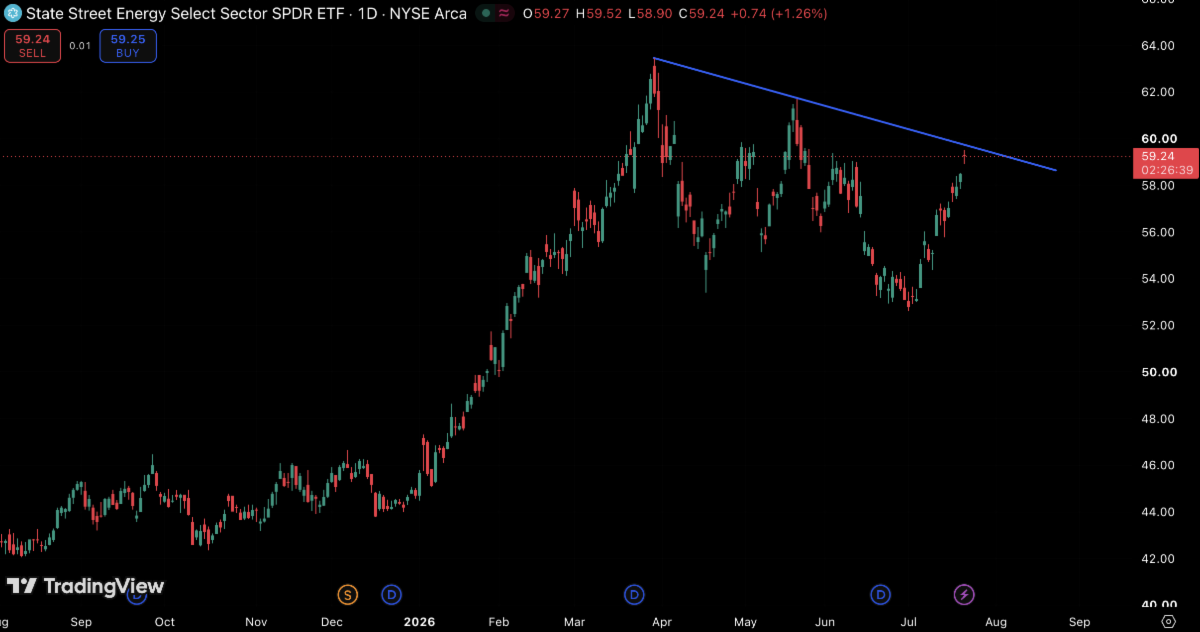
 | | SPDR Energy Select Sector ETF (XLE) - I was doing some reading and research this week and found that the large-cap energy sector is actually the cheapest group in the S&P 500 by a wide margin. The XLE trades at a forward P/E of around 13.4x, compared to the S&P 500 average of roughly 20x. Despite the XLE being up nearly 35% YTD and leading the market this year, I believe it still looks inexpensive. Yes, a lot of that has to do with oil prices spiking this year, which has boosted revenues, earnings, and future estimates. However, these companies are some of the most disciplined when it comes to managing volatile cash flows while still growing shareholder returns through dividends, buybacks, and stock price appreciation. The chart also suggests the fund and sector could be nearing another breakout above roughly $60 per share. I'll be watching this trend closely. This is a sector of the market that I really like heading into year-end because it feels a little more reliable than what we're currently seeing in the broader market, especially within the highly volatile technology sector. Plus, we get earnings from XOM, CVX, COP, and several other energy names next week, and I am very optimistic about the results.
GE Vernova (GEV) - It's been a while since I covered this name, and I've been waiting for a pullback. The stock dropped roughly 8% on Wednesday following a mixed earnings report. The company beat revenue expectations and raised its full-year revenue guidance but missed on earnings due to higher costs (some related to tariffs) and lower onshore equipment volume. That said, the company is still seeing strong growth in its power and electrification businesses, increasing both revenue and cash flow expectations. In Q2, equipment orders more than doubled, while service orders grew 15%. I always remind my readers that we really can't have a data center boom without GEV's gas turbines and electrical grid equipment. The company's backlog improved to $176 billion, with margins continuing to improve, and management said it remains on pace to reach a $200 billion backlog by 2027. Oppenheimer came out with a $1,338 price target, implying nearly 30% upside following the sell-off. This is a name I believe we need to be watching closely.
Oracle Corporation (ORCL) - Yes, this name again... three times in the last seven weeks, and for good reason. This is one of my most bullish names in the market right now. I love the opportunity, especially with the stock down nearly 50% over the last year. Stepping in here may seem like a ballsy move, but I think it's a smart one. As I've said before, I believe the stock has been overly beaten down because of its massive capital expenditure (CAPEX) spending and the large amount of debt the company has taken on. I'm okay with that because Oracle needs to invest aggressively to expand capacity and meet growing demand. Oracle reported $67 billion in revenue for FY2026 and expects $89 billion in FY2027. Even more impressive, the company has $455 billion in Remaining Performance Obligations (RPOs)—its backlog of future business—which is more than 6x its FY2026 revenue. Revenue growth is expected to accelerate, and at just 16x earnings (16x!!!), I think this stock is an absolute steal at current levels. The company even landed a $7 billion Department of Defense contract this week, yet the stock still sold off. To me, that tells you the market is still far too focused on Oracle's near-term CAPEX spending while overlooking the incredible amount of future business the company continues to win. Oracle still feels like it's in the market's doghouse, even as its long-term outlook continues to improve. Mizuho also said this week that Oracle has one of the most attractive risk-to-reward profiles in the market and reiterated its $320 price target. I couldn't agree more. I think the risk-to-reward setup here is extremely favorable.
| | * Disclaimer - It's important to highlight that, on occasion, I may have existing positions in the stocks I highlight in my newsletter. This disclosure aims to be transparent about potential conflicts of interest. Additionally, any stocks identified in this section are for informational purposes only and nothing in newsletter should be construed as a recommendation to buy or sell any security. Although I strive for unbiased analysis, my ownership of certain stocks may influence those that I highlight. Rest assured, my commitment to providing well-researched insights remains unchanged. | | |
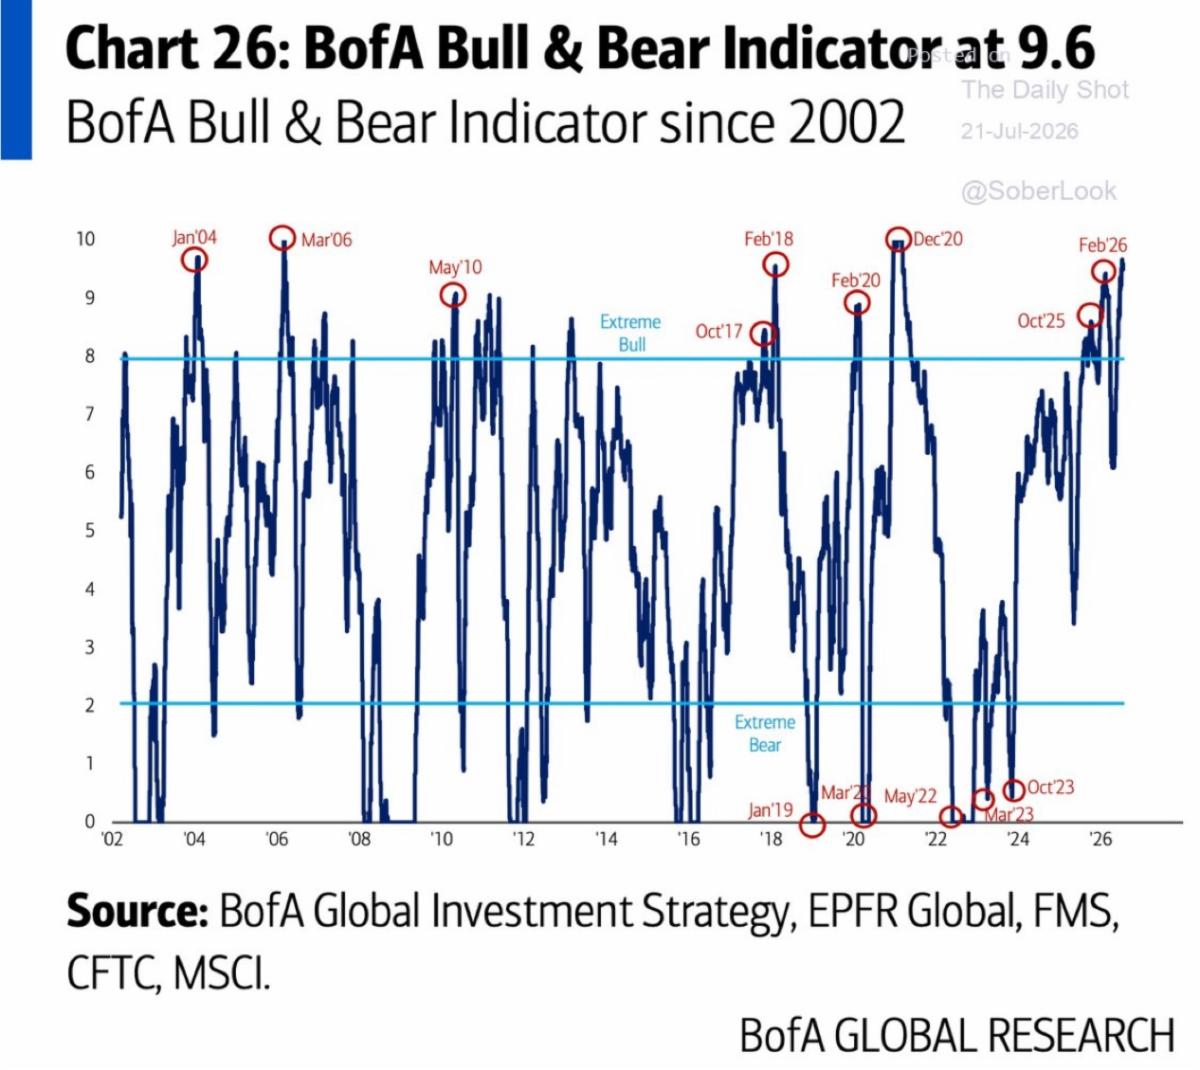
The chart below shows that market optimism is nearing extreme highs, as measured by Bank of America's Bull & Bear Indicator. In simple terms, it tracks investor fear and greed. Right now, it's signaling extreme greed or bullishness, and ironically, that's when we unfortunately need to start paying attention. History has shown that when we get that feeling that nothing can tear the market down, and that your local taxi driver could throw $1,000 into the market and make money like a blindfolded person throwing a dart at a dartboard, that is when I believe we need to be careful.
Now, why do I think we shouldn't feel this way right now? The S&P 500 is positive for the year, and the Nasdaq is up even more. That said, markets have been trading mostly sideways since the beginning of May with no meaningful pullback, all while inflation has spiked back to 4%, tensions with Iran remain elevated, concerns over hyperscalers overspending continue to grow, private equity has faced increasing scrutiny, the software sector has tanked, and yet the S&P 500 is still higher or holding its ground for the year.
I mean, shit, I typed all that out and got a little giddy. If the market is holding up through all of that, then when the dust settles on at least half of those concerns, why can't we see another 5–10% move higher in the overall market?
I do think an overall pullback would be healthy, but where does it come from? Maybe semiconductor stocks finally cool off, but software is already down. Materials haven't been great, gold has already pulled back, and while energy prices have moved higher, the sector still looks attractively valued. So where else could a pullback come from besides semis?
So despite what this chart is telling us, I remain bullish myself. I don't think it's greed—I think it's logical, at least in my opinion. It doesn't mean the market can't have a correction or pull back along the way, but based on how resilient it's been in the face of so many headwinds, it's hard for me not to remain optimistic into 2027 and beyond.
| | |
In Weekend Favorites, I share my thoughts on events I'm attending, the new series I'm planning to marathon, the movie I'm dying to see, restaurant craving to taste, trend that ticks me off, or the big game I won't miss.
Back home and feeling good! Although I think my dog was happier to be sleeping in my bed again than I was, lol. Anyways, first up is a great new show. It only has one season (has been renewed for a second), and I've already watched it from start to finish twice, lol. It's Kevin Hart's Funny AF on Netflix. If you don't like comedy or jokes that push the line a bit, then this probably isn't the show for you. But for me, I loved every second of it. It's a reality competition where Kevin Hart works with other comedians to find the next breakout comedy star. Contestants from all over the country compete for the chance to win their own comedy special. Along the way, they perform five-minute stand-up sets, interact with live crowds, and even participate in a roast of Marshawn Lynch, which was probably my favorite episode. If you're a fan of comedians like Kevin Hart, Andrew Schulz, or Shane Gillis, this is definitely a show worth checking out!
This weekend I am hoping to enjoy some down time, although somehow plans seem to be finding me. I have an event at the infamous Sands Club above the U of A stadium on Friday night, followed by a friend's birthday celebration on Saturday. So, I cant complain too much. With the World Cup over, I'll have to find something else to keep me busy. Next up on my watchlist is Will Ferrell's new Netflix series, The Hawk. A review will most likely be coming next week!
| | To learn more about Jake and what the Meridian Team can offer you, use the links below! | | | To read more of Jake's Analysis on Seeking Alpha where he shares his thoughts, opinions, stock ratings, and price targets on different stocks and ETFs, use the link below! | |
Sources:
- https://app.koyfin.com/home
- https://seekingalpha.com/
- https://www.blackrock.com/us/financial-professionals
- https://www.cnbc.com/
- https://x.com/home
- https://www.virtus.com/our-thinking/insights?
- https://www.franklintempleton.com/
- https://www.globalxetfs.com/insights
|
Disclaimer:
Advisory services offered through Meridian Wealth Management, LLC, a Registered Investment Advisor. Seek tax, legal, insurance, and investment advice from a licensed professional relative to your situation. The information and opinions voiced in this material are strictly for general information only and are not intended to provide any security recommendations, specific advice, or recommendations. Any views or opinions presented in this material are solely those of the Author and do not necessarily represent those of Meridian Wealth Management, LLC. Any mention of the use of a particular company, organization, or website is merely an opinion of the Author and is not a paid endorsement or advertisement. Securities and insurance products are not insured by the FDIC or any federal government agency, are not a deposit of or guaranteed by a bank or any bank affiliate and may lose value. No one connected with Meridian Wealth Management, LLC, can ensure the tax consequences of any transaction. All investing involves risk, including loss of principal. Past performance does not guarantee future results. No strategy ensures success or protects against loss. Further, readers should be aware that websites or sources listed in this work may have changed or disappeared between when this work was written and when it was read.
| | | | |