Forethought Quarterly
Wealth Aligned With Your Worth.
| |
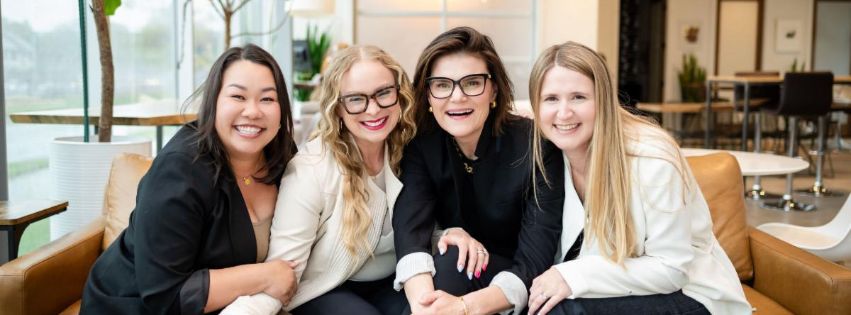
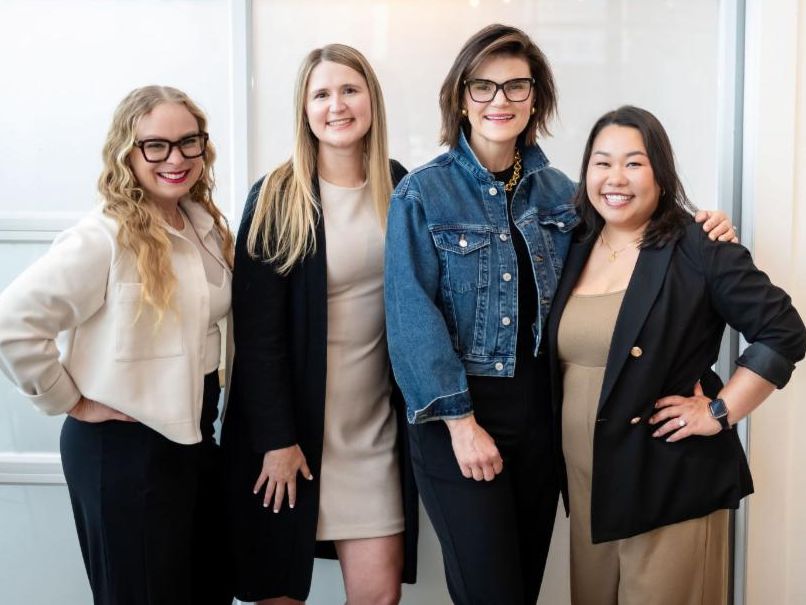
Forethought Team (L to R: Padao, Shannon, Kristi & Claire) | | | |
Greetings!
Every room I've walked into this week has had the same conversation running underneath it.
A leadership conference. A nonprofit event. Coffee with a friend. Somewhere between the name tags and the small talk, it comes up: the night sweats. The brain fog. The irritability that shows up out of nowhere. The emotions we feel on some days are completely out of our control.
It's top of mind in my house, too. I live with four women, two of us in perimenopause and two hitting puberty. Some days I'm convinced I'm on a reality show and Ashton Kutcher is about to jump out and yell, "You've been PUNKED!"
He hasn't yet. And I know I'm not the only one living this. Many of you are, too.
This conversation started taking shape for me after our team sponsored a Let's Talk Women event focused on menopause: the conversations, the advocacy, and the resources women need. As Michelle Obama said recently on her IMO podcast, in a conversation with Midi Health, "It's almost like women drop off the face of the healthcare map after we stop reproducing."
Then, at the end of September, a Pennsylvania lawmaker said the quiet part out loud. During a state House committee hearing on a bill requiring workplace accommodations for menopause- and pregnancy-related conditions, Rep. Scott Barger (R) argued the bill would make women "more costly to hire." Comparing a woman and a man in their mid-40s, he said employers would "find a reason not to hire the woman. They just will. I would!" The bill, which requires accommodations like longer and more frequent breaks and flexible schedules, advanced 14-12. It's part of an 11-bill package called "No Time for a Pause," which would also expand insurance coverage for menopause treatment.
I'm not sharing that to stir up fear. I'm sharing it because it names something many of you have felt at work and never said out loud.
What I want us all to recognize is that women’s health isn’t an issue just for women. It affects all of us. The systems around us affect all of us, and it’s important that we all take the time to understand that. Even if you don’t identify as a woman, don’t overlook this newsletter as a piece our team is writing only for women; this is for you, too.
Here's what I keep coming back to. Our health, our wealth, and this election are tied together in ways that go far beyond market swings and inflation. We'll keep talking about those, because they matter. Underneath them is something that rarely makes it into a financial plan: the out-of-pocket cost of trying to solve health issues that affect every woman, with very little research to give us the answers we need. And the ripple effects of those issues on our careers, our caregiving, and even whether we can qualify for long-term care insurance later.
Women live longer. We take care of everyone around us. And we usually take care of ourselves last.
So this quarter, I'm asking us to empower ourselves and the women around us to take action in two places. At the polls, where decisions about health care, workplace protections, and women's autonomy are being made. And in our financial plans, which should support all of the needs in our lives, not only the goals that come to mind first, like travel, career, education for you or your kids, a second home, or charitable giving. A good plan accounts for how your health and your wealth intersect.
Here's what's inside this issue:
- Midlife, menopause, and your money: caregiving, your health records, and long-term care
- Why we take care of ourselves last, and a simple check-in for balancing today and tomorrow
- Claire on the question we hear most: "Can I afford to stop, or pivot?"
- Where healthcare stands heading into midterms, & why market swings are weather, not the forecast
- A practical way to start, including open enrollment and your voting plan
| |
With care and steadiness,
Shannon
CEO | Founder | Wealth Advisor
Forethought Wealth
| | | |
Life Transitions & Your Financial Planning
In each edition of Forethought Quarterly, we highlight transitions that many of you are navigating. Transitions that influence not only your financial planning but also your emotional, practical, and relational life.
This quarter, we're talking about midlife, a season many women move through
while carrying everyone else at once.
Most of us plan for the costs we can see: groceries, tuition, travel, and a home.
Health care is harder to plan for because it’s less predictable, and it has been rising much faster than everything else. Here’s what the research shows:
-
Premiums: Since 1999, health insurance premiums have risen more than five times as fast as overall inflation. Workers’ share of family premiums grew 308%, while wages grew 119%.
-
Out-of-pocket costs: Since the pandemic, what the average person pays out of pocket has risen by about a third, from $1,239 to $1,652 a year.
-
Worry: Six in ten voters told KFF, an independent, nonpartisan health policy research organization, that they’re worried about affording health care for their families. That ties health care with gas prices as Americans’ top financial worry.
| | |
Caregiving
Many of us are caring for aging parents, kids, partners, or all three at once. Of the 455,000 women who voluntarily left the workforce in 2025, 42% said the reason was the cost of caregiving and caregiving responsibilities.
Child care alone now averages $13,128 a year nationally, about 10% of median household income for married couples and 35% for single parents.
| |  | |
Living longer
Women tend to live longer than men, which is a gift and also a planning question. More years means savings need to stretch further, and the possibility of an extended care event carries more weight.
Medicare generally doesn't cover long-term custodial care. Medicaid does, and it's facing federal cuts that analysts expect to fall hardest on nursing homes and long-term care facilities.
| | | |
Menopause
It's rarely talked about as a financial topic, and it should be. Symptoms can affect sleep, focus, mood, and energy during what are often your peak earning years. Some women cut back their hours, turn down promotions, or step away from work they love.
Many spend years and significant out-of-pocket dollars searching for answers, cycling through appointments, tests, and treatments that insurance doesn't fully cover.
| | | |
The connection almost no one talks about
Some women with significant menopause symptoms use the Family and Medical Leave Act (FMLA) to protect their jobs. To qualify, they need documentation from their doctor certifying a serious health condition. When symptoms affect mental health, that documentation often has to describe them at their most severe.
That protection can be exactly what someone needs. But the records stay in your medical history. Years later, when you apply for long-term care insurance, insurers review that history, and it can affect whether you qualify or what you pay.
Never skip care, or the documentation you need, to protect a future insurance application. Your health comes first. What helps is telling us what’s happening, so we can plan around your real life. That might mean exploring coverage earlier, or building other ways to fund care.
Many people don’t think to tell their financial planner about their health. With our team, you can. Every one of us has served, or is serving, as a caregiver.
| |
The Behavioral Financial Buzz
Behavioral finance reminds us that money decisions aren’t just logical. They are emotional, learned, and shaped by the world around us. If we don’t define what “enough” means for us, it’s easy to fall into autopilot: chasing more, comparing, reacting to fear-based headlines, or spending to soothe stress.
Why We Take Care of Ourselves Last, and How to Bring Yourself Back In
Your brain isn’t built to weigh your future self as heavily as the person standing in front of you. Researchers call this present bias. For many women, something else is layered on top of it: a lifetime of being the one who shows up for everyone. Here are four reasons we tend to put ourselves at the end of the line. See if any sound familiar.
-
The Expectation. Everyone expects you to be the one who’s there. You’re the one who handles the doctor’s appointments, organizes the holidays, and answers the 10 p.m. call. Over time, being needed becomes part of who you are, and saying no feels like letting people down.
-
The Responsible One. Maybe you’re the planner in the family. You saved. You understand money. So when a parent needs help, a sibling falls short, or an adult child needs a hand, it lands on you. Being prepared is a strength, but it can also make you everyone’s safety plan except your own.
-
The Cultural Script. Many of us grew up watching the women in our families give endlessly and ask for nothing. Some cultures and communities expect daughters, wives, and mothers to carry the care. Those messages run deep, even when we don’t fully agree with them.
-
The Caregiver’s Default. When money gets tight, the first thing to go is often your own retirement contribution. It feels flexible, because no one is counting on it today. But future you is counting on it, and there’s no financial aid program for retirement.
How it shows up in your money
-
Present bias: A dollar spent today feels real. A dollar saved for age 80 feels abstract. Both are real. One just has a better publicist.
-
The “Someday” story: “I’ll catch up once the kids are through school.” “I’ll see a doctor once work slows down.” Sometimes someday comes. Often the next season arrives first.
The Today and Tomorrow Check-In
Before your next big financial decision, take three minutes:
- Who is this decision for, and does my future self have a voice in it?
- Is this coming from my values, or from guilt, expectation, or a headline?
- What’s one small thing I can do for future me this month, without taking anything away from the people I love?
The goal isn’t to stop caring for others. It’s to make sure you’re on the list too.
| |
Learning Moment with Claire
"Can I Afford to Stop, or Pivot?"
The question I hear most from our clients in their 40s and 50s isn't about Medicare. It's quieter, and often harder to say out loud: Can I afford to stop? Or to change direction?
These are clients who have worked incredibly hard. They set big goals, reach them, and are still on the battlefield every day, often feeling more alone the higher they climb. And many of
them feel a pull toward something different. A bigger impact. A dream they've carried for years.
Or maybe a part-time job at the local bookstore. Then the worry kicks in. Can I actually afford this? And what about health care?
That second question carries extra weight for women, who are usually the ones scheduling the appointments, for ourselves and for the kids, partners, or parents we care for. Health care isn't one line item. It's the whole family's well-being running through our calendars.
When a client brings me this question, here's what we look at together:
-
Your runway. How long your savings can support a pause or a lower-paying chapter, and what that means for your long-term plan.
-
Your health care bridge. If you leave employer coverage before 65, the ACA marketplace is often the bridge to Medicare. Enhanced federal subsidies expired at the end of 2025, and many enrollees are paying much more this year. Because marketplace subsidies are tied to income, how and when you draw from savings can change what you pay for coverage.
-
What you'd leave behind. An employer retirement match, disability and life insurance, and possibly an HSA. Some of these are worth replacing or maxing out before you go.
-
What a pivot can add. Even modest income from part-time or purpose-driven work can reduce how much you draw from savings and extend your runway significantly.
Often, the answer isn't a flat yes or no. It's "yes, if" or "not yet, and here's when." Either way, you get to decide with real numbers instead of fear.
If a dream is tugging at your heart, bring it to your next meeting. We'll model it with you.
| |
The Financial Pulse: What's Trending?
In The Financial Pulse, we’ll unpack key trends and economic shifts impacting your financial strategy. Our goal is to offer clear, timely insights that help you confidently navigate today’s market movements while staying aligned with your long-term goals.
Health Care Is a Bipartisan Issue. Let’s Act Like It.
With midterm elections on November 3, health care costs sit near the top of voters’ concerns across the country. Here’s where things stand, and what you can do about it.
What’s changed this year
Several federal changes are reshaping what health care costs and who can get it:
-
ACA marketplace premiums rose sharply. Enhanced federal subsidies that made marketplace plans more affordable expired at the end of 2025. This matters most for people who retire before 65, are self-employed, or step away from work to care for family.
-
Medicaid is shrinking. The 2025 federal tax and spending law includes about $1 trillion in Medicaid cuts. One analysis projects roughly 15 million people will lose coverage by 2034, plus another 4.2 million who will lose marketplace coverage.
-
Long-term care is under pressure. Medicaid is a major payer for nursing home care, and analysts expect these cuts to fall hardest on nursing homes and long-term care facilities.
-
New work requirements. Some Medicaid enrollees must now work at least 80 hours a month. Family caregivers are broadly exempt, but the exemption isn’t automatic.
| |
We agree more than we think
Here’s what rarely makes campaign ads: Americans broadly agree the system needs fixing. In KFF’s latest poll, about nine in ten Democrats and three-quarters of Republicans said health care needs major changes or a complete overhaul. Only 15% said it works well enough as is.
Where people differ is in solutions. Republicans have focused on market-based approaches, like expanding Health Savings Accounts and tax credits. Democrats have focused on restoring the expanded ACA subsidies and lowering out-of-pocket costs. That’s exactly why our voices matter. Leaders need to hear from us about what we actually need.
| |
And the markets? Plan for them.
Don’t live in them.
Markets go up and down. That’s a normal part of every economic and market cycle, under every party. Election years can feel especially noisy, but over the long term, returns haven’t depended on who wins.
We build your plan for that reality, with diversification and cash reserves, so you don’t have to react to every headline. But planning isn’t about bracing for doomsday. It’s about freedom.
Think about the choices you want today: to travel, to pivot, to help your family, to take a breath. You’ll want those same choices in the future, at a time when you may not want to work, or may not be able to. Planning for tomorrow makes sure future you has them.
| | |
How to hold leaders accountable, locally and nationally
Voting matters.
So does what happens before and after it.
-
Know what you want. Write down your top two or three priorities: maybe out-of-pocket costs, support for family caregivers, or menopause care coverage.
-
Do the research. Look up where candidates stand, from your state legislature to Congress. Many health care decisions, like workplace accommodations and Medicaid rules, happen at the state level.
-
Pick up the phone. Call or email your representatives. A short, specific message about your own experience carries weight.
-
Ask direct questions. At town halls and forums, ask: “What will you do about out-of-pocket health costs?” “How will you support family caregivers?”
-
Vote early. Postal delays have increased, and late-arriving mail ballots were rejected at twice the usual rate in this year’s primaries. Check your state’s deadlines.
| |
A Practical Way to Start: Your Q4 Check-In
-
This week: Make your voting plan and write down your top health care priorities.
-
This month: During open enrollment, review your HSA, FSA, and disability coverage. If you’re 50 or older, you can add up to $8,000 more to a 401(k) in 2026 ($11,250 at ages 60 to 63).
-
At your next meeting: Share any health changes, even small ones. They matter more to your plan than you might think.
Markets will rise and fall. Elections will come and go. Prices will do what prices do.
What stays constant is your ability to make thoughtful choices for yourself and the people you love. Your health is part of your wealth, not separate from it.
You’re allowed to live fully today. You’re allowed to protect tomorrow. You’re allowed to ask for help holding both.
| | | | |
Ready to discuss your personal situation?
Together, we'll navigate life's transitions with clarity, confidence, and an unwavering wealth mindset, seeking to ensure your financial plan supports not just your goals but your deepest values.
| | | |
There is no guarantee that a diversified portfolio will enhance overall returns or outperform a non-diversified portfolio.
Diversification does not protect against market risk. Rebalancing a portfolio may cause investors to incur tax liabilities and/or transaction costs and does not assure a profit or protect against a loss.
| | |
Content in this material is for general information only and not intended to provide specific advice or recommendations for any individual.
All investing involves risk including loss of principal. No strategy assures success or protects against loss.
| Securities and Advisory Services offered through LPL Financial, a registered investment advisor. Member FINRA/SIPC. Financial planning offered through Forethought Planning, a registered investment advisor and separate entity from LPL Financial. | | | | |