Metal Market Update - January 2023
|
|
|
Greetings!
Happy New Year!
We trust this email finds you well and we hope this information adds value to your busy day. We appreciate the opportunity to connect with you and your Team in all facets of the business cycle so please don't hesitate to call us at 704.568.3001 or email us at sales@wardve.com if we can be of any assistance.
|
|
Industrial Manufacturing News
|
|
The ISM Manufacturing Index (PMI) fell for the second straight month to 48.4 in December, following a score of 49 in November. The reading shows further contraction in factory activity, being the biggest decline since the heat of COVID in May 2020. Order backlogs, prices, and deliveries are all showing signs of softening. Demand is also weakening, helping to ease supply chain bottlenecks and moderate inflation.
Consumer Confidence increased to 108.3 in December following back-to-back monthly declines, now standing at the highest we have seen since April 2022. This could be partly due to the cooling of inflation expectations, decreasing gas prices, and holiday vacation plans. Although, the purchasing of large ticket items such as homes and major appliances are still on the decline.
WTI Oil slowly fell through November and into the beginning of December. Oil entered December at $81.14 per barrel, diving to $71.21 per barrel by the 9th then steadily climbing back to $80.26 per barrel by the end of the month. COVID lockdowns in China appear to be lessening, which could be the cause for the climb in oil prices as we enter the New Year.
The online US Oil Rig Count is at 772 which is down 12 compared to last month's report and up 184 from January 7 of 2022 (a high of 1609 in October of 2014 before oil pricing dropped below $20 per barrel at the end of that year). This key and leading indicator shows the current demand for products used in drilling, completing, producing, and processing of hydrocarbons which all of us use every day as fuel sources and finished products.
|
|
News & Insights on Materials |
|
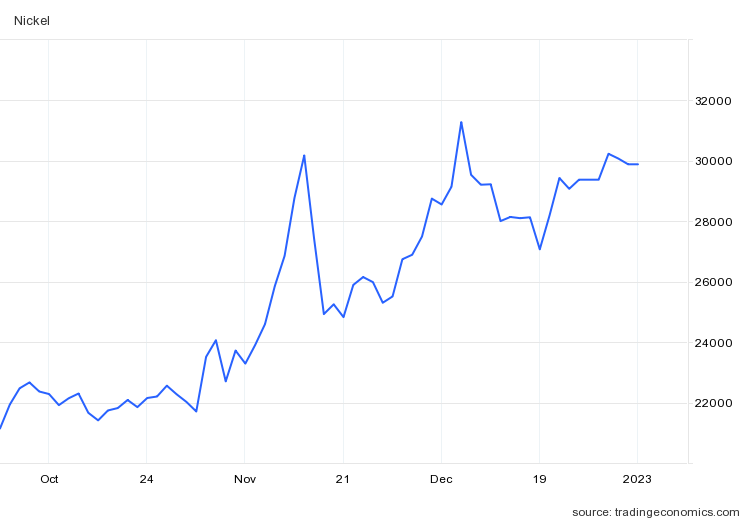
Nickel bounced around in December, beginning at $12.47/lb., then racing to $14.19/lb. by the 7th, prices we have not seen since May 2022. By mid-December prices had cooled to $12.28/lb. but then began to rise, closing at $13.56/lb. Prospects of China beginning to reopen due to new COVID guidelines brought an increased demand for nickel. Nickel will remain in high demand as the use of it in EV batteries only increases.
Domestic steel plate mills have had an exciting month. Nucor Corporation announced earlier this week that their new Brandenburg, Kentucky plate mill rolled its first steel plate on Friday, December 30th. Nucor states the mill will have the ability to produce 1.2 million tons annually. In late December, the United Steelworkers signed a four-year labor contract with United States Steel Corporation. This contract will continue through September 1st, 2026.
Commodity stainless and Duplex plate deliveries remain in the 7 to 12 week range, while Nickel alloy plates range from 12 to 26 weeks. Carbon Steel plate mill deliveries reside in the 6 to 10 week delivery range.
Welded tubing – Smaller quantity deliveries remain in the 10 to 16 week range, with larger quantity orders still in the window of 18 to 25 weeks. Carbon steel tubing deliveries have lead times ranging anywhere from 8 to 14 weeks when strip is available. Welded nickel alloy tubing ranges from 18 to 24 weeks, with some cases of 30 week deliveries.
Seamless tubing - Current schedules reflect 10 to 20 weeks or more for carbon steel (24 to 26 weeks for Western European carbon seamless) and 8 to 30 weeks for stainless. Seamless nickel tubing is being offered at the 8 to 12 week delivery window so long as hollows are in stock. If hollows are not readily available, anticipate deliveries of seamless nickel tubing in the 20 to 32 week timeframe.
Please don't hesitate to reach out if you have any questions about the current state of our industry's material supply chain.
|
|
90 Day Nickel Price Trend |
|
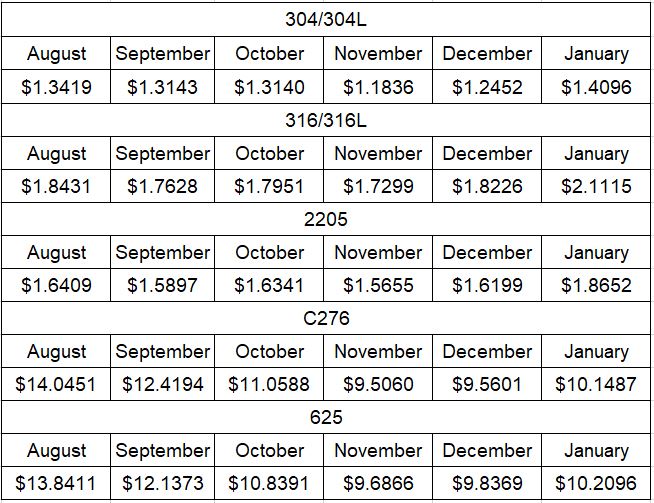
Material Surcharge History |
|
Historical Nickel Price Data |
|
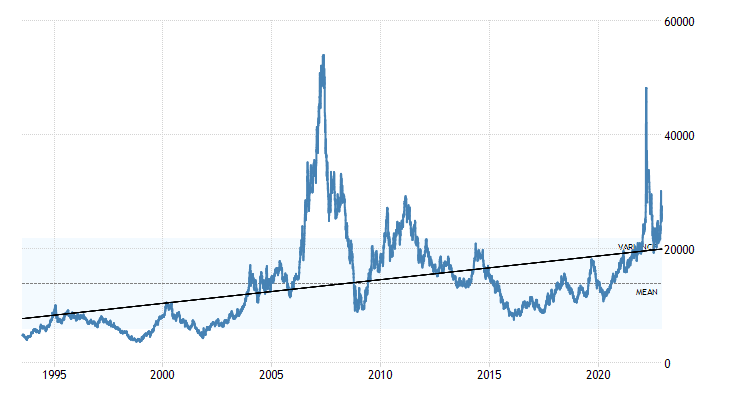
Nickel Prices have had an interesting ride over the past two decades with a low of $2.20/lb. in October of 2001 (following September 11 events) and a high of $23.72/lb. in May of 2007. Surcharges trail Nickel prices by approximately two months, so they would have been at their lowest in December of 2001 (304 was $0.0182/lb.) with the peak in July of 2007 (304 was $2.2839/lb.).
The chart below illustrates Nickel price by way of U.S. Dollars per Metric ton.
|
|
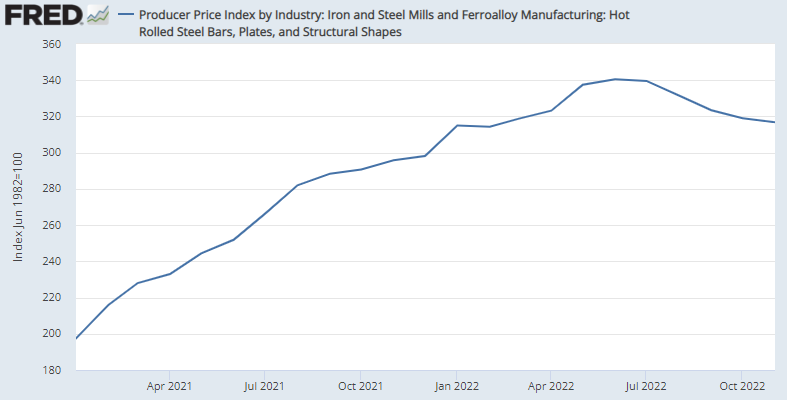
Price Index: Hot Rolled Bars, Plate, and Structural Shapes |
|
ASME Code, TEMA and API Facts - Did you know? |
|
Seal vs. Strength Welds
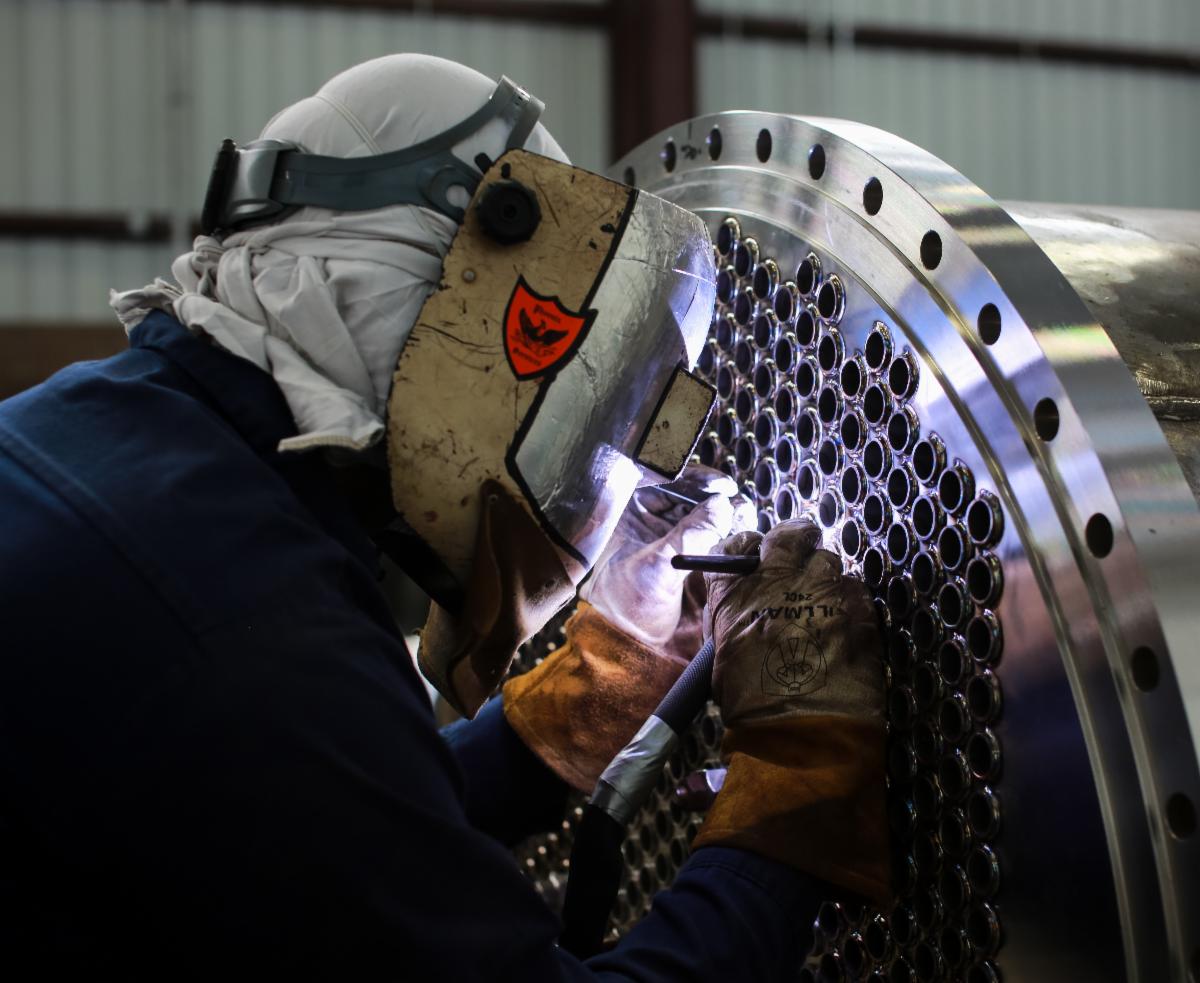
Heat exchanger tube end welds can be specified as strength welds or seal welds. What is the difference? The tube to tubesheet joint is a critical component of the exchanger and must be designed for several conditions. First, the joint needs to seal against pressure acting from both the shell and tube sides. Second, the joint needs to be able to handle the axial forces of the tubes as they grow or contract due to thermal differences in the exchanger. A strength weld is designed to be large enough to handle all the forces and pressures on the joint. In fact, normally a strength weld is designed to be as strong as the tube itself. A seal weld, on the other hand, is only a minimal size weld acting as a secondary seal. The primary joint strength and sealing is obtained from expanding the tubes into the tubesheet in those cases. Tube expansion is required for seal welded joints, but optional for strength welds.
|
|
TEMA Update - The 10th edition of the TEMA Standards are available for purchase as of April 15th, 2019. Please visit www.tema.org to get your copy on order today!
|
|
Benefits of a Specialty Turnkey Service Provider
|
|
"The Perfect Order"
This bit of wisdom came from a long-time friend and co-worker who received this sage advice from a leader in the Corps of Cadets at Virginia Polytechnic Institute:
"If you give an order that can be understood, you have failed. You have only succeeded if you give an order that cannot be MISunderstood."
|
|
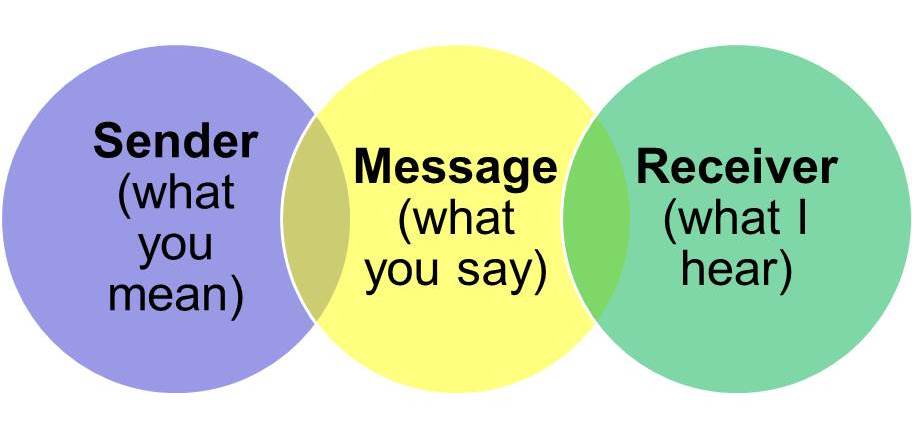
Entire books can be written on this topic and, if you consider its military roots, it's easy to understand why. Think for a minute about how critical communication is in wartime. People live and die according to orders. And we are not talking about only the giving of the orders - you must also take into account how the order is received. Both have to be lock-in-step or things can get sideways in a hurry.
As civilians, we shouldn't take orders (directions) any less seriously. We each go through our day, communicating with our clients, co-workers, and partners. How many of us spend enough time communicating with the goal to ensure clear and effective information that cannot be misinterpreted?
Often, this means more time will need to be taken in the creation of the order. In modern times, we have developed different technologies with an emphasis on short and quick communication. Text messages, emails, etc. have led us down a path where we water things down in the interest of 140 characters. While simple writing is almost always best in the day-to-day, it can get too simple. Put yourself in the recipient's shoes. Try to empathize and clear your mind of what you know about the directive and give an honest attempt to understand how your information will be digested before you craft that message. Then, using plain and simple language, convey the information in a way that leaves little to the imagination. Your recipient is likely not as immersed in the situation as are you and therefore may need a few more dots to connect to arrive at a full understanding.
Forget what you know in order to help others understand what you mean.
This is the first in a three-part series. Next month, we will talk about “Three-Way Communication” and in March we will touch on why it’s important to “Read the Instructions”.
|
|
|
|
|
|
|