September Supplement Issue

Popping the Gridlock Cork

Expect an instant mortgage interest rate cut in reaction to the Federal Reserve?


Realtors are getting back their skip in step. Inventory has continued to increase with this Federal Reserve cut expected to be a pop in the gridlock cork to help get the wheels in motion.


The Federal Reserve leaned in and went with a full half, but what does that mean to you? Many lenders started hedging bets on not just this cut, but also future anticipated cuts with a lowering of rates ahead of the Federal Reserve meet.


For this reason combined with lenders generally holding in the sidelines awaiting more and varied upcoming economic indicators, immediate further mortgage rate reduction in reaction to this cut is likely not in the cards. It is, however, a step in the right direction from an interest rate perspective.


While dependent on upcoming economic indicators, additional interest rate reductions have been shared as anticipated by multiple lenders going forward. There is underlying speculation whether this will hold the market in sellers market conditions or actually move the pendulum toward a neutral, if not buyers market. This was further addressed in the September issue of The Brick: "Do you feel the undercurrent?"

Timely Tips in this Supplemental Issue:


  • Closing before December holidays (and potentially Thanksgiving)
  • Why "First Time Buyer" programs are not exclusive to first time buyers
  • Credit impact on the monthly nut
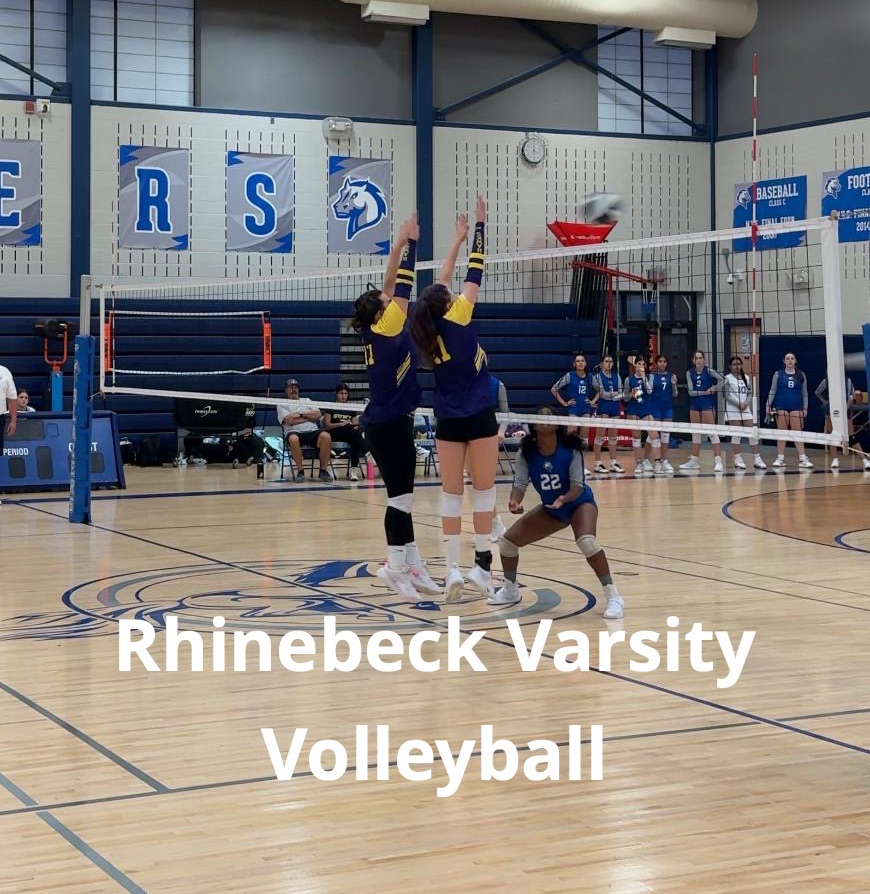
  • Rhinebeck vs. Pine Plains varsity volleyball. Send up positive vibes!


Here we go...

Close before December holidays...


Inventory of homes on the market continues to increase! Let's get even more options on the market! Homes priced well and effectively marketed are moving swiftly in current market conditions.


To share an example time frame from listed to sold assuming the following: the home is solidly priced and effectively marketed, buyers, sellers, attorneys, lenders and title are aligned with intention for a swift close, a nudge realtor is on board to keep check, no title issues and non-luxury property.


With those boxes checked, the following seems a reasonable expectation based on my clients sales histories over the past four years in this market condition:


Timeline to Close


Enter the market October 1st

Fully executed contract within 30 days (October 31)

Closing between December 2-13.


This is assuming a mortgaged buyer. Cash buyers can generally shave up to approx. two weeks off the schedule as while lender processing would not be factored, title processing still should be.


I have had mortgaged buyers close in a cash window and also fully executed contracts within two weeks from listing. The dates noted are a sample overall reasonable window in current market conditions for a listing going on the market by early October. With hustle from all parties and professionals involved in the transaction, closing by Thanksgiving could be feasible, particularly if in fully executed contract by mid October.


The market is expected to slow down on approach to Election Day as is historically the case in election year fall markets. Therefore, it is most ideal to secure a buyer as early in October as possible with buyer pool currently existing in the market. Unless unforeseen events arise, I do expect Q1 2025 to continue in sellers market conditions, particularly if interest rates continue to go down.


However, sellers that "test the market" with overly aggressive pricing in Q1 could find themselves sitting on the market into Q2/Spring Market 2025 as more sellers/competition enter the market. Spring Market 2025 has a fair enough share of wildcards to introduce question on market conditions. If I were to place bets on sellers market conditions, I would place them on the now and Q1 2025.


Sounds good, but you need a place to go to? Throughout all this crazy, I have yet to have a client go homeless and don't plan on starting now. Let's talk it through to solid plan. Reach out by phone or text.

The Name can be Misleading:

"First Time Buyer" Programs


"First Time Buyer" can be a misleading program name as certain programs available through Fannie Mae and Freddie Mac require a home to have not been purchased within the past three years to be considered a "first time buyer". Other programs are primarily income based for qualification without three year requirement at all. One of my preferred lenders, Jim Gallagher with Fairway Mortgage, shared the following insight.


The area median income ("AMI") is a key qualification definer within varied first time buyer programs. In the traditional Fannie Mae and Freddie Mac programs, the current AMI income limitation in Dutchess County, for example, at 100% is $114,800. Ulster County is higher at $117,200. Considering the jump in median pricing in Westchester County, the maximum income to qualify is surprisingly low with current 100% income at $119,300 to qualify. However, this program does not require filing of full household income, per Mr. Gallagher. While monthly debt is also factored, currently a credit score of 680 has the capability of qualifying for a 5.75% 30 year conventional with this program with 3% down. To see the AMI limit amount by address click here.


For those with income at 80% of the AMI, another program exists called "Home Ready" and

"Home Ready Possible" with Fannie Mae and Freddie Mac respectively. This program is primarily income and credit dependent without mandate for 3+ years since last purchase.


Just one dollar over the AMI income limit can move the credit score requirement from 680 to a 780 minimum score in order to qualify. That's a real hit in credit score requirements over a dollar! Income limits are very real with both programs. There are other programs that do require full household income, but these two currently do not. Speaking directly with lenders is best when considering a mortgage. I have multiple high caliber lenders I work with. For more information, reach out to me and I would be happy to provide contact information.

Credit Score Impact on Mortgage Rates


The world of mortgage is highly dependent on credit scores to determine interest rates. Another preferred lender I spoke with, Stephen Betterton with PrimeLending, shared the dollar impact credit can have on the monthly nut.


The below examples are for a standard 30 year conventional mortgage. Interest rates fluctuate daily. There are also additional variables in the qualification process that can impact rates and qualification. These examples were provided to me within the past week from Stephen. PMI noted if buyer is not putting a minimum of 20% down. The below is principal only and does not include taxes or insurance other than PMI as noted.


Loan Amount $300,000


780+ credit score, interest rate 5.875%. Mortgage payment $1775. PMI $37.50 per month. Total payment: $1812.50 per month.


620 credit score. Interest rate 7.49%. PMI $230 per month. Total payment $2326 per month.


Loan Amount $500,000


780+ credit score, interest rate 5.875%. Mortgage payment $2985. PMI $62.50. Total payment per month: $3047.50.


620 credit score, interest rate 7.49%. Mortgage payment $3494. PMI $362. Total payment $3856 per month.


Loan Amount $700,000


780+ credit score, interest rate 5.875%. Mortgage payment $4141. PMI $87.00. Total payment: $4228 per month.


620 credit score, interest rate 7.49%. Mortgage payment $4890. PMI $507.00. Totally payment $5397 per month.


I hosted an interview with Vincent Aurigemma, now with Valley Bank (previously Rhinebeck Bank) and Jackie Fellin with TEG Federal Credit Union that is a few years dated. There are certain references specific to getting a mortgage during Covid as it was taped during the frenzy period, but the underlying content is still relevant and informative. Click here for this discussion on mortgage processing and tips.


Getting Ready to Apply


For buyers planning on a Spring Market 2025 purchase, the time is ripe to prepare for the mortgage application process. If you haven't checked your credit score within the past year, myannualcreditreport.com offers a yearly free credit report to each of the three credit reporting agencies. Whether or not applying for a mortgage, it is a general good rule of thumb to check credit reports on a yearly basis as they directly feed the FICO score, which is highly relevant to all loan types, interest rates attached to credit cards, etc.


It is important to view a copy of the report from each agency as information on them can differ between the three (TransUnion, Equifax and Experian.). It can take time to have updates process with credit reporting agencies. That process should begin now with goal to be buttoned up by early Q1 2025 as options could very well come on the market with desire for an "early bird gets the worm" start ahead of the more crowded Spring Market.


Note the FICO score online will likely differ to a certain level from the banks FICO score as lenders employ a specific algorithm for banking, but the online version should give you a good perspective on what to expect with the bank. Many banks offer FICO score services their customers. Myfico.com is another source to gain FICO as well as through myannualcreditreport.com to name a few.


It's can be highly productive to speak with lenders at least 3-6 months ahead of applying to discuss programs and the overall mortgage process, documentation that will be needed, etc.


Questions or lender recommendations, always feel free to call or email.

Do you feel the undercurrent?


Interested in a projection for the road ahead into 2025? Latest in Hudson Valley events and workshops? Questions to consider when hiring a realtor? The latest in buyer/seller professional fees and agreements? If you missed it, check out the September issue of The Brick: Do you Feel the Undercurrent?

Client Testimonial


"I worked with several realtors before partnering with Sandi. She is an

exceptional realtor." P. Chang

I'm going to be one of "those" moms, but I can barely contain my excitement and pride for the Rhinebeck varsity volleyball team. My daughter, Alana, along with her teammates have dedicated a great deal of focus and training that for most began with the JV team last year.


The season just started with games neck to neck nail biters so far. Their win is coming with a cheer leading section of friends, family and faculty at the ready to go ballistic when it does! So exciting to watch!


Go Hawks!


I had a really interesting interview posting in the next day or two with two heads of international real estate with Hamptons International based in the UK. We covered varied aspects of the real estate market throughout Europe during this discussion. Hot markets, buyer/seller representation, AirBnB and other aspects of the European market were addressed.


I will include in the next issue of The Brick, but if you would like to see when it posts, follow on my social media channels. My channel on YouTube and Instagram are great starting grounds for my content. Each channel has unique aspects.


It's a wrap on the special edition! Enjoy the bounty of beauty that is the Hudson Valley. Fall Foliage here we come!


If you know someone interested in buying or selling, pass The Brick along!


Best,

Sandi


JOIN THE BRICK


Pass The Brick on to those interested in the market! Was it passed on to you? Join The Brick community below to receive upcoming issues!


Subscribe

INSTAGRAM


I am very active on Instagram! Join me for updates between newsletters house tours, featured listings, tips, advice and more!


@hudsonvalleynest

 
Instagram  
 

Sandra "Sandi" Park

Licensed Real Estate Broker

Global Luxury Specialist

Senior Transition Partner

Hudson Valley Nest | Coldwell Banker Realty

M: 914-522-6282

Email:  spark@hudsonvalleynest.com

www.HudsonValleyNest.com

Serving the Hudson Valley and Global Luxury Markets