Rates taking a breather from their decline but still looking well below the recent highs.
Borg's Edge Weekly Rates
Chris Borg
NMLS#116995/#891464
Borg Edge Home Finance
503-481-1369
Chris@Borg-Edge.com
Mortgage Rate Update: A Pause After a Nice Rally
Mortgage rates took a little breather this week after the latest CPI report came in hotter than expected, raising concerns that inflation may still be sticking around. There has even been some talk of the Fed potentially raising its federal funds rate by as much as 0.50% at an upcoming meeting.
The good news? We've seen a great rally over the past month, and rates are still well below the recent highs. One week of movement in the wrong direction doesn't erase the progress we've made.
The bottom line: Rates may bounce around, but we're still in a much better position than we were a month ago.
TRUE - INDEPENDENT - MORTAGE BROKER
Rates as of [Wednesday November 11, 2026]
UNDERWRITING FEE WAIVED ON ALL SCENARIOS!!!
LOAN PROGRAM
RATE
APR/POINTS
30 YEAR FIXED
6.990%
7.263% / 0.779
15 YEAR FIXED
6.250%
6.676% / 0.901
FHA 30 YEAR FIXED
6.375%
7.334% / 0.835
VA 30 YEAR FIXED
6.250%
6.665% / 0.504
JUMBO 30 YEAR FIXED
6.750%
6.908% / 0.566
*APR=Annual Percentage Rate. Assumed 760 credit score, OR/WA purchase. Rates include pricing up to a 1% loan fee. Based on $600,000 purchase price with 20% down. FHA APR based on $600,000 purchase price with 3.5% down includes MI. VA with 0% down & 2.15% Funding Fee. Jumbo loan based on $1,125,000 sales price with 20% down/780 credit score. Rates are subject to change during the loan term. That change can increase or decrease your monthly payment. See Hood River Mortgage Group for details. Rates are subject to change without notice.
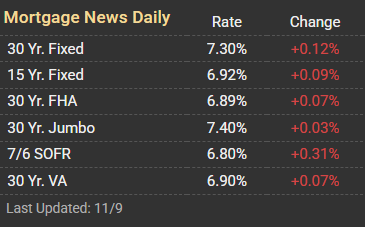
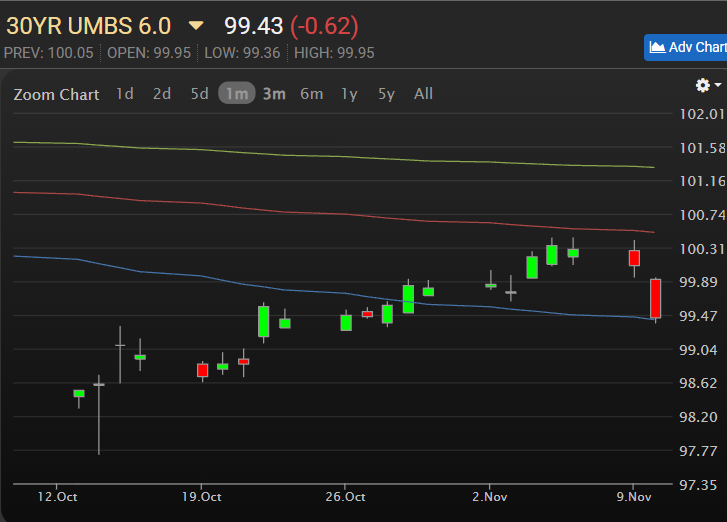
PUBLISHED NATIONAL AVERAGE RATES Mortgage backed securities chart
How Mortgage News Daily Calculates These Rates
Averages are based on actual rate sheets from a variety of wholesale, correspondent and retail lenders, using a consistent “top-tier” borrower scenario. Rates are updated daily as market pricing changes.
The typical scenario assumes:
780 FICO
75% LTV / 25% down
30-year fixed conventional conforming loan
Top-tier agency pricing
No unusual or program-specific pricing adjustments
Actual mortgage pricing can vary based on credit, down payment, loan amount, property type, loan program, points and other factors.
📈 Reading the MBS Chart
MBS prices and mortgage rates generally move in opposite directions.
MBS price ↑ = Good for mortgage rates — pricing improves, which can lead to lower rates.
MBS price ↓ = Bad for mortgage rates — pricing deteriorates, which can put upward pressure on rates.
The one-month chart helps show the overall trend rather than focusing on any single day.
When MBS prices are trending higher, that’s generally a positive sign for mortgage rates.
When prices are trending lower, rates are typically facing upward pressure.s are typically facing upward pressure.
This Week’s Program Highlight: Builder Forward Loan Program
Builders sitting on unsold inventory may have an opportunity to move homes with below-market fixed rates.
A builder forward program can provide buyers with attractive financing incentives, making completed or spec homes more competitive without necessarily cutting the sales price.
Lower fixed rates can help reduce the buyer's monthly payment.
Gives builders another tool to move standing inventory.
Creates an opportunity to connect with builders who have homes sitting on the market.
The strategy for realtors: The catch is getting the builder to work with the agent. Even if the builder doesn't need an agent to sell today's inventory, showing them how you can help move those homes could open the door to the next project.
Don't just chase the listing. Build the relationship. Today's conversation could turn into the opportunity to represent the builder on their next development.
Have questions on how this works?
Give me a call and let's see !
Have First Time Home Buyers?
Ask me about my Oregon Housing Down Payment Assistance Programs
Mortgage Strategy Tips:
Encourage buyers to compare multiple lenders—rate quotes don’t require multiple full applications.
Mortgage brokers can’t mark up government loans (VA, FHA, USDA), making them especially competitive.
Proactively review past clients for refinance or cash-out opportunities.
Ask about DSCR and non-QM options for investor clients.