Q2 2026 | METRO DETROIT CRE INSIGHTS | |
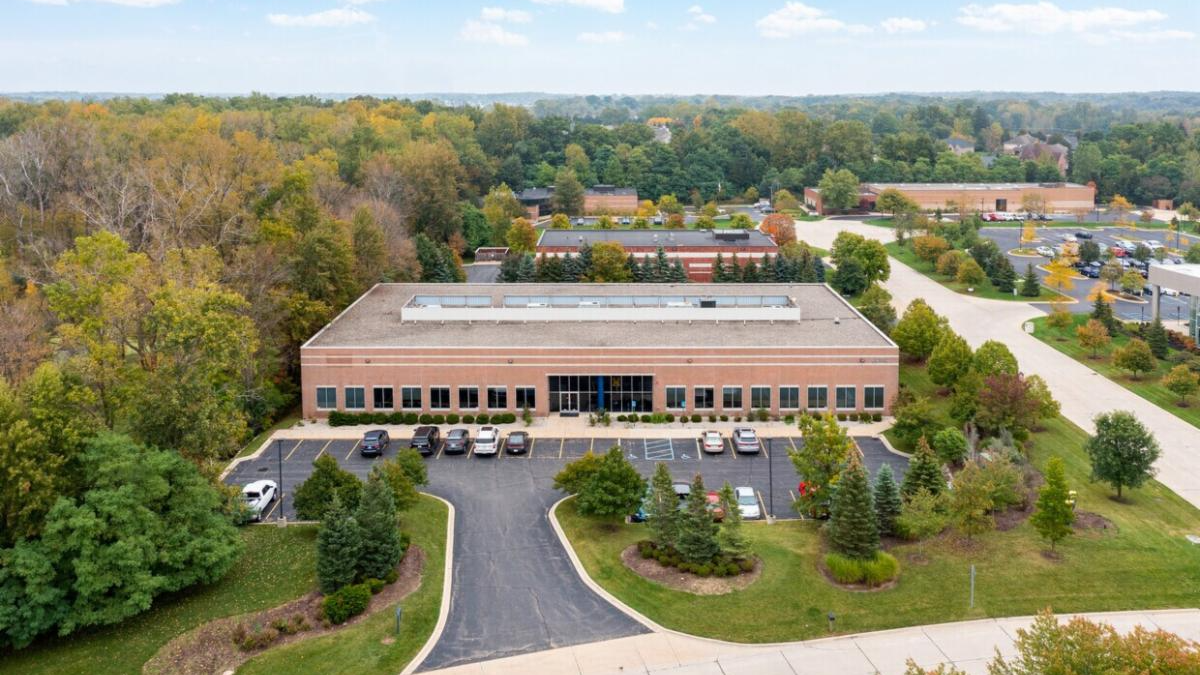
Metro Detroit’s office market continues to navigate a period of transition, but the latest data points to pockets of stability and opportunity beneath the broader vacancy picture. The market currently encompasses approximately 202 million square feet, with vacancy at 12.2% and trailing 12-month net absorption returning to positive territory at approximately 313,000 square feet. Performance varies significantly by property class, tenancy and submarket. For owners and investors, this increasingly segmented environment is placing greater emphasis on asset quality, tenant stability and strategic positioning, while limited speculative development may help support existing inventory over the longer term.
OFFICE STATS
- Vacancy among 4 & 5 Star properties is 18.4%, compared with 12.1% for 3 Star and just 6.4% for 1 & 2 Star inventory.
- Asking rents range from $19.42/SF in the Southfield area to $31.75/SF in Birmingham.
- The roughly 340,000 SF office building at 5151 Corporate Drive sold for approximately $39/SF despite being fully occupied at the time of sale, while Raleigh Officentre, a 300,000 SF Southfield property that was entirely vacant, traded for approximately $27/SF.
- 1.7 million SF is under construction, led by major projects in the CBD, New Center, W of Woodward, and Birmingham submarkets, and an impressive 90% of this space is already preleased.
| | |
Metro Detroit’s industrial market remains fundamentally strong, supported by tight vacancy, positive absorption and continued demand across manufacturing, logistics and distribution uses. The region’s approximately 642 million SF industrial inventory is currently 95.5% occupied, with vacancy holding at just 4.5%—well below the 7.4% national rate. Over the past 12 months, approximately 3.0 million SF of net absorption outpaced 2.2 million SF of net inventory growth, while asking rents increased 2.8%. With construction activity remaining below recent historical levels, Metro Detroit continues to offer favorable fundamentals for industrial owners and investors.
INDUSTRIAL STATS
- Looking at vacancy by subtype, logistics vacancy stands at 5.0%, specialized industrial vacancy is 3.3%, and flex sits at 7.1%.
- Rent levels vary by segment: Logistics spaces have an average market rent of $8.60/SF, compared to $9.10/SF across specialized assets, and $13.00/SF for flex buildings.
- Two of the largest second-quarter transactions involved owner-user acquisitions. Motor City Electric purchased a roughly 233,000 SF manufacturing facility in Roseville for approximately $87/SF, and Shipping Container Corporation acquired 168,000 SF in Canton Twp.
- There is 4.5 million SF of industrial space under construction, with the majority being constructed in the Airport, Livonia, and Auburn Hills/Pontiac/Rochester submarkets.
| | |
Metro Detroit’s retail market continues to strengthen as tenant demand outpaces new supply and vacancy trends lower. The market currently totals approximately 264 million SF, with vacancy at 4.8% and trailing 12-month net absorption reaching approximately 2.2 million SF. That level of absorption far exceeds recent historical averages and has been driven largely by the backfilling of existing anchor, big-box, and second-gen spaces. With limited new construction underway and average asking rents continuing to rise, market conditions remain supportive for well-positioned retail assets across the region.
RETAIL STATS
- Recent large lease transactions with retailers such as Meijer, Ross Dress for Less, TJ Maxx, Nordstrom Rack, Burlington, Planet Fitness, Crunch Fitness, and VASA Fitness show continued demand from value-oriented retailers, fitness operators, and experiential concepts.
- Retail asking rents in Detroit average $19.00/SF triple-net compared with $26.00/SF nationally - from a long-term perspective, we have seen a 13.4% rent increase over the last 5 years.
- Retail investors continue to prioritize assets with durable cash flow, necessity-based tenants, and strong occupancy. Grocery-anchored centers, discount-oriented retailers, fitness users, and net-leased properties remain common targets.
- There is 840,000 SF of retail space currently under construction, with the majority being constructed in Southfield, Dearborn, and the CBD submarkets, and 87% of the development pipeline is pre-leased.
| | | | |
Q2 2026 Deal Activity | Strong Results Across Metro Detroit
P.A. Commercial closed 53 transactions in Q2, reflecting activity across office, industrial, retail, and land properties. Leasing remained a major driver, with 39 lease and tenant representation transactions, while the team also completed 12 sale and buyer representation transactions. Office led the quarter with 29 transactions, followed by 13 industrial and six retail deals. Q2 activity demonstrates continued demand across multiple property sectors and P.A. Commercial’s ability to serve clients on both sides of the transaction.
| | | | |
Big Firm Brokerage vs Boutique Firm: Why the Difference Matters
In commercial real estate, the right strategy rarely comes from a one-size-fits-all approach. P.A. Commercial’s boutique structure allows our team to collaborate across specialties, share market intelligence and adapt quickly as our clients’ needs evolve. For our clients, that means direct access to experienced professionals, personalized strategies and the resources and expertise needed to navigate complex transactions. It’s a model built around relationships—and one that allows us to remain closely involved from the initial strategy through closing and beyond.
| | | | |
Marketing Vs Listing: Why Strategic Property Marketing Matters in CRE
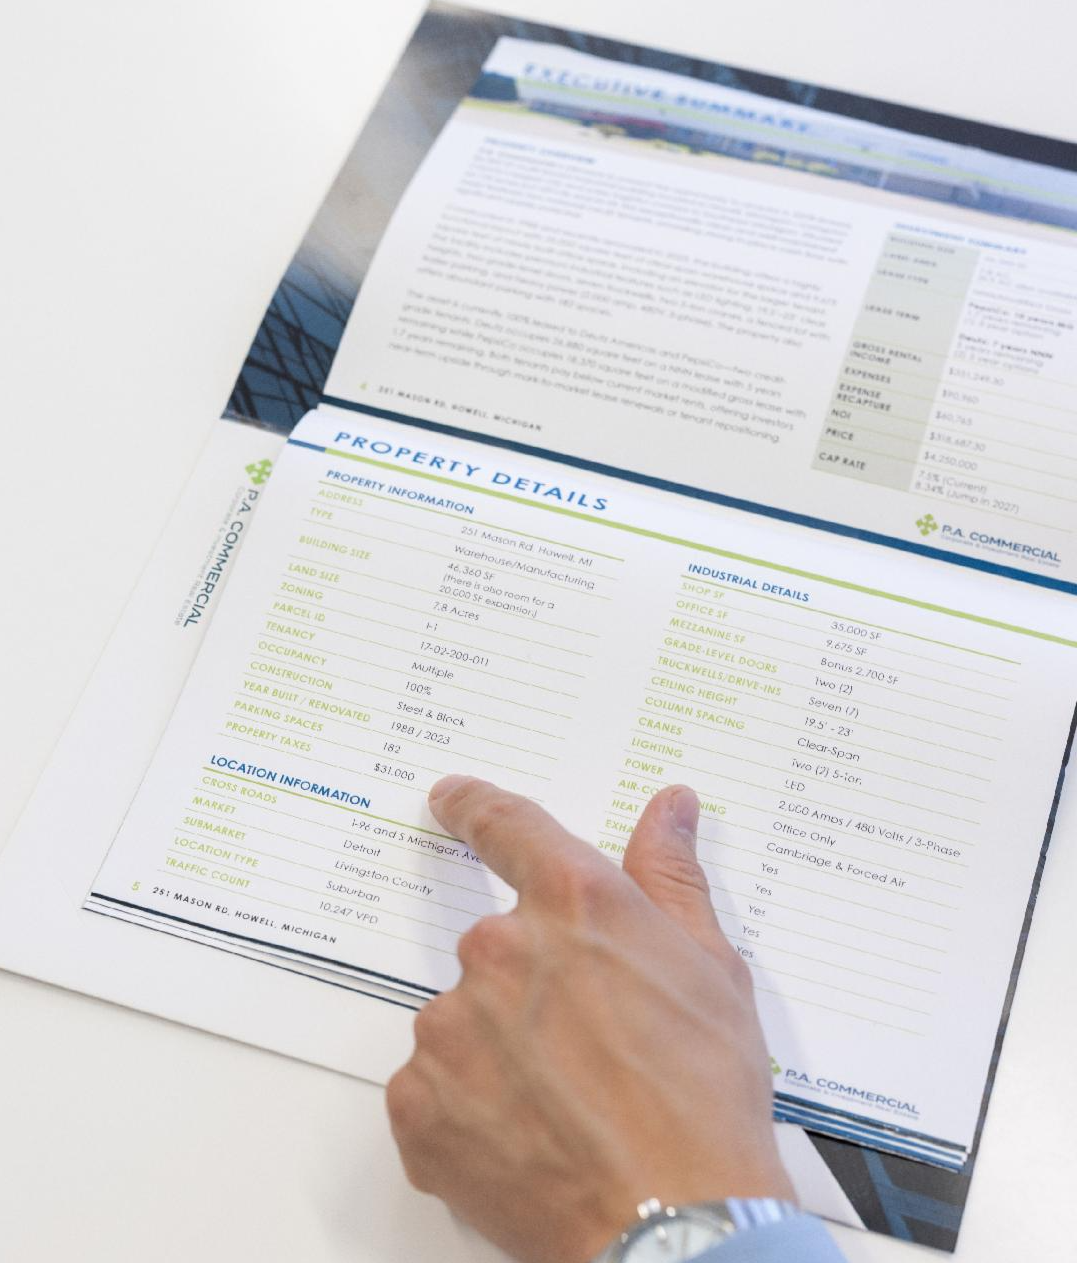
There’s a significant difference between simply listing a commercial property and strategically marketing it. While listing platforms create visibility, effective marketing creates demand through thoughtful positioning, professional materials, targeted outreach, direct prospecting and ongoing performance tracking. In today’s competitive market, property owners should expect more than a sign and an online listing—they need a proactive strategy designed to reach the right buyers or tenants.
| | | | |
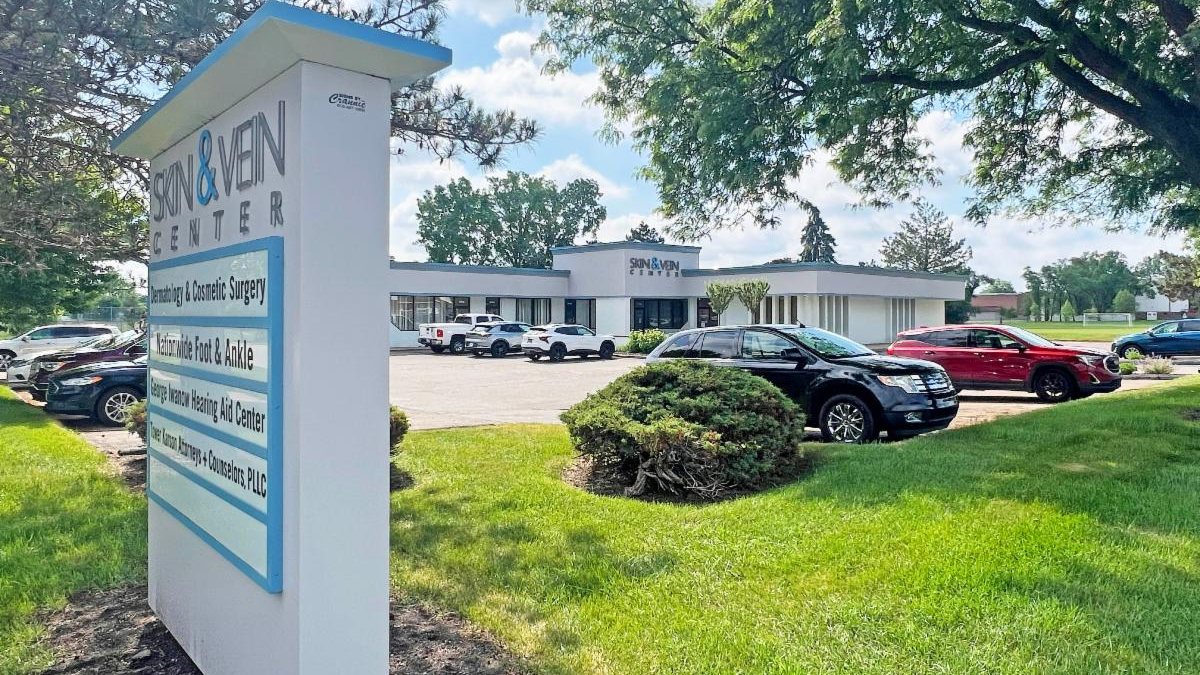
Medical Office Owner/User Opportunity with In-place Income
Address: 10982-10990 Middlebelt Rd
Submarket: Southern I-275 Corridor
Building Size: 9,710 SF
Zoning: C-1
Year Built/Renovated: 1979/2020
Occupancy: 61%
Sale Price: $1,550,000
| | | | |
Investment Opportunity: State-of-the-Art Flex Building
Address: 29770 Hudson Dr
Submarket: Central I-96 Corridor
Building Size: 21,443 SF
Zoning: I-1
Year Built: 2004
Cap Rate: 6.5%
Sale Price: $2,900,000
| | | | |
Value-add Investment:
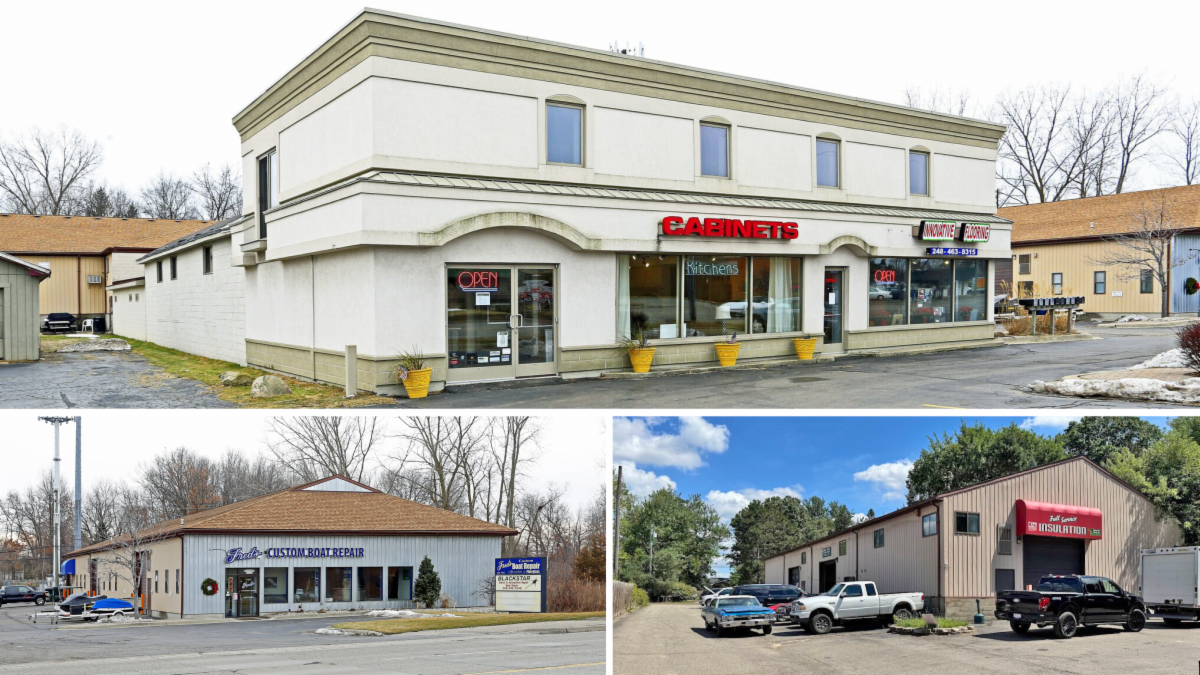
Three-Building Industrial Portfolio
Address: Highland Rd & Tull Dr
Submarket: Lakes Area
Total Building Size: 33,240 SF
Lot Size: 2.9 Acres
Occupancy: 65%
Zoning: BI
Sale Price: $2,999,000
| | | | |
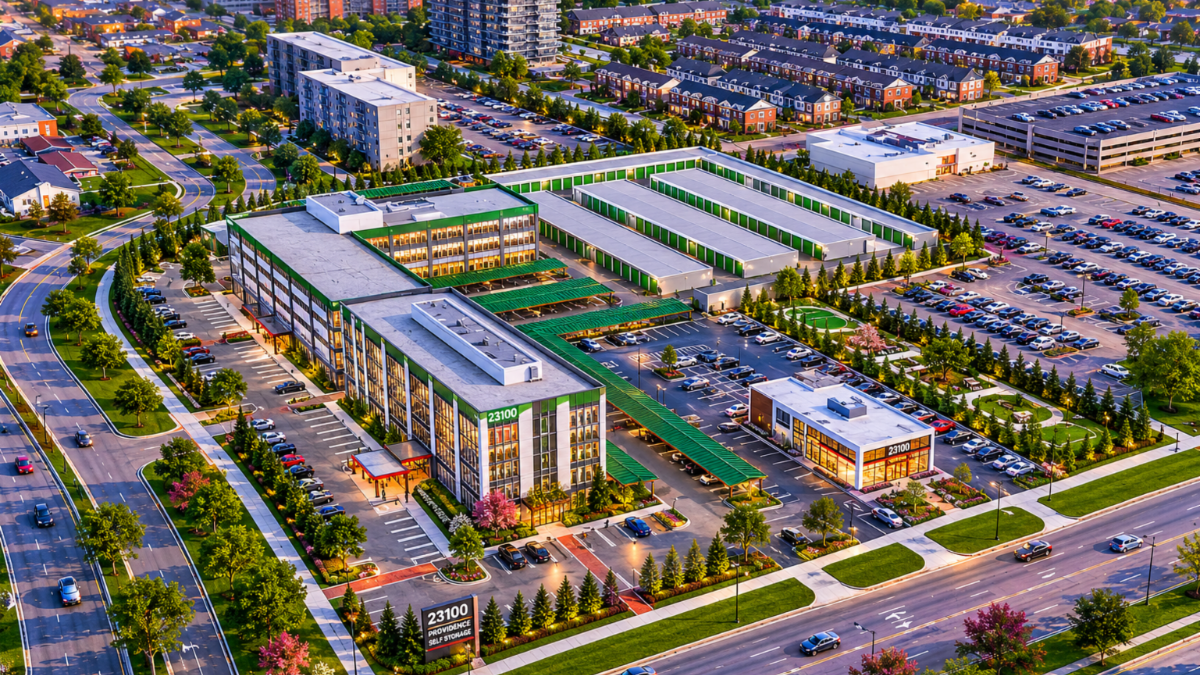
Redevelopment Opportunity: Fully-Entitled Office to Multi-Family Conversion
Address: 1600 W 9 Mile Rd & 23100 Providence Dr
Submarket: Southfield
Building Size: 151,563 SF
Lot Size: 5.8 Acres
Zoning: ODD Potential
Sale Price: $7,500,000
| | | | |
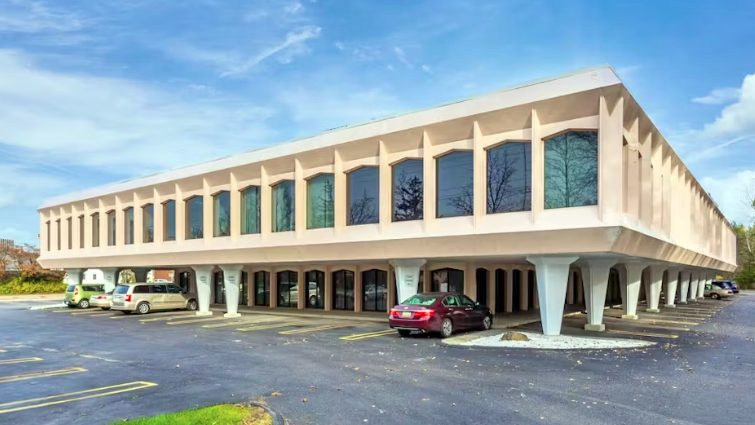
Value-Add Investment: Office Building with Additional Land for Development
Address: 24450 Evergreen Rd
Submarket: Southfield
Building Size: 33,600 SF
Lot Size: 1.80 - 5.39 Acres
Year Built/Renovated: 1971/2020
Cap Rate: 8.01%
Sale Price: $3,400,000 - $3,950,000
| | | | |
Owner/User Opportunity: 100% AC Manufacturing Building
Address: 33891 Doreka Dr
Submarket: Groesbeck Central
Building Size: 14,400 SF
Lot Size: 1.12 Acres
Zoning: M-2
Year Built/Renovated: 1985 / 2021
Sale Price: $1,399,000
| | | | |
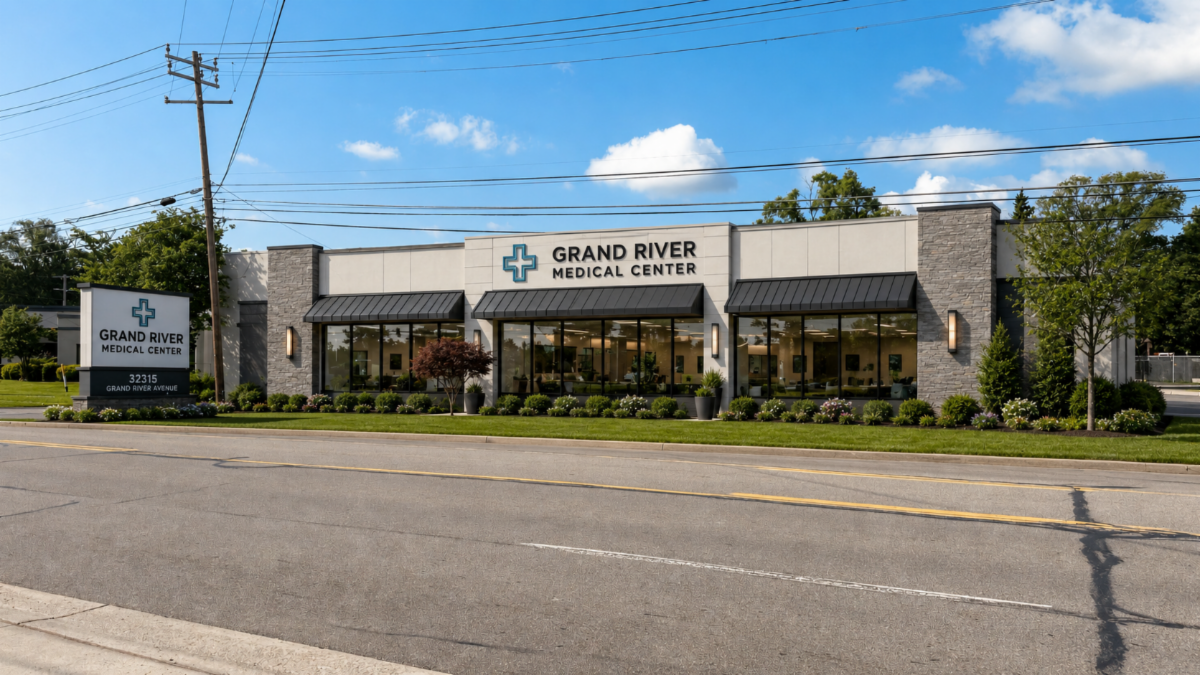
Acquire, Reposition, or Redevelop a Multi-Purpose High-Visibility Property
Address: 32315 Grand River Ave
Submarket: Farmington/Farmington Hills
Building Size: 11,736 SF
Lot Size: 0.86 - 1.37 Acres
Zoning: C-2
Best Use: Medical, Fitness, or Mixed-use
Sale Price: $1,500,000 - 3,000,000
| | | | |
Owner/User Opportunity: Warehouse
in Mt. Elliott Industrial District
Address: 19430 Mount Elliott St
Submarket: Detroit E of Woodward
Building Size: 14,000 SF
Lot Size: 1.4 Acres
Zoning: M-4
Year Built/Renovated: 1950 / 2011
Sale Price: $1,260,000
| | | | |
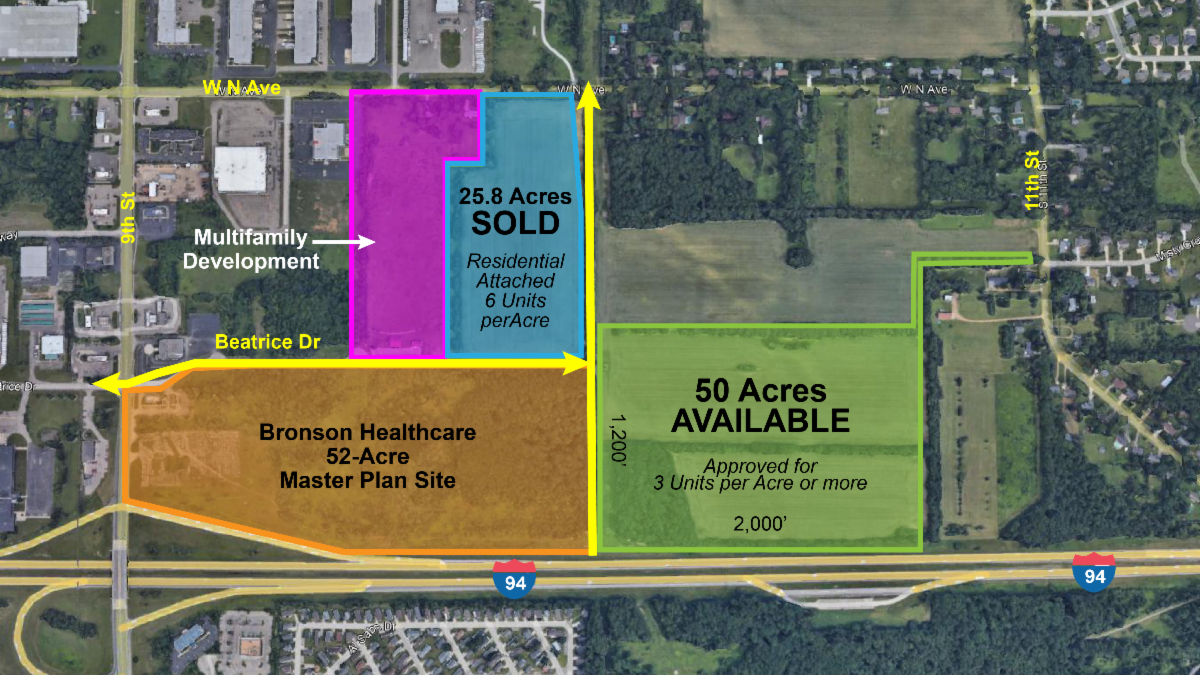
50 Acres of Ripe Land for Mixed-use, Multi-Family or Single-Family Development
Address: Beatrice Dr
Submarket: Western Kalamazoo County
Lot Size: 50-Acres
Zoning: Mixed-use
Frontage: 2000' on I-94
Sale Price: $5,000,000
| | | |
We hope you found this market report helpful and insightful. For additional information and personalized assistance, please contact:
Matt Schiffman
Managing Partner / CEO
D: 248.281.9907
matt@pacommercial.com
|
| | | |