undefined


Noovember 5, 2026

From Rick's desk...


Why Diversification Matters as Stock Market Leadership Shifts


Dear Clients and Friends,


As the last few votes are tallied in the midterm elections and a strong performance by the Democrats brings divided government, the same crosscurrents that have shaped markets this year remain in place:


  • The artificial intelligence (AI) spending boom has drained excess cash flows from some of the biggest U.S. technology stocks and added to their debt loads. However, the investment has also contributed to solid economic and profit growth. Free cash flow, which deducts capital expenditures from operating cash flow, is still expected to increase 11% over the next year (source: FactSet).


  • Interest rates are higher than in recent decades, and the Federal Reserve (Fed) may hike rates in December, but the 10-year Treasury yield has fallen 0.4% over the past month to below 5% and well within historical norms.


  • Oil prices are too high, and inflation remains elevated, but we believe the chances of a diplomatic solution in the Middle East may have increased now that the election is behind us. Market-based measures of inflation expectations remain well anchored, and the Kevin Warsh-led Fed has credibility as an inflation fighter.


  • Midterm elections have historically brought uncertainty and increased market volatility, but that uncertainty has tended to fade quickly once votes are counted. The S&P 500 has been positive in the 12 months after midterms 19 times in a row, dating back to 1950, averaging a gain of over 15%.


Against that backdrop, the average S&P 500 stock gained 5% in October even as the more common market capitalization-weighted index fell 0.9%. As the technology and AI-heavy communication services sectors fell, the other nine sectors rose. As the Russell 1000 Growth Index slipped 6.1%, its value counterpart gained 4.4%. As U.S. large cap benchmarks dipped, small caps eked out a gain. The benefits of diversification were also evident in bonds, as the Bloomberg Aggregate Bond Index gained 2.4% for the month.


The earnings picture is also diversifying, bolstered by a strong U.S. economy that grew at a 3.4% annualized pace in the third quarter, adjusted for inflation. While S&P 500 companies are on track to grow earnings 30% overall in the third quarter, including the big AI spenders, excluding technology, earnings are still growing at a solid mid-teens pace. That’s a key benefit of diversification.


Our message for investors is this: Stay diversified. Own companies using and benefiting from AI, not just those building computing capacity. Keep your focus on strong stock market fundamentals - a resilient U.S. economy and healthy corporate sector. Finally, don’t make portfolio decisions based on political outcomes. Any election-related volatility will likely present an opportunity for long-term investors.

As always, please reach out to me with questions, and I thank you for your continued trust.


Best regards,


Rick


Richard B. Welsh, A.A.M.S.

Founder & President

LPL Econ Market Minute

AI, the Fed, and France: Three Shifts to Watch

LPL’s Chief Economist, Dr. Jeffrey Roach examines how AI, Fed meeting changes, and fiscal pressures in France are shaping the outlook.

From Marie's desk...


Your Money Has a Tax Personality


Dear Clients and Friends,


One thing we notice when meeting with new clients is that many have accumulated savings across various accounts without fully understanding the differences between them - or why someone might choose to prioritize one type of account over another.


And that's perfectly understandable. Between Traditional IRAs, Roth IRAs, 401(k)s, brokerage accounts, and all the variations in between, the financial landscape can feel like alphabet soup.


But here's something worth understanding: Not all dollars are created equal. In fact, some dollars are considerably more cooperative with the IRS than others.

One of the interesting things about financial planning is that two people can have identical account balances and very different financial outcomes. Why? Because where their money lives can matter almost as much as how much they have accumulated.


Think of your money as having three different tax personalities.


The Pay-Taxes-Now Personality


These are the dollars sitting in taxable accounts. Interest, dividends, and realized investment gains may create tax consequences along the way. The upside? Your money remains accessible, and qualified long-term capital gains and certain dividends may receive favorable tax treatment.


The Pay-Taxes-Later Personality


Traditional IRAs and 401(k)s are perhaps the most familiar examples. Contributions may qualify for a tax deduction or exclusion, depending on the account and circumstances, and investments can grow without annual taxation on earnings. Eventually, however, withdrawals generally become taxable income. Uncle Sam may simply be waiting patiently for his turn.


The Pay-Taxes-Never-on-Qualified-Withdrawals Personality


Roth IRAs and Roth 401(k)s bring a different twist. Contributions are generally made with after-tax dollars, but qualified withdrawals - including investment growth - can be tax-free. There are rules, of course, including holding periods and age requirements for Roth IRAs.


Here's where the conversation gets interesting.


Many people spend years focusing on how much money they have saved, but pay considerably less attention to the tax character of those savings. Yet the combination of taxable, tax-deferred, and tax-free assets can influence retirement income, flexibility, and the taxes ultimately paid over a lifetime.


And taxes aren't just a year-end consideration. They can be an important part of the bigger financial picture.


The takeaway? Your money has a tax personality. Understanding those personalities may be just as important as knowing your account balances.


Because when it comes to financial planning, it's not always about how much money you have. Sometimes, it's about how much of it you actually get to keep.


If you have questions about how your accounts fit into your overall financial picture, we're always happy to help you understand the differences and how they may impact your financial future.


Best regards,


Marie


Marie A. Welsh

Partner & Chief Operations Officer

Finding Joy in the Journey

While we take finances seriously, we also believe joy matters. A balanced life isn't just about money - it's about the moments that make you smile. In this section, we share a few of our "little joys" and a glimpse into our personal side.

The Full-Size Candy House 🎃


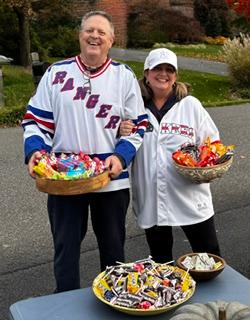
I think we may have officially earned the title of Full-Size Candy House this Halloween! Between the beautiful weather and Halloween falling on a Saturday, we had what felt like a record number of trick-or-treaters. Despite what I thought was an impressive candy stockpile, we were pretty much cleaned out between 5 and 7 p.m. - with at least another hour of little ghosts, goblins, and superheroes still making their rounds. At that point, apologies to the late arrivals, but the minis had to make their debut!


The evening was every bit as fun as the candy chaos. Neighbors gathered at the ends of driveways around fire pits, drinks in hand, costumes on, and plenty of laughs along the way. Rick and I even got into the spirit by dressing as NY fans. (Please don't hold that against us!)


All in all, a wonderful Halloween filled with neighbors, laughter, and enough candy to make us reconsider our inventory management strategy for next year. Apparently, even a full-size candy house can underestimate demand!

What If…?


Ever wonder what’s possible for your financial future? At WFG, our partnership with LPL gives us the tools to help you see all that your future can hold. Watch this short video to learn why we’re proud to partner with LPL and how it strengthens the support we provide you.

Facebook  LinkedIn  X
 

410.777.5897