|
As we move into the final months of 2026, we are pleased to share the latest news and legal developments from our firm. The legal landscape continues to evolve rapidly, with new laws, important legislative changes, and emerging issues creating both opportunities and challenges for individuals and businesses. Our goal is to keep you informed about developments that may affect you, your family, your business, or your legal rights.
As always, we are committed to providing thoughtful, effective advocacy and helping our clients navigate an increasingly complex legal environment. We are grateful for the trust you place in our firm and look forward to continuing to serve you.
| | WILDFIRE RELATED LEGISLATION | | |
Recent Disaster & Recovery Packages:
Major wildfire recovery legislation, including the Smoke Damage Recovery Act (AB 1795) and the Disaster Recovery Reform Act (SB 876), were signed into law by Governor Gavin Newsom to overhaul how insurers test for smoke contamination, handle claims during declared emergencies, and double penalties for insurer delays.
Smoke Damage Recovery Act (AB 1795): Sponsored by Insurance Commissioner Ricardo Lara and authored by Assemblymember Mike Gipson, the act establishes enforceable public health and insurance claim standards for homes damaged by wildfire smoke, soot, and ash. The bill requires the California Environmental Protection Agency (CalEPA), by June 30, 2027, to develop science-based, health-driven standards for sampling, testing, and chemical screening levels in residential properties affected by wildfire smoke. It also creates a rebuttable presumption that if smoke, ash, soot, or char are found in a surviving home within a designated wildfire impact zone, the contamination is legally tied to the fire. Furthermore, the bill shifts the financial and logistical burden of testing from disaster survivors onto insurance companies, requiring insurers to pay for proper assessments and remediation.
Disaster Recovery Reform Act (SB 876):
-
Requires a “disaster recovery plan” from insurers for handling claims and meeting timelines. The Department reviews each plan in advance, and it takes effect in an emergency.
-
Doubles penalties during a declared emergency for violations of fair claims practices and settlement law.
-
Requires insurance companies to pay restitution directly to policyholders when they engage in unfair claims settlement practices.
-
Addresses delays caused by multiple adjusters by requiring insurers to send policyholders a status report within 15 days whenever a new adjuster is assigned.
-
Provides adequate recovery funds through a mandatory offer of extended replacement cost coverage and additional living expenses coverage when a policy is written. Insurers must also provide regularly updated replacement cost estimates for new business and renewals.
-
Supports safer rebuilding by applying building code upgrade coverage at the time of rebuild, not the time of loss, so it accounts for updated rules.
Utility Bailout Bill Defeated
Wildfire survivors and advocates successfully defeated a push by PG&E, Southern California Edison, and San Diego Gas & Electric, backed by Governor Newsom, to bailout California utilities at the expense of wildfire victims. The legislative proposal sought to increase the profits of these utilities, while capping the recovery of fire survivors like damages for emotional distress and litigation costs. What was missing from the discussion? Talk of the utilities taking greater safety measures to ensure that they do not cause wildfires in the first place. The utilities also were not talking about capping their profits so that they can pay full, fair, and complete compensation to wildfire victims.
We, along with advocates from Every Fire Survivors Network and Consumer Watchdog, and other attorneys who work to protect the rights of consumers and wildfire survivors, fought hard through our own media campaign and discussions with stakeholders and defeated this bailout attempt.
| CHANGES IN EMPLOYMENT LAW | |
Official 2027 Minimum Wage and Exempt Salary Hikes
On July 31, 2026, the California Department of Finance officially certified the state's inflation-adjusted numbers for the new year. Effective January 1, 2027, California’s statewide minimum wage will increase to $17.40 per hour for all employers, regardless of size.
Because California ties its white-collar exemptions to the state minimum wage, the minimum annual salary required to maintain an executive, administrative, or professional exemption will rise to $72,384 ($1,392 per week).
While the current local rates in cities like San Francisco ($19.61/hr), San Jose ($18.45/hr), Sunnyvale ($19.50/hr), and Mountain View ($19.70/hr) already vastly exceed the state floor, over 30 jurisdictions will further update their municipal minimum wages on January 1, 2027, based on regional Consumer Price Index (CPI) changes.
SB 1149 — Bereavement leave for a “designated person”
California already requires employers with five or more employees to allow up to five days of bereavement leave for the death of a family member. SB 1149 adds a “designated person identified by the employee” to that list,. Employers may limit an employee to one designated person per 12-month period.
AB 1803 — Anti-hate speech component in harassment training
Beginning January 1, 2028, the biennial sexual-harassment prevention training that employers with five or more employees already provide must include an anti-hate speech component. The training must address workplace speech that vilifies, humiliates, or incites hatred based on protected characteristics.
Year-End Compliance Checklist
Before January 1, 2027, employers should consider taking the following steps:
- Update payroll systems for the new minimum wage.
- Review exempt employee salary thresholds and classifications.
- Confirm applicable city and county minimum wage rates.
- Review pay ranges, compensation policies, and pay equity practices.
- Update employee handbooks, onboarding materials, and workplace notices as needed.
- Train HR personnel and managers on applicable changes.
As always, if you have questions about how to navigate California’s labor and employment laws, contact our team of seasoned employment litigators and counselors, Amanda L. Riddle, Steven M. Berki, Sumble Manzoor or Tyler K. Larson.
| |
I’ve Established My Trust!... Now What?
Many people assume that once they’ve signed and notarized a trust instrument, they are done. Unfortunately, that is incorrect. That is only the first step because the trust sits empty and will stay that way until you retitle assets into the trust to fund it.
“But what does that mean?”
It means you have a signed document that has little power over the plans you carefully made to distribute your property. Property, assets and accounts must be titled in the trust’s name. But fear not, for all you must do is have the trust or a Certification of Trust with you when you speak with financial institutions, insurance agencies, title companies, etc., and the agent helping you will assist with the rest.
Trustee Checklist:
When you created the trust, either your lawyer or whoever assisted you should have asked what property you intend to fund the Trust with. This matters because it dictates what is usually called Schedule “A” of your trust. This schedule lists your trust property and will likely change over time. What you had when you established the trust won’t be the same forever.
If you have a home, the Schedule “A” should list it. But the property is not in the trust until it is retitled into the name of the trust.
Step 1: Retitle Assets into the Trust
Work with a lawyer or title company to prepare the requisite grant deed and assessor forms placing your real property into your trust. If the title history shows that the property belongs to “John Smith, an unmarried man” or to “Jane Doe and John Doe, a married couple with right of survivorship,” then your property is not in your trust. Rather the property will need to be deeded into the trust e.g. “Jane Doe and John Doe, Trustees of the Doe Family Trust dated 1/1/2000.” Also, speak with your financial agents about retitling your accounts into your trust.
Step 2: Add your Trust as an Additional Insured
For those with homeowners’ insurance, especially, it is imperative that you let your insurance agent know you have a trust and you want it to be named as an additional insured on the policy. You don’t want to be in a situation where you need coverage, and the insurer issues a denial because your home is in a trust and it isn't listed as a policyholder.
Step 3: Regular Maintenance
You do not have to update your trust every single year, but it is important to review it every few years, especially when new events occur:
- If you inherit or purchase property after creating the trust or after the death of the first spouse in a Marital Trust, make sure the new property is titled in the trust.
- If you refinanced property that was titled in the trust, confirm with the agent who helped you or an attorney whether that property was placed back into the trust after the transaction was completed.
- Make sure you have and then review your alternate Successor Trustees. You never know what life will throw your way, and that is true for your named agents. Consider whether the individual may decline to serve, and who you would want to step up in their place.
- What has happened on a political scale? New bills may change your tax situation for better or for worse. Some terms of your trust may need to be adjusted to navigate or take advance of these changes.
- Finally, family circumstances may have changed. Kids grow up, get married, and have kids of their own. Is your trust keeping up with your current intentions?
Of course, this is not an exhaustive list. It may look intimidating at first, but once you have created the trust and handled all the “start-up,” it will be a well-oiled machine you bring to the shop regularly for a tune-up from time to time.
If you want to learn more about setting up an estate plan or have any questions on the above, feel free to contact our estate and probate team: Stevan N. Luzaich, Andrea A. Nguyen, Dallas E. Dean, Celyn O. Coker or Kyler B. Jerome.
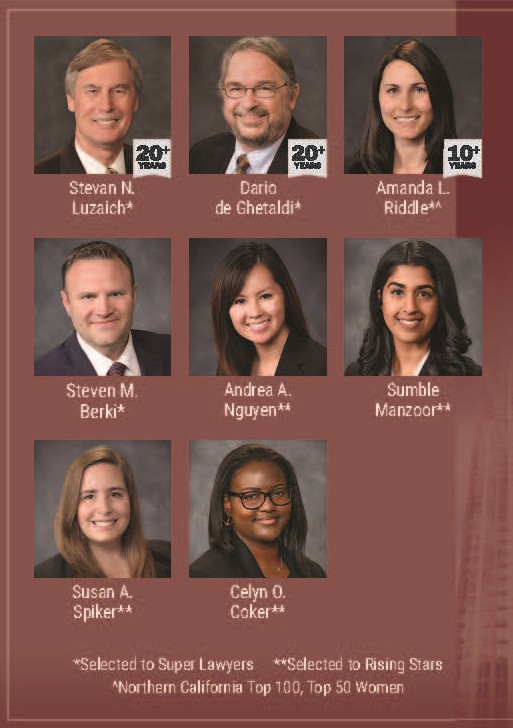
| Congratulations to our Northern California Super Lawyers and Rising Stars! Super Lawyers’ attorney selection process is peer influenced and research driven, selecting the top 5% of attorneys to the Super Lawyers list and top 2.5% of attorneys to the Rising Stars list each year. | | |
New Board Member Appointments
| | This newsletter should be considered informational only. Nothing in this newsletter is intended to create an attorney-client relationship. | | | | |