December 5, 2024 | Capital Market Updates From BWE's PEAK Team | |
|
Federal Open Market Committee (FOMC)
- Final meeting of the year scheduled for December 18
- Key economic indicators, November Nonfarm Payrolls (to be released tomorrow), and November Consumer Price Index (CPI) due next Wednesday, are pivotal to the Fed’s decisions
- Economists expect a significant rebound in Nonfarm Payrolls (+215K) after weak October data (+12K jobs)
- Mixed labor market signals this week
- Job openings exceeded expectations
- Private payrolls (ADP Employment Change) fell short of forecasts
- Weekly initial jobless claims slightly increased and continuing claims decreased
Federal Reserve remarks
- Fed Chair Jerome Powell acknowledged reduced downside risks to employment
- Powell emphasized a cautious approach to finding a neutral interest rate
- Market sentiment reflects confidence in a quarter-point rate cut at the next meeting, 70% to 75% likelihood
Treasury yields and market dynamics
- Treasury yields remained stable
- 10-year yields hover around 4.20%
- Short-term yields dipped as markets adjusted near-term expectations
- Yield stability supported by international political uncertainties (South Korea, France)
Commercial Mortgage-Backed Securities (CMBS)
- Strong rate lock activity
- ~$600M of Fannie Mae DUS rate locks reported by midweek
- Freddie Mac announced plans to sell $1.96 billion in Participation Certificates (PCs) for December
- Investor spread trends
- Tightened slightly for generic Fannie Mae DUS structures
- Credit spreads for investment-grade indices remain steady or marginally tighter
- Best pricing awarded to large-sized loans ($25 million+), full-term interest-only structures, and low-leverage arrangements
| |
|
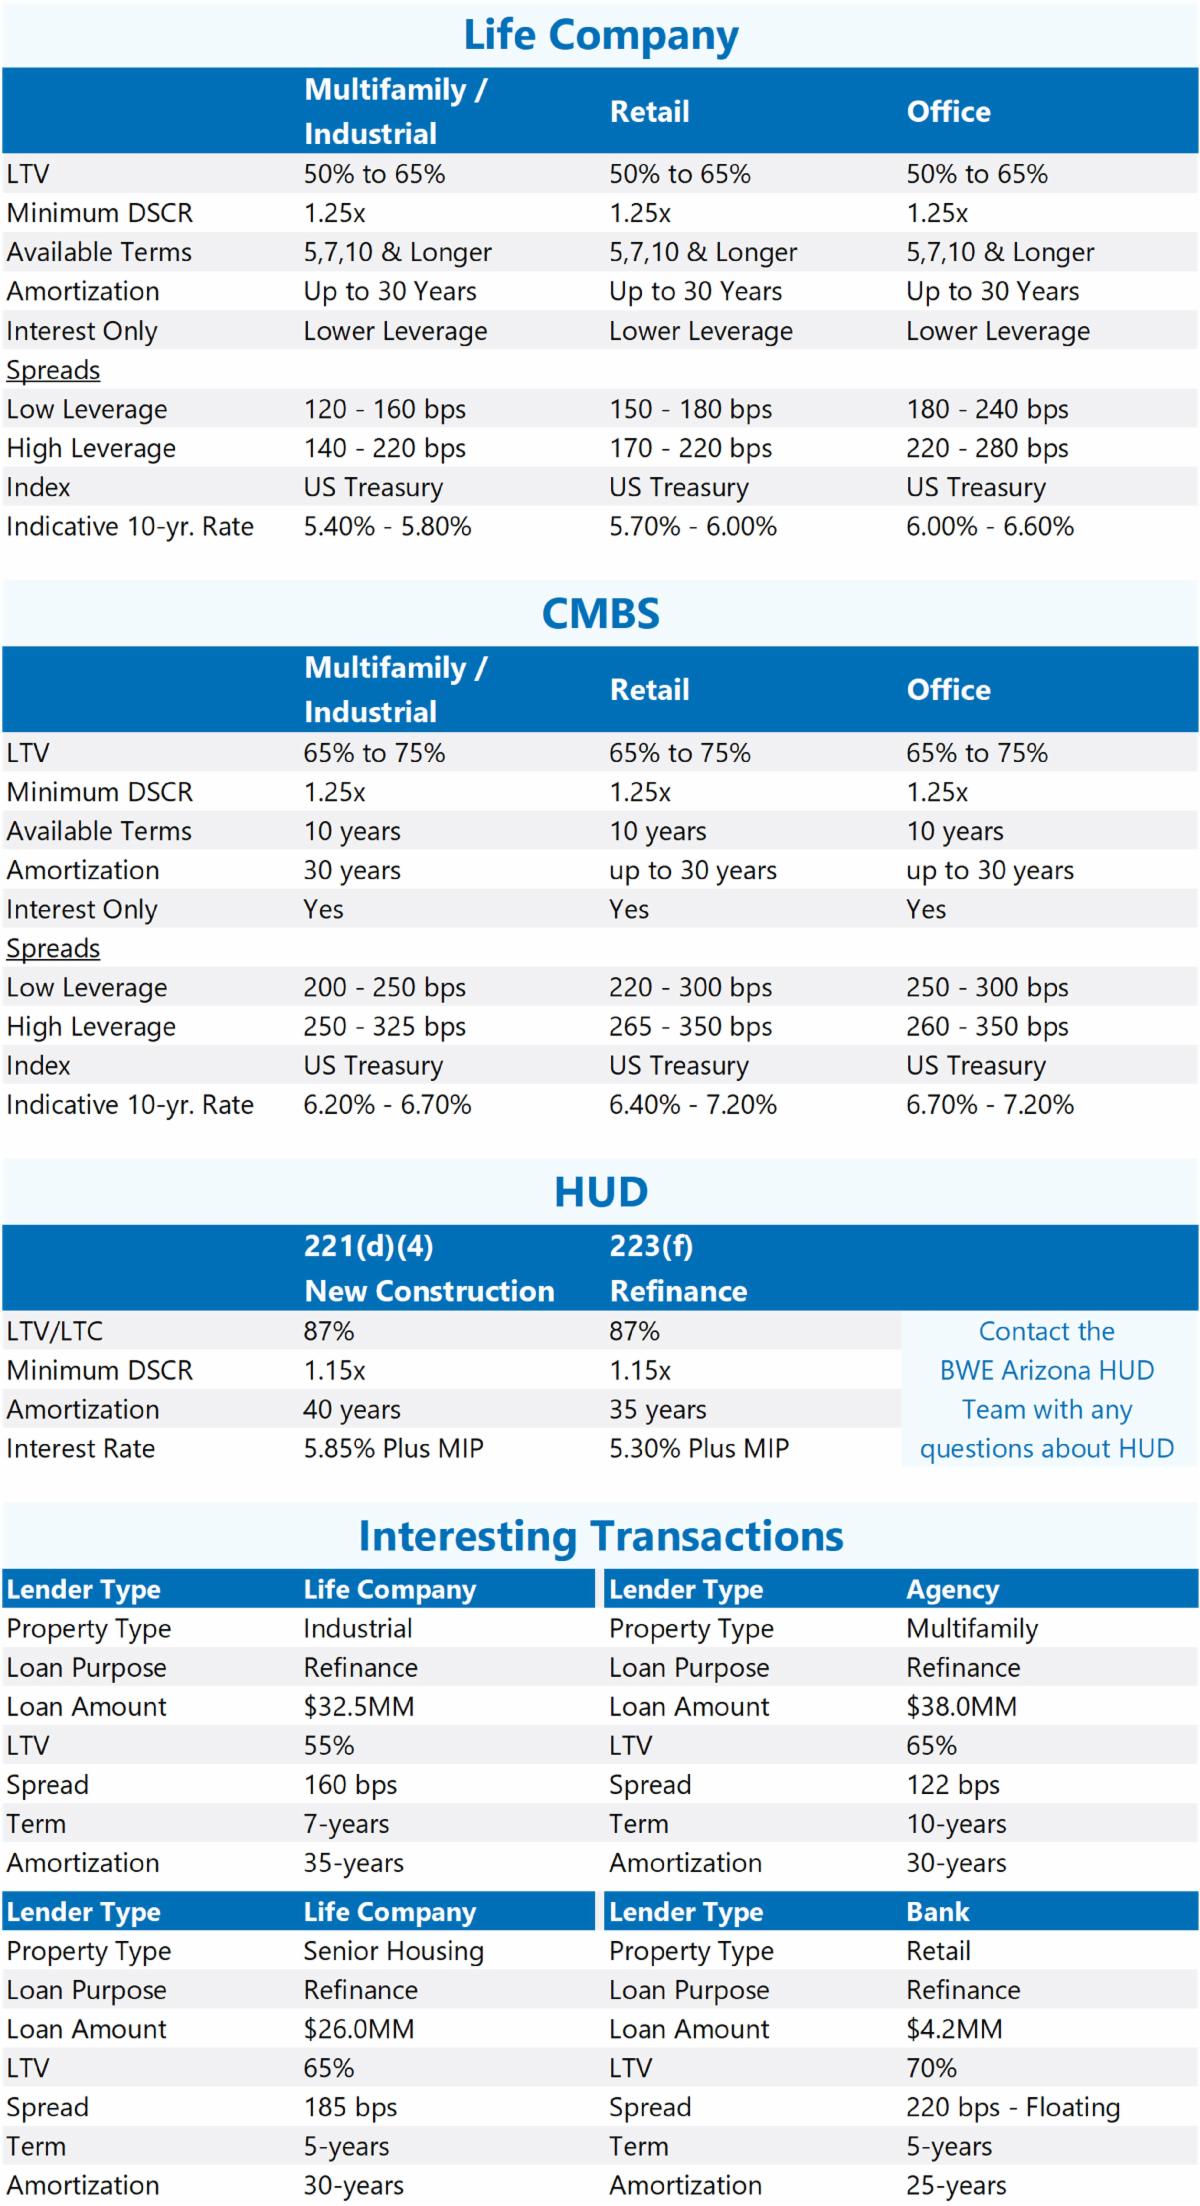
With the recent dip in U.S. Treasuries ending the month of November, Life Company lenders reported a heavy volume of loan activity and getting under application ahead of the Thanksgiving holiday. Lender spreads have remained between 160 to 200 basis points for well-located, good-quality, and stable properties. However, the decline in the benchmark 10 year has brought coupons in the mid to high 5% range on recent rate locks.
Outlier pricing for high-quality properties in major markets, coupled with low-leverage requests, can price 20 to 40 basis points lower. Single-A Corporate spreads to Treasuries have remained in the high 50 bps range as of the first part of this week.
| |
- Recent dip in U.S. Treasuries prompted strong loan activity with many deals being rate locked in the mid to high 5% range
- Life Company lenders have indicated 2025 allocations are similar to their 2024 production and are seeking opportunities with good borrowers to kick off the new year
| |
|
Borrowers dash to the finish line: Despite the holiday-shortened week, Agency CMBS rate lock activity was vigorous as borrowers raced to squeeze in loans ahead of year-end MBS deliveries. Weekly new issue rate lock volumes for Fannie Mae DUS/MBS surpassed $1.4 billion, nearly double the year-to-date average of $780 million.
Markets continued to award large-sized ($20 million+), standard structured (5/4.5, 7/6.5, 10/9.5), full-term, interest-only loans with interest rate buydowns with the tightest pricing, and an additional benefit is conferred to loans with low leverage (Tier 3/Tier 4).
Over the past few weeks, Agency CMBS traders have witnessed an expanding end-investor base looking to purchase Fannie Mae, Freddie Mac and Ginnie Mae products. The account base looks to be a healthy balance of banks (large and small), money managers, life companies, pension and hedge funds, etc.
Tight Agency credit spreads (Fannie, Freddie and Ginnie) were rangebound last week, though traders noted that spreads may see further tailwinds based on recent underperformance in relative value compared to similar products in the corporate investment-grade credit space along with the pool of investors expanding of late with the resurgence of bank appetite appearing.
Tighter and stable spreads: Over the past few weeks, Agency traders have witnessed an expanding end-investor base looking to purchase Fannie, Freddie and Ginnie products. The account base looks to be a healthy balance of banks (large and small), money managers, life companies, pension and hedge funds, etc. Recognizing the recent heavy new issuance supply of Agency CMBS paper hitting the market, credit/investor spreads are holding steady as end accounts efficiently absorb the elevated supply. Banks have played a major role in this as their reemergence into purchasing Agency paper has created additional competition driving these spreads down overall.
| |
|
Driving spreads lower: Banks have played a large part in keeping spreads low in the Agency market because of their reemergence into the space. Historically, banks have been a primary buyer but backed out of the market following the regional bank crisis two years ago. As the Basel III endgame gets closer, banks have more clarity into how they will look at liquidity requirements on their books and thus they are buying Agency paper.
Fulcrum for activity: A 4.20% Treasury rate has been the tipping point for borrowers in 2024. Activity increases significantly when the 10 year is below 4.20% and Agencies have early rate lock options for borrowers to take advantage of timing Treasuries.
Estimated Agency volumes: Overall in 2024, both Agencies will fall short of their maximum allotment of $70 billion each, but Freddie Mac will be close. In 2025, both will have an increased $3 billion allocation for a total of $73 billion each. Fannie Mae is likely to end the year in the range of $50 billion, while Freddie Mac is still targeting a range of $67 billion to $68 billion for year end.
| |
|
Freddie Mac Refinance
- $17,300,000 loan
- 10-year fixed / full term IO
- 70% LTV / 1.30x DSCR
- 1.52% spread before buydown
- Limited to no affordability
| |
|
Following the heaviest issuance month in two years, November added steadily to the year’s total, bringing the cumulative to $94 billion – a substantial increase compared to $33 billion in 2023. The market is on track to exceed $100 billion in annual issuance for the first time since 2021 and only the third time since 2008.
This growth has been largely driven by refinancing activity, as acquisition volumes have declined this year. Despite the uptick in loan flow, spreads have remained stable, with some tightening observed on super-senior AAA tranches. Looking ahead, market analysts anticipate continued strength in 2025, bolstered by a wave of upcoming loan maturities.
Loan pricing and terms
Currently, 10-year CMBS loans are pricing in the low-to-mid 200 basis points over Treasuries, while 5-year loans are in the mid-to-high 200s. For multifamily properties, lenders continue to provide full-term, interest-only financing, allowing borrowers to maximize loan proceeds.
Underwriting typically supports a 1.25x debt service coverage ratio on an interest-only basis. These terms, combined with lower interest rates and rate buydown options, make CMBS financing especially appealing to multifamily property owners, often surpassing agency alternatives in both proceeds and interest-only flexibility.
Other asset classes, such as office properties, have also benefited from favorable full-term, interest-only financing offers. However, these loans generally feature more conservative leverage and higher debt yield requirements.
| |
|
Opinions, estimates, forecasts and all other information contained in this document are those of Bellwether Enterprise Real Estate Capital, LLC (“Bellwether”) and should not be construed as indicating Bellwether’s business prospects or expected results. Although Bellwether attempts to provide reliable, useful information, it does not guarantee that the information or other content in this document is accurate, current, or suitable for any particular purpose. All content is provided on an “as is” basis, with no warranties of any kind whatsoever and is subject to change at any time without notice. Information in this document may not be used without permission from Bellwether. This document is not intended to be an offer to buy or sell or a solicitation of an offer to buy or sell securities, if any, referred to herein.
Bellwether Enterprise Real Estate Capital, LLC (BWE) conducts business through Bellwether Enterprise Mortgage Investments, LLC – Mortgage Banker license #BK-1007784 – the Department of Financial Institutions State of AZ (Fannie Mae transactions), as well as Bellwether Enterprise Real Estate Capital, LLC – Mortgage Banker License #BK-1007825 – the Department of Financial Institutions State of AZ (all other transactions).
| | | | |