November 18, 2026 | BWE Arizona | Putting clients first. Trusted to be part of their future. | | | Agency
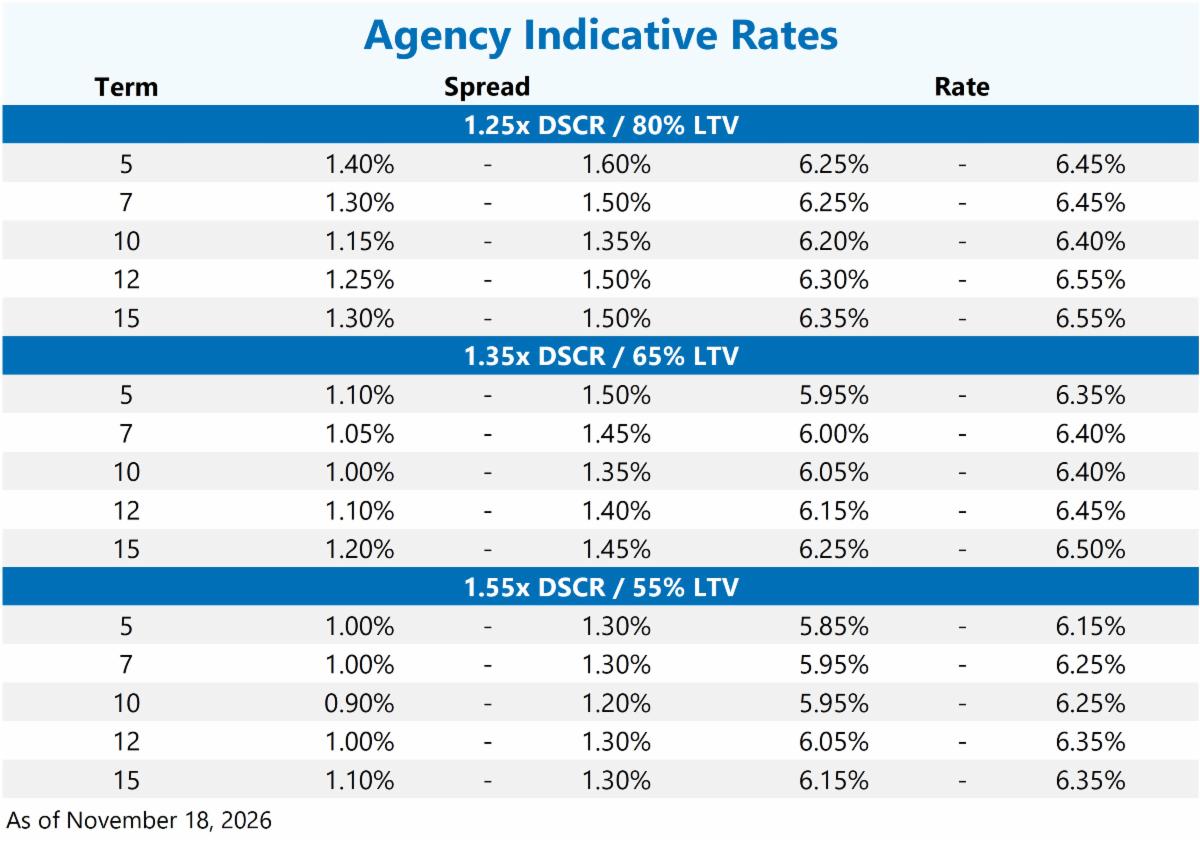
5.95%
0.90% + 10yr UST
Low leverage multifamily refinance | Life Company
6.25%
1.20% + 10yr UST
Low leverage multifamily refinance | | | |
Key takeaways
- This week marks a critical inflection point for monetary policy expectations. Hot October CPI and PPI data, combined with Fed Governor Waller's openness to a 50-bps rate hike, have pushed markets to price certainty into a December rate increase and initiated pricing for 75 bps of cumulative tightening through June 2027.
- The sharp Treasury selloff has created one of the most volatile weeks of the year, with the 2-year climbing nearly 40 bps and the 10-year rising 34 bps on a weekly basis.
- Coming Fed speakers, including Chair Warsh and other voting members later this week, will be closely monitored for additional signals regarding the December decision and the magnitude of potential rate moves.
Inflation and monetary policy
October CPI report
Last week's October CPI report delivered inflation readings that slightly exceeded expectations across both headline and core measures.
- Headline CPI rose 0.4% MoM, slightly exceeding expectations.
- Core CPI rose 0.3% MoM, meeting expectations and hitting Fed Governor Waller's previously stated threshold for considering a stronger policy response.
- The fact that core CPI met the 0.3% threshold puts a potential 50 basis point rate hike firmly in play for the December FOMC meeting.
October PPI report
- The Producer Price Index showed business-level annual inflation at 6.5%, the highest level since late 2022.
- The elevated PPI reading reinforces persistent inflation pressures across the supply chain.
Fed rate hike expectations
Hot inflation data and hawkish Fed commentary have reshaped rate hike expectations.
- CME FedWatch shows a December rate hike as a certainty.
- A 50-bps move in December is currently priced at roughly 9–13%.
- Swap traders are beginning to price in 75 bps of cumulative rate hikes between now and June 2027.
- Fed Governor Christopher Waller's openness to a 50-bps hike has injected hawkishness into the market narrative.
- The open question remains whether the Fed will move by more than 25 bps at the December 8–9 FOMC meeting.
Treasury yield volatility
Last week's Treasury selloff hit the front end of the curve hardest, though volatility was broad-based.
- The 2-year yield climbed nearly 40 basis points from trough to peak.
- The 10-year yield moved within a 34-bps range, its widest weekly range year-to-date.
- The 2-to-10s curve has flattened to about 28-34 bps the prior Friday.
- The 10-year yield sits at 5.13%, breaking back above 5.00% on the back of hot inflation data and hawkish Fed commentary.
Energy markets
- Brent crude sits near $93 a barrel after a sharp decline earlier in the month.
- The softening in oil prices provides some relief to inflation dynamics, though energy remains a key variable for Fed policy decisions.
| | |
It is that time of year when CRE industry conferences and events start to ramp up. Below is a shortlist of regional/national conferences where you can find us. If there is an event you think we should check out, please let us know by emailing Carla Goettsch.
January 26-28
National Multifamily Housing Council (NMHC) Apartment Strategies + Annual Meeting, Las Vegas, NV
February 7-9
Mortgage Bankers' Association (MBA) Commercial/Multifamily Finance Convention and Expo, San Diego, CA
| | |
Agency CMBS spreads stay steady: Fannie Mae DUS/MBS weekly rate locks reached approximately $900 million (prev. week ~$580 million), with investor spreads flat to marginally tighter.
Fannie Mae DUS/MBS new issue rate locks rebounded from the prior week’s lighter pace, even as interest rates rose sharply late last week. In the holiday-disrupted week, DUS rate-lock volume reached approximately $900 million, up from roughly $580 million for the full week prior. Most of the activity came from two large block trades last week: a roughly $160 million 10/9.5 full-term interest-only deal and a $500+ million 5/4.5 full-term interest-only portfolio.
Despite the sharp move higher in Treasury yields, Fannie Mae DUS/MBS investor spreads were roughly unchanged to marginally tighter week-over-week, consistent with the stability in corporate credit, where the CDX North America Investment Grade 5-Year index closed the week at 59 bps (Prev. 61 bps). Freddie Mac also priced the $778 million K-569 transaction this week, a 5-year fixed and floating rate deal backed by fixed-rate collateral.
Quick hits
Observations
- Maturities and construction take out opportunities remain the main driver of volume for the agencies. However, we are seeing an uptick in acquisitions taking shape.
- We are seeing some markets continuing to battle concession burn off, which can be a challenge for maximizing Agency loan proceeds. In other markets, with less supply issues, we continue to evaluate Near Stabilized and Lease Up opportunities with the Agencies.
- On the structuring front, we continue to see a lot of requests for 5-year fixed rate terms
Tools
- 35 Year Amortizations and Buydowns continue to be active tools to increase proceeds.
- Freddie Index Locks and Fannie Mae SRLs continue to be utilized to take interest rate risk off the table
Buydowns
- Freddie remains very open to allowing a 3% buydown if it makes the deal work – and with the caveat that proceeds with a buydown will max out at 70% LTV.
- Fannie continues to reserve a 3% buydown for larger deals and repeat clients that have $100 million in Fannie debt outstanding.
- On 5-year loans, the buydown benefit is roughly
- 23-24 bps at 1%
- 45-46 bps at 2%
- 62-70 plus bps at 3%
Prepay flex adders
- Five-year loans can be structured in the last two years at 1%. This adds roughly 18 bps with Freddie and 25 bps with Fannie Mae.
Loan highlights
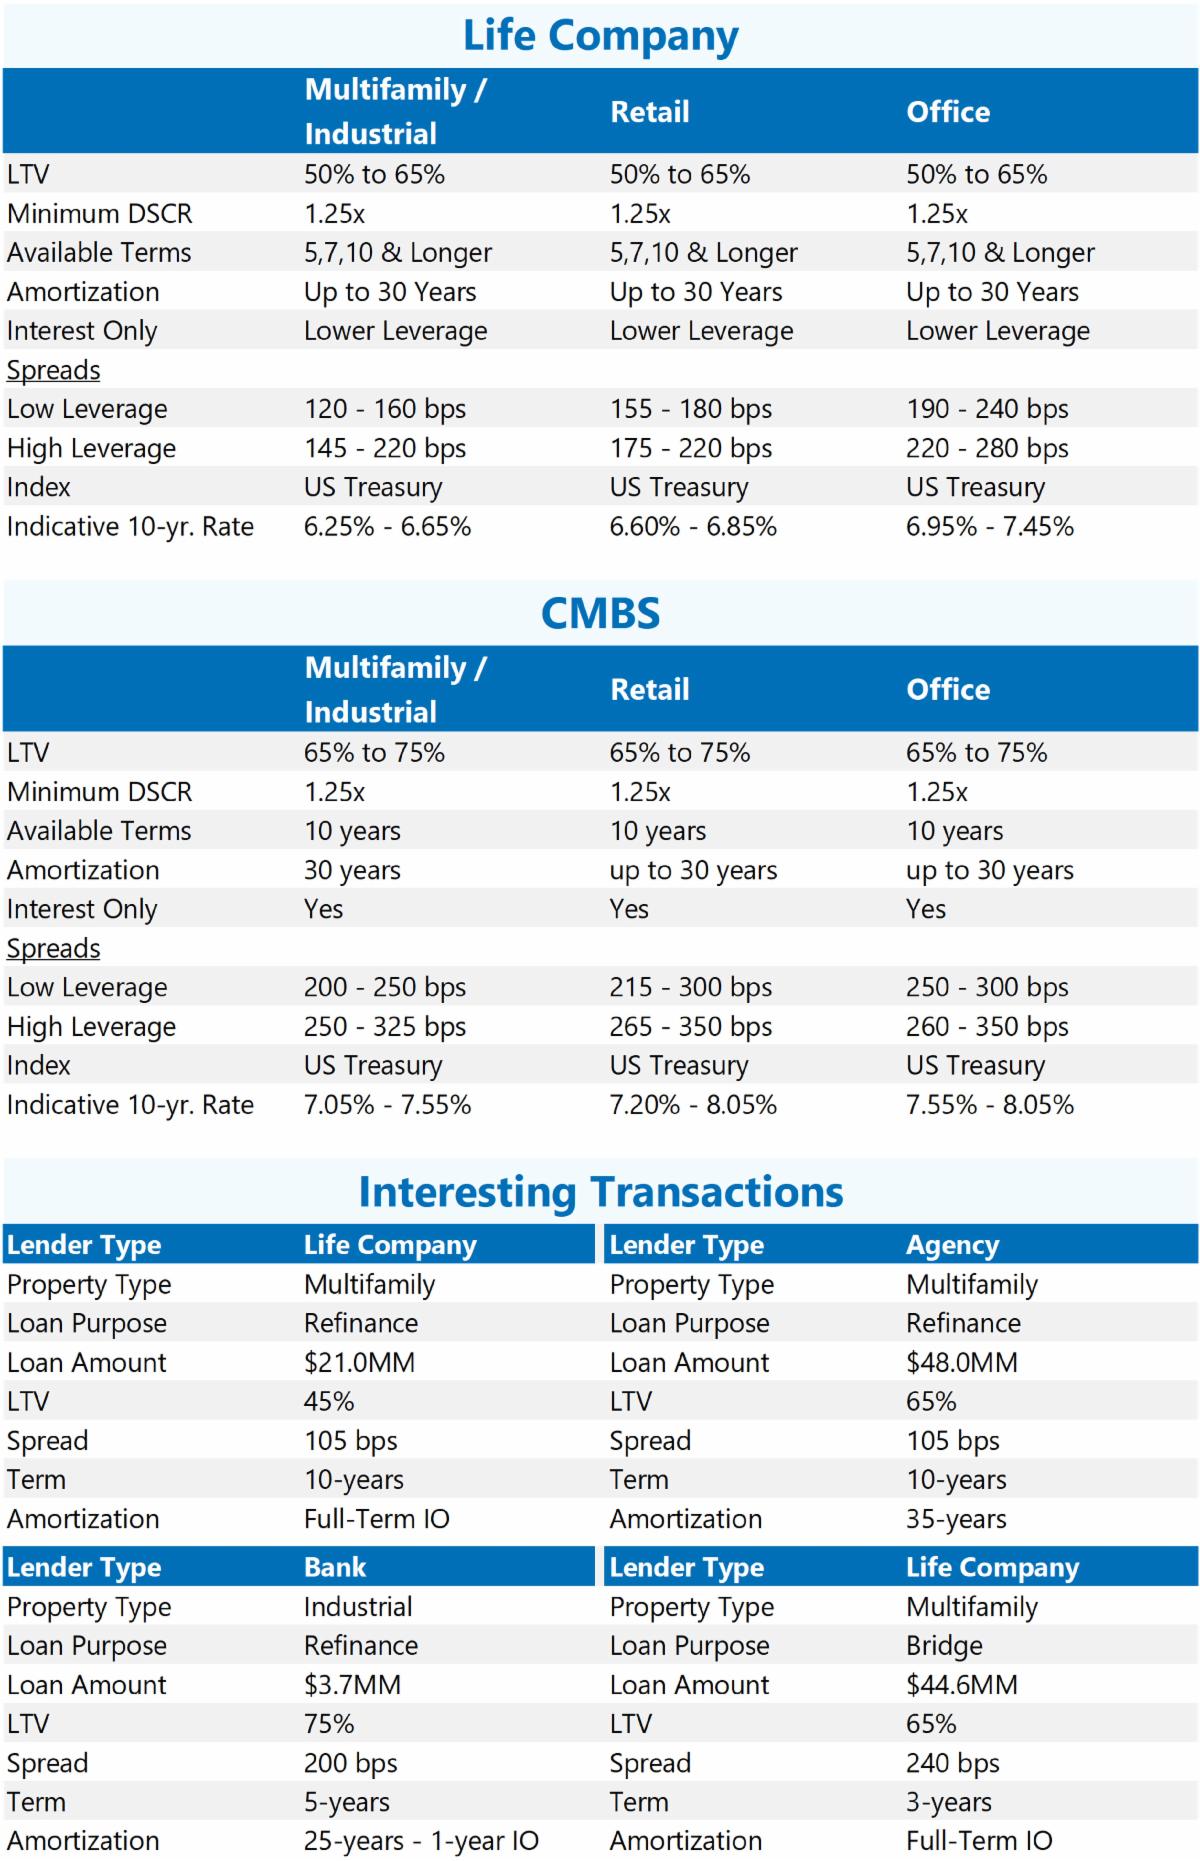
Freddie Mac refinance in Fort Wayne, IN
- $48 million
- 105 bps spread
- 10-yr term / 35-yr amortization
| | |
Life Company lenders are focused on closing loans under application prior to year-end 2026 while starting to review new loan opportunities to kick off their pipeline for first quarter 2027 fundings. Loan allocations for 2027 are expected to be consistent with 2026 production levels, although lenders have not provided specific details.
Strong demand for shorter term capital in the second half of 2026 predicts an equally strong appetite for three to five-year capital to start the year and is projected to make up a sizable portion of lender allocations. Life Company spreads for good-quality, well-located and stable properties have remained range-bound during most of the year, falling between 130–180 bps on short-term fixed rate loans. Outlier pricing for exceptional opportunities could be lower by 10-20 bps.
Consistent with the previous report, core floating rate programs are being priced with spreads generally between 160-225 bps over SOFR and carry a minimum interest period plus a lender origination fee. This approach allows the borrower to refinance the debt during the loan term without penalty into longer-term fixed rate debt when the interest rate environment settles to a desirable level.
| | |
U.S. CMBS issuance now totals approximately $116.2 billion year‑to‑date, ahead of the $111.0 billion level at this point last year. Conduit spreads have widened in recent weeks with 10‑year AAA spreads currently at 81 bps over Treasuries—above the trailing 12‑month average of approximately 75 bps. Borrower spreads widened among recent volatility, although have remained mostly range‑bound over the past several months. Ten‑year CMBS loans are generally pricing at 200–225 bps over Treasuries, while five‑year CMBS loans are pricing in the low‑to‑mid 200 bps range. For high‑quality, low‑leverage transactions, pricing can be as low as 150 bps over Treasuries.
Multifamily assets continue to attract strong lender demand with CMBS lenders maintaining a willingness to offer full‑term, interest‑only structures. These loans allow borrowers to maximize proceeds with underwriting typically supporting a 1.25x DSCR on an interest‑only basis. In addition, several CMBS lenders have secured dedicated B‑buyers for multifamily‑only securitizations, enabling the introduction of “stretch senior” executions. These loans are generally priced at 180–225 bps over Treasuries and can be sized down to a 1.20x DSCR on an interest‑only basis.
Other property types including office have also benefited from the availability of full‑term, interest‑only financing. However, these transactions are subject to more conservative leverage constraints, higher debt yield requirements, and tighter overall underwriting standards compared to multifamily loans.
| | |
About BWE
Bellwether Enterprise (BWE) is one of the nation's largest privately-owned real estate financing companies. Its trusted advisors combine innovation, extensive experience and strong lender relationships to optimize a loan's capital stack for commercial and multifamily investors, developers and property owners. For more information, visit BWE.com.
| | |
Opinions, estimates, forecasts and all other information contained in this document are those of BWE and should not be construed as indicating BWE’s business prospects or expected results. Although BWE attempts to provide reliable, useful information, it does not guarantee that the information or other content in this document is accurate, current, or suitable for any particular purpose. All content is provided on an “as is” basis, with no warranties of any kind whatsoever and is subject to change at any time without notice. Information in this document may not be used without permission from BWE. This document is not intended to be an offer to buy or sell or a solicitation of an offer to buy or sell securities, if any, referred to herein.
Bellwether Enterprise Real Estate Capital, LLC (BWE) conducts business through Bellwether Enterprise Mortgage Investments, LLC – Mortgage Banker license #BK-1007784 – the Department of Financial Institutions State of AZ (Fannie Mae transactions), as well as Bellwether Enterprise Real Estate Capital, LLC – Mortgage Banker license #BK-1007825 – the Department of Financial Institutions State of AZ (all other transactions).
| | | | |