|
September 30, 2025
NEWSLETTER
| | Workers’ Compensation, Experience-Modifier, and How Litigation is Adding to Your Claims | | |
Introduction: Insurance costs for auto, garage liability, EPLI and Workers’ Compensation (WC) continue to climb. For WC policies effective September 1, 2025, the California Department of Insurance has approved a rate increase of about 9%. Other states are also in the same league. It is a good time to know how the premiums are calculated and how to bring the premiums down!
Background. Workers’ Compensation (WC) insurance is mandatory in the United States and many other countries. It ensures employees receive medical treatment and disability benefits for workplace injuries, while protecting employers by providing immunity from employee lawsuits for alleged negligence. WC premiums are paid entirely by employers and represent a significant, manageable business expense. Rate increases are attributed to significant increase in legal expenses (see the ad on the side of the highways), rising medical and claims costs, more cumulative trauma claims, and increased claim adjustment expenses.
Cost Containment. WC premiums are calculated using a base rate that reflects job duties, payroll size, and the number of employees. This base rate is then adjusted by an experience modifier (X-Mod) tied directly to the frequency and severity of workplace injuries. Losses are calculated from claims paid by the insurance company, so every claim impacts your premium for multiple years. Preventing injuries is the most effective cost-control strategy. We assume you are running a lean operation with payroll expenses under control.
Being Proactive: Reducing both injuries and claims, starts with a proactive approach to safety and claims management. Employers should:
- Form and maintain an active Safety Committee
- Designate an approved medical clinic. Seek a clinic approved by your insurance carrier and post details on your Employee Notice Board.
- Encourage open communication
- Document thoroughly
- Accident Investigation
- Employee Statement of Injury
- Employee Counseling
- Declination of treatment by employee
- Verify coverage for contractors working on your premises e.g., detail company, gardeners, etc. Get coinsured on their policies. Your WC policy covers only employees on your payroll!
| | |
Post-Claim.
-
Promptly report all claims to the carrier—even declinations with signed forms. In California, the 90-day rule for workers' compensation claims means that if the insurance carrier fails to accept or deny a claim within 90 days of it being submitted to the employer, the claim is presumed accepted. Any delay in submitting claims can have claims accepted by default even the fraud ones and they can cost you a pretty penny.
- Ensure supervisors investigate each claim and notify your carrier if legitimacy is in question. Flag the 3 F claims: frivolous, fictitious, or fraudulent. If a third party is at fault, pursue subrogation.
- Offer modified duty, when possible, to reduce costs. In California, an employee who unjustifiably declines a bona fide offer of modified work during a workers’ compensation claim may lose certain benefits—especially temporary disability payments.
- Work closely with your claims adjuster by providing requested information quickly for efficient claim handling.
Managing Your Claims. Stay actively engaged in the claims process—ask for updates frequently. Open claims with high reserves are a major reason X-Mods increase. Remember that legal expenses do not affect your X-Mod, but illegitimate claims should always be challenged. Sometimes settling quickly is more cost-effective than allowing claims to linger. For litigated cases, voluntary resignations may be part of the settlement strategy. The best claim is one that is prevented, and the next best is one that is promptly closed.
Calculating Costs. We used payroll data and losses incurred over a four-year period are used to calculate an employer’s workers’ compensation premium. For example, the 2025 X-Mod basis for policy renewal on January 1, 2025, are WC claims from 2021, 2022, and 2023. While 2024, most recent year’s claims are excluded from the X-Mod calculation, it remains critical for underwriting. Even with a favorable or “credit” X-Mod, a dealership with multiple recent claims may be viewed by carriers as having a weak safety culture, leading to fewer quotes and/or higher premiums.
Checklist before submitting your data.
- Is payroll data correct? – Payroll data for service department that includes both technicians and service drivers together will cost you. The risk for service advisors behind computer screens in an air-conditioned office is much lower than a technician working in the shop with physical risks from moving machinery, heavy lifting etc. and hence a lower premium rate for advisors. Ensure they are classified differently. See class codes below.
- Are X-Mods calculated correctly? Per insurance brokers 75% of all X-Mods are incorrect.
- Are subrogated & joint claims included or missing?
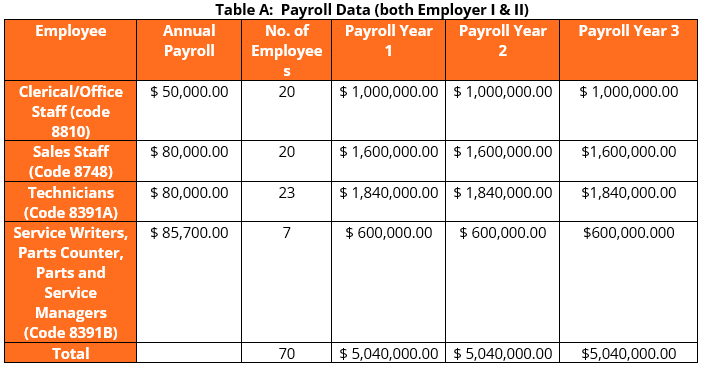
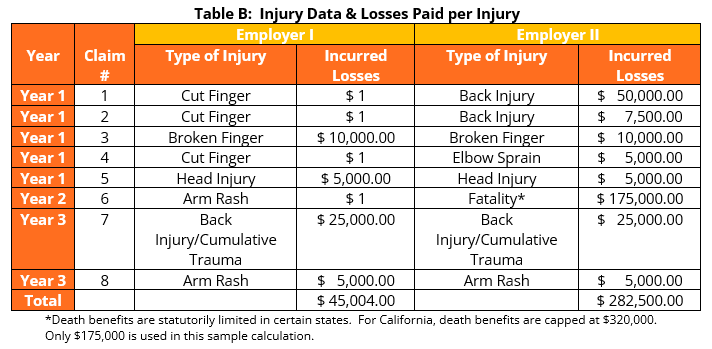
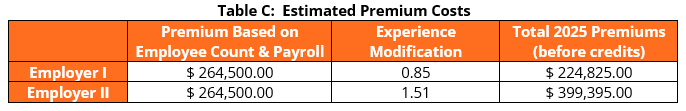
Cost Savings. To illustrate insurance premium calculations (which may vary based on the difference in injury rates), hypothetical calculations were made for two employers, Employers I and II, who have the same payroll. Table A shows the payroll data for each type of employee. Table B illustrates the excessive injuries of Employer I and Employer II. Employer II has four more injuries than Employer I, resulting in a total loss of $282,500 instead of a total loss of $45,004 during the same period. While the insurance company pays these losses, the difference for the two premiums is $174,540. A savings of $174,540 for fewer injuries (Employer I, see Table C) offers a competitive advantage. The fact that injuries affect the premium rate for three consecutive insurance years shows how important it is to prevent workplace injuries. Investing in time, training, and equipment for employees is worthwhile, especially with significant premium savings of the magnitude described in our example. The benefits of being a caring, proactive, employee well-being focused employer in terms of employee productivity and morale are important additional considerations.
Class Code 8391A vs 8391B (CA only)
-
Class code 8391A applies to service technicians, porters, and drivers. Any employee of the dealership who is engaged in repairs, maintenance, service, detailing, or cleaning of automobiles or trucks should be assigned to this class code. Any employee engaged in driving or transporting automobiles or trucks should also be assigned to this code. Parts drivers should also be assigned to this code.
-
Class code 8391B applies to service writers, estimators, parts managers, parts counter-persons, and service managers.
| | |
Note 1. Wages and employee count for employees (CA automobile dealership) in Table A are fictitious and used illustratively.
Note 2. Experience Modification in Table C uses California rates and formulas. Calculations for other states will vary.
Note 3. Table C premiums are before underwriter’s “risk adjustment” debits, credits, or premium discounts (if any). Good safety record will bring you discounts from good carriers. Conversely, a bad safety record will bring increased premiums.
| | Please leave your comments via email to sam@cellyservices.com. | | | | Have any Questions, Comments, or Concerns? | | DISCLAIMER: The contents of this newsletter are for informational purposes only and are not to be considered as legal advice. Employers must consult their lawyer for legal matters and EPA/OSHA consultants for matters related to Environmental, Health & Safety. The article was authored by Sam Celly of Celly Services, Inc. who has been helping automobile dealers across the United States comply with EPA and OSHA regulations for over 38 years. Sam is a Certified Safety Professional (No. 16515) certified by the National Board of Certified Safety Professionals. Sam received his BE (1984) and MS (1986) in Chemical Engineering, followed by a J.D. from Southwestern University School of Law (1997). Sam is a member of the American Chemical Society (No. 31176063), American Industrial Hygiene Association (No. 124715), and National Association of Dealer Counsel (NADC). Sam also serves on the Board of Orange County American Industrial Hygiene Association and on CA Industrial Hygiene Council (CIHC). Our newsletters can be accessed at www.epaoshablog.com. Your comments/questions are always welcome. Please send them to sam@cellyservices.com. | | | | |