|
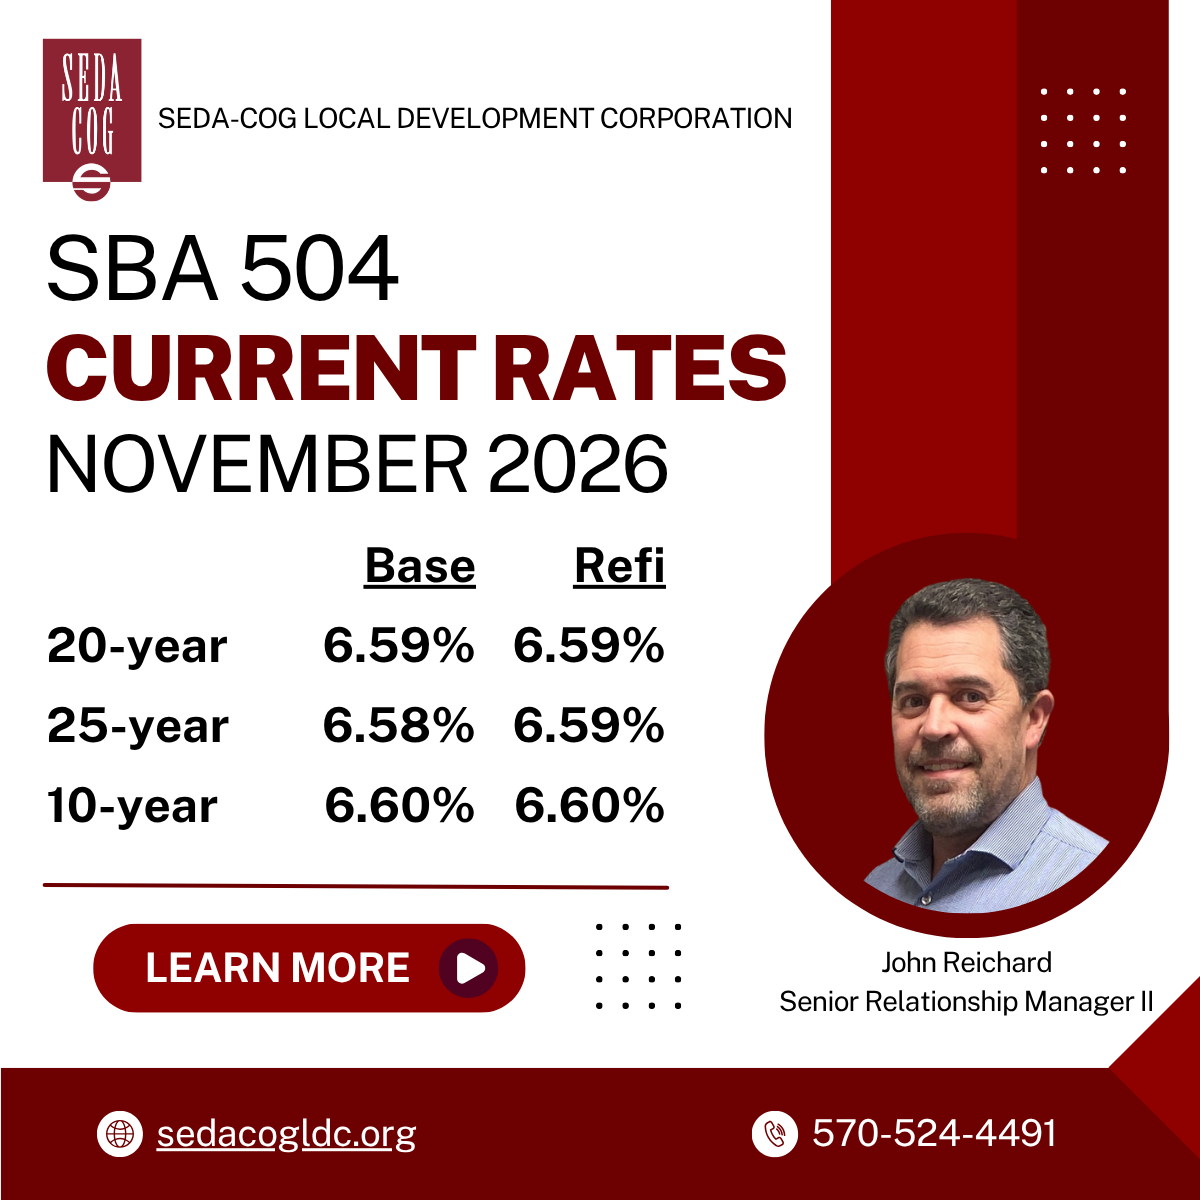
NADCO, the trade association for the nation's Certified Development Companies (CDCs), has released the SBA 504 fixed interest rates for November 2026. Eagle Compliance, the Fiscal Agent for the SBA 504 Loan Program, responsible for the marketing, pricing, and selling of the debentures sold to investors to fund the SBA 504 Loan Program, stated that November saw SBA interest rates fall sharply amid concerns that a Democratic sweep of Congress could lead to tighter AI industry regulation and lower investment in the sector, prompting investors to seek safe-haven alternatives, which sent the U.S. Treasury 10-Year rate lower ahead of the SBA bond offerings.
According to Eagle Compliance, a week before the SBA bond sales:
Fed Holds Steady, AI Slumps
Wednesday’s Fed announcement of no change was expected, though two Fed Governors dissented, opting for a 25 bps rate increase. Initial reaction for Treasuries was muted, but AI stocks dragged down the major indexes with reports that missed expectations. The most significant of them was from Alphabet, the parent company of Google, which lost half a billion dollars of value after earnings disappointed investors, triggering a 12% price decline, and that only got worse. By the end of the week, other disappointing reports from Amazon, Meta, and Microsoft brought the market value loss for these four hyperscalers to almost $900 billion, triggering a resumption of the safe-haven trade into Treasury securities that left the 10-Year Benchmark at 4.94%, 34 bps lower than when the 504 program priced its October debentures.
This market activity is not deterring Anthropic from planning a $63 billion IPO, for which Blackstone Group says an investment-grade rating is needed, as the company lost $81 billion in the first half of 2026 and there is fear that it is expected to receive a “high” junk rating after its initial public offering. That rating would increase its future cost of funding as it announced a “bold but sane” plan to spend more than $800 billion on computing infrastructure between now and 2045.
To say the least, the company is all-in on AI.
The crypto world shared some of this pain as Binance suspended all withdrawals after being hit by a $6.3 billion hack but restarted withdrawals on Sunday. The theft took 30 minutes to complete Thursday night and involved 200 different cryptocurrencies. Some of that money was able to be frozen, but about $3.3 billion had already been converted into digital assets. The FBI reported a North Korean entity named Trader Traitor was responsible for the heist.
Expectations & Reports
The futures market forecast for the December 9 FOMC meeting holds steady at 77% for a 25 bps rate hike after a week that saw the forecast for 3Q2026 GDP increase to 3.4% from 2.2% and better than its 3.1% forecast.
The Fed’s preferred inflation gauge came in a bit stronger than expected, with Personal Income at 0.2% and Personal Consumption outpacing that at 0.5%. PCE m/m was 0.5% from 0.3% and y/y it was 3.6% from 3.4%.
Considering steady job gains, inflation concerns, and strong economic growth it is surprising the probability of a December 9 rate increase is not higher.
Following the bond sales, Eagle Compliance reported:
What a week it was!
As we approached the November SBAP sale the market’s “risk-off” tone which had permeated the market the prior month, was still present. Additionally, it was recognized that our November announcement would coincide with the mid-term elections. Many of those races were expected to be close and as the results were expected to drive U.S. policy over the next several years it had the potential to move markets significantly. There was some concern that it could prove distracting to our November offerings. The week’s expected economic releases were light, the most significant of which was the October payroll report due on Friday, post SBAP pricing.
Since the September 10-Year pricing, 5-Year UST yields had risen 6 bps to yield 4.76%, and 10-Year UST yields had fallen 33 bps since the October pricing to yield 4.95%. Month over month, comparable ACMBS new issue and secondary market spreads were mildly wider by 2 to 3 bps. SBAP 25-year paper was quoted in the secondary market at spreads in the mid-50s, but those levels were not attracting much investor response. The 2/10s portions of the UST Curve had flattened 17 bps month over month, while the shape of other portions of the curve remained largely unchanged. Collectively, the election, large rally in U.S. Treasury 10-Year yields, and a cautious investor perspective led to the conclusion that this sale might be challenging. With these factors in mind, it was decided that the suggested initial pricing spreads on the November offerings would be +45 bps on the 10-Year SBAP (over the 5-Year UST), +52 bps on the 20-Year, and +60 bps on the 25-Year SBAP (both over the 10-Year UST). The 10-Year SBAP was 7 bps wider, the 20-Year SBAP 2 bp wider, and the 25-Year SBAP 3 bps wider; each from the last pricing of each issue.
Tuesday’s election resulted in the Democratic Party gaining a majority in both the House and the Senate; the party’s victories across the country were widespread and, in certain cases, surprising, as in some cases very deeply rooted Republican territories elected a Democrat. Concerns that the Democratic sweep of Congress could lead to tighter AI industry regulation and lower investment in the sector weighed on sentiment, prompting investors to rotate out of tech and AI-related stocks and triggering a broader risk-off mood in the equity markets. However, dip-buying emerged on Friday, and the sell-off paused, particularly across major chipmakers. Over the week, the S&P 500 was down nearly 3%, the Dow was off over 1%, and the Nasdaq was down around 3.6%. U.S. Treasury yields declined over the week as investors sought safe haven alternatives. The U.S. Treasury 10-Year was 4.85% at week's end, a decline of 10 bps over the week, which certainly helped during the pricing of the November SBAP issues.
Investor response to the $12.9 million 10-Year and $488.7 million 25-Year was very positive; for the $25.2 million 20-Year it was more moderate. It was therefore decided the spread on the 10-Year and 25-Year offerings could be narrowed by 3 and 2 bps, respectively, while the spread on the 20-Year issue would remain unchanged. The 10-Year, 20-Year, and 25-Year SBAP offerings were priced at +42, +52, and +58 bps, respectively. The November debenture rate for the 10-Yr. was 5.08%, for the 20-Year it was 5.39%, and for the 25-Year it was 5.45%. The coupon level on the 10-Year issue was 1 bp lower than the prior offering; the 20-Year and 25-Year were 39 bps and 40 bps lower, respectively. The 25-Year rate is 9 bps over the program life average of 5.36%, and the spread over Treasury (+58) was 20 bps below its program life average of T+78. Banks purchased the majority of the 10- and 20-Year issues, while the 25-Year issue was more evenly split across account types.
On Friday, the Non-Farm payrolls report jumped by 165k in October, more than double the 70k gain expected and marking the strongest pace since August. The three-month average, meanwhile, surged to 137k, the fastest pace since May. Additionally, the unemployment rate unexpectedly ticked down from 4.2% to 4.1% in October, a two-month low. This surge in payrolls underscores the still positive and more than decent nature of labor market conditions; coupled with an ongoing acceleration in inflation, as well as a recent surge in domestic activity, the October employment data may reinforce the need for the Fed to take action sooner rather than later to reinstate price stability. Next week brings both the CPI and PPI reports, which will give us another opportunity to gauge the inflation situation.
_________________________________________________________________
Despite the recent rise in rates, SBA 504 loans remain very attractive, as they reduce the down payment on commercial real estate projects to as low as 10% and provide a 20- or 25-year fixed rate for up to 40% of the borrower's financing need.
For more information about the SBA 504 loan program, visit sedacogldc.org.
|