|
Happy Friday! It’s Casey from Howard Bailey Financial! Each week, I’ll send you my commentary on four financial-related resources that I think will be beneficial for you — plus a preview of my latest podcast episode.
Have questions? Send me a note!
| | |
#1
The Best Long-Term Investment
| | |
Spilled Coffee — Every year, Gallup asks Americans a simple question: What’s the best long-term investment? For the past 12 years, real estate has claimed the top spot, well ahead of gold, stocks, CDs, and cryptocurrency. On the surface, it makes sense. Homes often appreciate over time and their value isn’t posted like a stock ticker. But when you dig deeper, the math and maintenance can tell a different story.
Key Takeaways:
📌 Real estate feels safe, but it comes with hidden and ongoing expenses that can erode returns (think taxes, interest, insurance, repairs)
📌 Long-term stock market performance has consistently delivered higher results, despite its ups and downs (a simple $1 invested in the S&P 500 in 1950 would be worth over $300 today—no tinkering, just time)
Bottom Line: Your best investment reflects your values, risk tolerance, and lifestyle. There is no one-size-fits-all answer—it's about what matters most to you.
| | |
The Surplus Bucket Strategy:
A Way to Spend More Confidently in Retirement
| | |
If you're like many retirees we meet with, you may struggle to spend confidently in retirement, even when you've saved enough.
In this episode of the Retire With Purpose Podcast, we discuss:
📌 The dynamics of underspending in retirement
📌 How to apply the “Funded Status Metric” and “Surplus Bucket” to your income plan
📌 How to find an income strategy that aligns with your values
| |
| |
#2
What’s the Best Withdrawal Strategy in Retirement?
| | |
Of Dollars and Data — After a lifetime of disciplined saving, entering retirement should feel like crossing a finish line—but for many, it simply marks the beginning of a new, complex journey: turning your wealth into a reliable income stream. How do you pinpoint the path that best supports your lifestyle?
Here’s a breakdown of the top strategies:
📌 The 4% Rule: A straightforward, historically reliable method—withdraw 4% of your portfolio in the first year, then adjust annually for inflation. Simple, yes—but not adaptable to real-life market ups and downs.
📌 Flexible Spending Strategy: Spend more when the market is up, cut back when it’s down. This method lets you withdraw as much as 5.5% annually—if you’re comfortable trimming back discretionary spending in tough times.
📌 Guardrails Strategy: Adjust spending only when your portfolio hits certain upper or lower limits
📌 Bucket Strategy: Segment your savings into short-, mid-, and long-term buckets based on when you’ll need the money. This helps offer emotional peace of mind with spending goals.
📌 Never Touch the Principal: The most common real-life strategy—live off interest and income only. Simple, conservative, and popular among retirees who value peace of mind over maximizing every dollar.
Key Takeaways: Retirement isn’t just about math—it’s about meaning, lifestyle, and personal comfort. Whether you're a numbers person or someone who leads with intuition, you can find a withdrawal strategy that aligns with your values and gives you confidence for the years ahead.
| | |
#3
You Can’t Put the Investing Genie Back in the Bottle
| | |
The Italian Leather Sofa — What if the greatest financial freedom doesn’t come from beating the market, but from stepping away from it? For retirees and near-retirees, this reminder is especially poignant. You’ve done the hard work: saved, studied, and strategized. But now, the challenge is different—can you let go enough to truly live?
Key Insights from This Article to Remember:
📌 The more actively you manage your investments, the more emotional baggage you may carry
📌 Even passive investing requires active, ongoing decisions—and that’s okay
📌 True mental freedom comes not from disengagement, but from building a plan you trust, and knowing when to stop tweaking it
📌 Your identity isn’t your portfolio—and your peace of mind shouldn't depend on its daily performance
As You Navigate Retirement, Keep in Mind: Your financial plan is meant to support your life, not consume it.
| | |
#4
Self-Help is for Suckers
| | |
(Less) Lonely Money — What if everything you’ve been told about self-improvement—grit, willpower, solo success—wasn’t just misleading, but harmful? This powerful piece challenges the myth of the “self-made” person, making a compelling case for why lasting change, whether financial, personal, or emotional, doesn’t happen in isolation—it happens in connection.
Key Takeaways:
📌 Social support physically and emotionally reduces your stress and builds resilience
📌 Self-help often sells shame, not solutions—what you really need is connection
📌 In retirement and beyond, clarity and confidence are best built in relationships—not isolation.
As You Plan for Your Future, Remember: The strongest steps forward are the ones taken together.
| | | | |
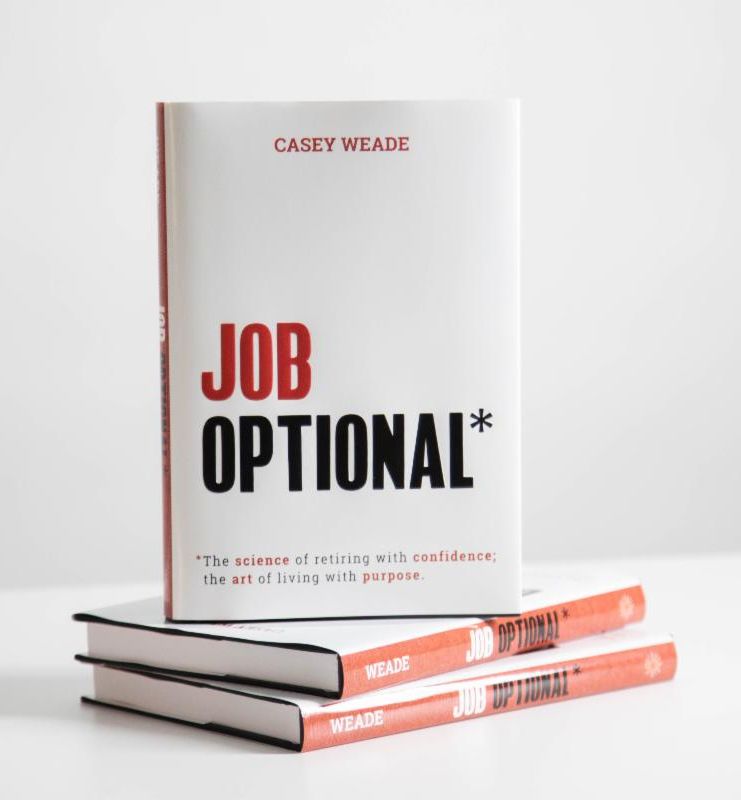
Ready to seriously start thinking about retirement? My best-selling book, Job Optional*, is a good jump-off point — it will teach you potential strategies designed to safeguard your financial future so you can focus on what matters most to you now.
| | On November 22, 2024, Howard Bailey Financial was named to Newsweek’s Top Financial Advisory Firms for 2025. No compensation was provided to Newsweek to obtain inclusion on the list, but there is a licensing fee to utilize the Newsweek logo in marketing materials. Criteria may not be directly related to the quality of investment advice provided. If you’re curious, the full methodology can be found on newsweek.com/rankings/americas-top-financial-advisory-firms-2025. | | |
Investment Advisory Services may be offered through Howard Bailey Securities, LLC, a registered investment adviser. Job Optional was a #1 Amazon best seller in Retirement Planning on 7/2/19, and a Wall Street Journal eBook Best Seller on 8/9/19. Working with Howard Bailey Securities, LLC, cannot guarantee investment success or that specific financial goals will be achieved. For more information on professional designations, visit finra.org/investors/professional-designations.
University of Notre Dame and University of Notre Dame Athletics (“Notre Dame") are not current clients of Howard Bailey Securities, LLC nor Howard Bailey Financial, Inc. Legends / JMI Rights Holders, on behalf of Notre Dame, was compensated for this endorsement, as such term is defined under SEC Rule 206(4)-1. For more information, please visit howardbailey.com/nddisclosure.
This has been provided for informational purposes only and is not intended as legal or investment advice or a recommendation of any particular security or strategy. The investment strategy and themes discussed herein may be unsuitable for investors depending on their specific investment objectives and financial situation. Information obtained from third-party sources is believed to be reliable though its accuracy is not guaranteed. Opinions expressed in this commentary reflect subjective judgments of the author based on conditions at the time of publication and are subject to change without notice. Past performance is not indicative of future results.
©2025 HOWARD BAILEY FINANCIAL, INC.
| | | | |