|
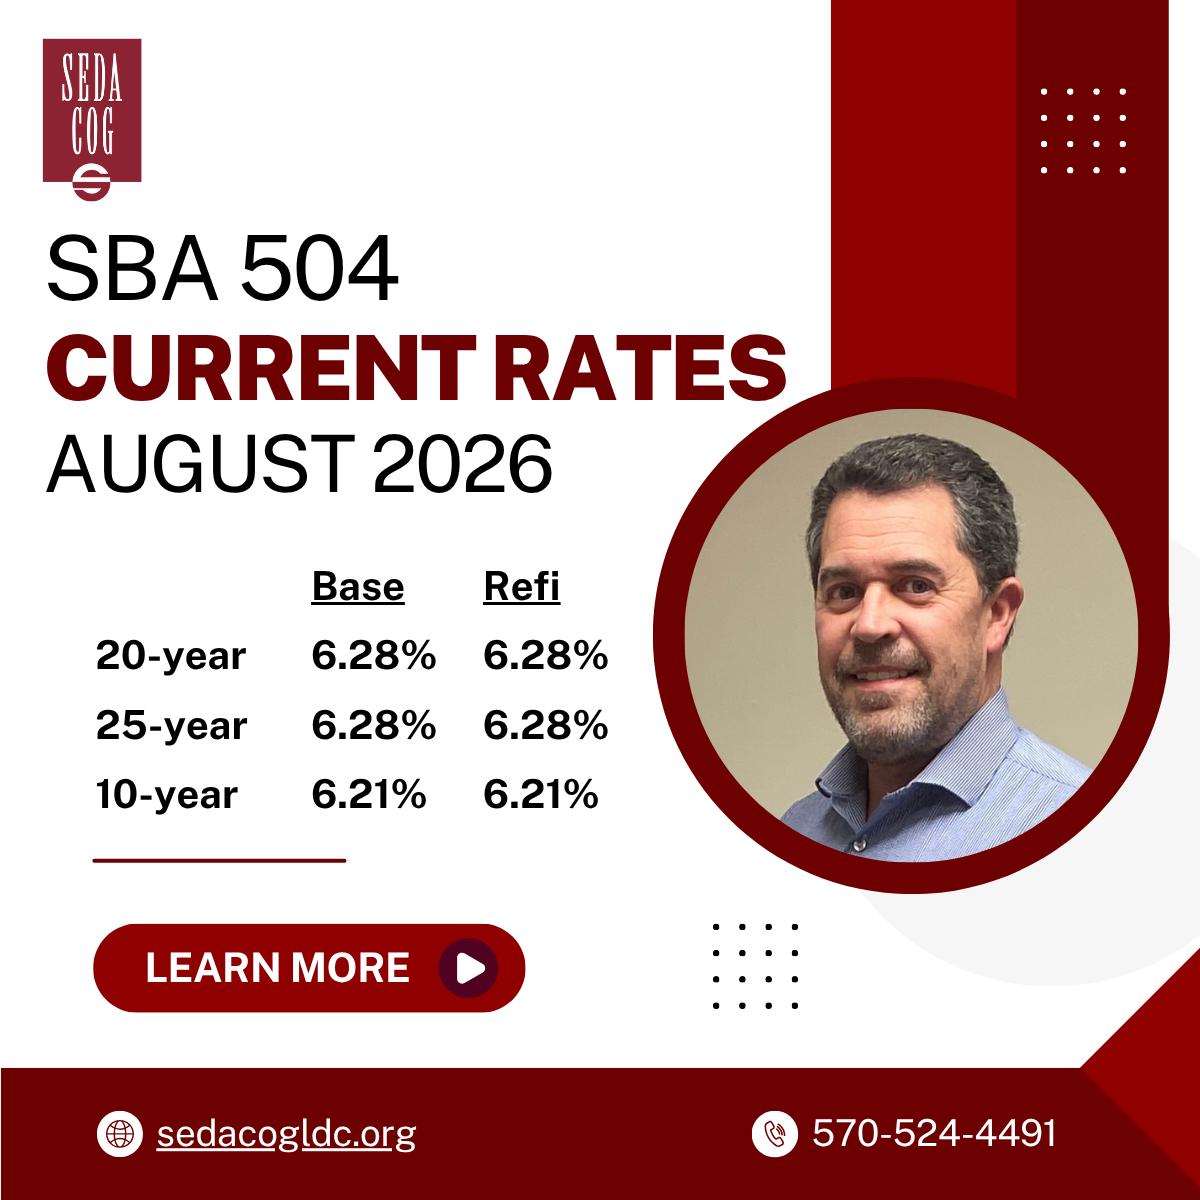
NADCO, the trade association for the nation's Certified Development Companies (CDCs), has released the SBA 504 fixed interest rates for August 2026. Eagle Compliance, the Fiscal Agent for the SBA 504 Loan Program, responsible for the marketing, pricing, and selling of the debentures sold to investors to fund the SBA 504 Loan Program, stated that August saw SBA interest rates inch higher due to a cautious and troubled bond market as well as Fed dissent over rates.
According to Eagle Compliance, a week before the SBA bond sales:
A “Good Family Fight”
Fed Chairman Kevin Warsh uses that phrase frequently when asked how he enjoys policy discussions to unfold, and in his second FOMC meeting as Chairman, he is getting what he asked for. Three Federal Reserve Bank presidents dissented on the 9-3 decision to hold rates steady at last week’s meeting, marking the first time since 2016 that three voters dissented for the same action. Two of those voters had supported a rate increase in June, but the third, Neal Kashkari, President of the Minneapolis Fed, had previously supported a rate cut as recently as March to support a jobs market that was weakening at the time. With inflation remaining above the Fed’s 2% target for the last five years, they believe they cannot wait for the impact of tariff increases and the Iranian conflict to be resolved before inflationary pressures ease.
The market now turns to the scheduled September 16 FOMC meeting where it assigns a 67% probability of a 25 bps rate hike. Chainman Warsh, in addition to creating five task forces to review how the Committee analyses data and manages communication, has also suggested that the Committee discuss reducing the number of its meetings from the current total of eight each year to six. The Fed’s governing law requires four meetings a year, and the current schedule of eight has been in effect since 1981. Fewer meetings would conform to his desire to reduce the amount of communication put forth from the Committee and would accomplish one of his objectives.
Like the CPI and PPI reports, last week’s Personal Consumption Expenditures report showed inflation cooling, though the resumption of hostilities is not encouraging for continued gains. Headline PCE improved to -0.1% from 0.4%, and the y/y rate improved to 3.7% from 4.1%, and this is a measure that Chairman Warsh hopes to no longer use by evaluating a trimmed mean deflator for PCE. As measured by the Federal Reserve Bank of Dallas, that rate for June was 2.2%, almost at the Committee’s target rate. Its calculation varies from the Bureau of Economic Analysis’ calculation by removing the most extreme price changes at both the high and low ends of the distribution, then computing a weighted average of the remaining components. If successful in making it the Committee’s preferred inflation gauge, the current reading of 2.2% is a compelling reason not to raise rates. Additional family fights will be interesting as the market has already done some of the work for the Fed, and based on how the Committee measures inflation, it remains to be seen how much more work is needed.
Reports
Other economic reports of interest were:
- Durable Goods report improved to 0.3% from -4.5% but was below the consensus of 1.7%.
- Q2 GDP declined to 1.5% from 2.1% and was below its 2.3% consensus.
Rates
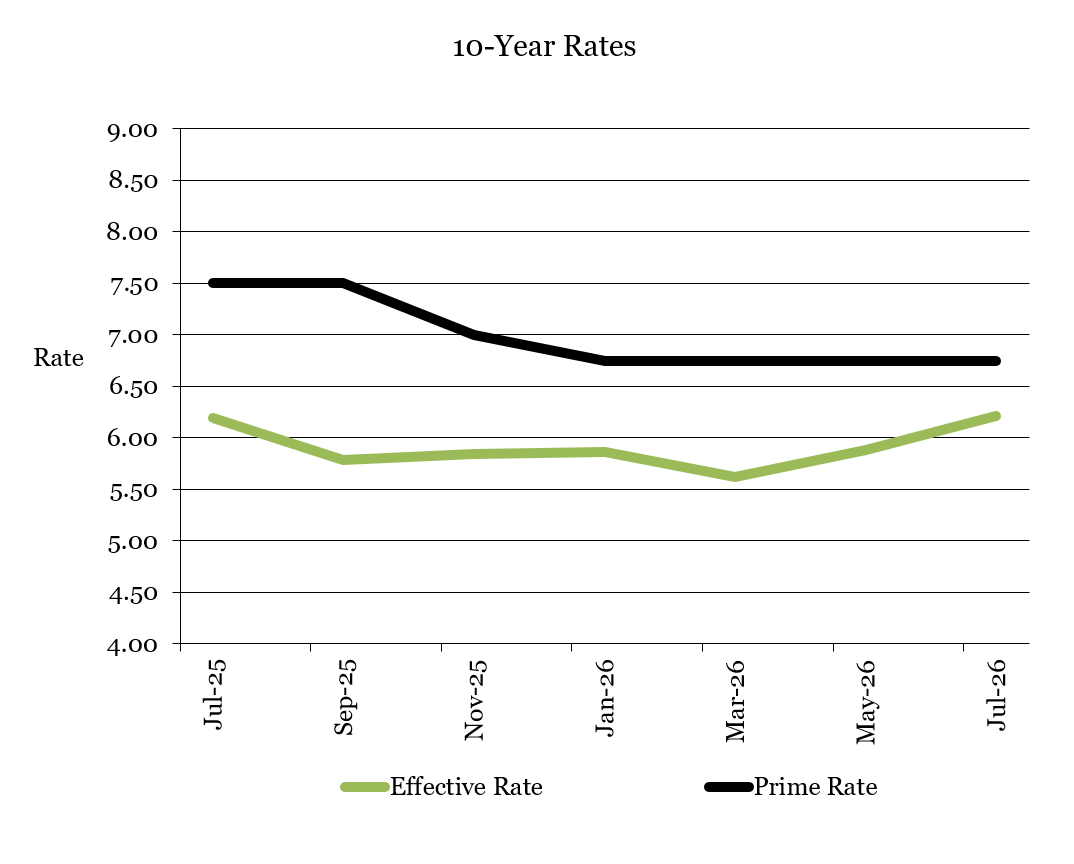
The bond markets were unhappy with Chairman Warsh’s Wednesday press conference as it pushed the 10-year yield to 4.74%, 18 bps higher than when the 504 program priced its July debentures. It also widened the spread between short-term and long-term rates, pushing that spread from +36 bps to +44 bps, as measured by the rates of the 10-year and 30-year Treasuries.
Following the bond sales, Eagle Compliance reported:
As we approached the August SBAP sale, the tone in the fixed income markets fell somewhere between cautious and troubled. The conflict in Iran had continued with little sign of meaningful/sustained progress toward resolution. As such, progress that had been made on the inflationary front was likely to be short-lived. The FOMC meeting had concluded last week, and although rates were left unchanged, there were three dissenting votes in favor of raising rates. Chairman Warsh also expressed his desire for fewer FOMC meetings, which, if accepted, would provide market participants with less information. He also remained in favor of changing the FOMC’s preferred inflation measure. These factors taken together made many believe that interest rates moving higher in the future was most likely.
Early last week, since the July SBAP pricing, U.S. Treasuries had increased in yield across the curve. The 10-Yr. UST yield was 4.73%, up 17 bps month over month, and the U.S. Treasury curve had steepened ever so mildly. As measured by the MOVE Index, UST volatility had increased 22.3% from 65.8 to 80.5 month over month. Comparable ACMBS issues had maintained spread levels month over month, but the MBS to UST basis had widened 5 bps, the 30-Year residential mortgage rate had increased 23 bps, and the MBS to UST OAS spread had also widened. With these factors in mind, it was decided that the suggested initial pricing spread on the 20-Year debenture would be +47 bps and for the 25-Year debenture it would be +50 bps, each to the 10-Yr. U.S. Treasury Note; both 2 bps wider than the July pricing. Preliminary guidance about the August debenture offerings suggested $19.1 million of a 20-Year and $503.6 million of a 25-Year. The week’s significant expected economic releases were very light, with the exception of the Non-Farm Payroll report due on Friday (post SBAP pricing), which was expected to improve to 72,000 from 57,000 in June, and the Unemployment Rate was expected to hold steady at 4.2%.
The morning of the SBAP announcement, market conditions displayed signs of improvement. The 10-Yr. UST yield had fallen to 4.64%, and equity markets had regained some upward momentum. Investor response to the SBAP $18.543 million 20-Year was immediate and very positive; for the SBAP $499.169 million 25-Year it was also good. The underwriters received significantly more investor orders on the 20-Year than debentures available; the 25-Year was also oversold, but to a lesser degree. Given the very good reception on the 20-Year, it was decided that its pricing spread could be narrowed by 3 bps. The 20-Year debenture was priced at a spread of +44 bps (lowest since February 2022 and 1 bp less than the July pricing); the 25-Year debenture was priced at a spread of +50 bps (2 bps wider than the July pricing). The August debenture rate for the 20-Year was 5.08%, and for the 25-Year it was 5.14% (7 bps and 10 bps higher, respectively, than the July pricing). The 25-Year rate is 21 bps under the program life average of 5.35%, and the spread over Treasury (+50) was 28 bps below its program life average of T+78.
Friday’s Non-Farm Payroll report unexpectedly dropped by 23k in July, marking the weakest pace since February. As mentioned above, payrolls were expected to rise 72k. Additionally, the three-month average declined from 77k to 20k in July, again marking the weakest pace since February. Household employment also dropped 87k in July, which follows a 507k drop in June; the labor force declined as well (down 264k) following June’s 720k plunge. Thus, the unemployment rate unexpectedly declined from 4.2% to 4.1% in July, the lowest level in a year. This data contradicts previous growth trends and is likely to support additional debate between FOMC participants. Early Friday, the news had little effect on the U.S. Treasury market, 10-Yr. note yields were quoted at 4.63%.
Next week will be relatively light from an economic release perspective, though it will also include the Treasury’s refunding of 3-Year, 10-Year, and 30-Year notes and bonds. The CPI will be released on Wednesday, and Thursday brings the PPI, both of which are July reports.
_________________________________________________________________
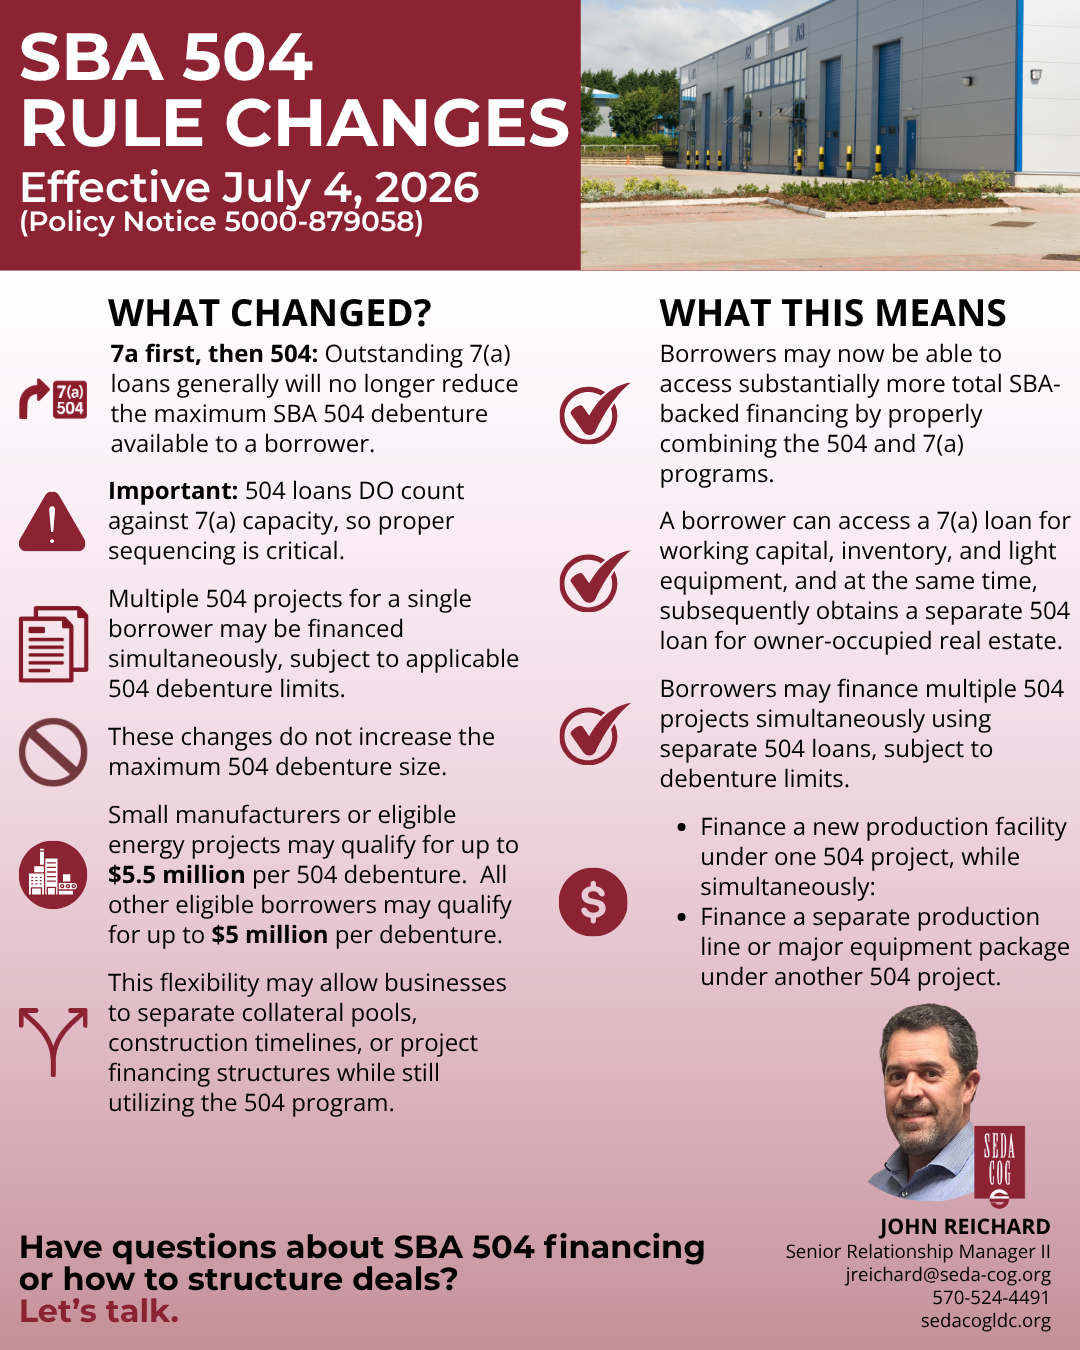
Despite the recent rising rates, SBA 504 loans continue to be very attractive, as it reduces the down payment on commercial real estate projects to as low as 10% and provide a 20 or 25-year fixed rate for up to 40% of the borrower's financing need.
For more information about the SBA 504 loan program, visit sedacogldc.org.
|