RETIREMENT SECURITY MATTERS
A forum for retirement innovation information sharing focused on
states, supporters, and service providers.
|
|
Greetings! welcome!
to Retirement Security Matters – where we talk about retirement readiness innovation by states, supporters, and service providers.
|
In this edition, in honor of the upcoming 4
th of July holiday, we are taking it easy and giving you some
light but useful reading:
|
- CITs, MEPs, PEPs and ESG – Oh My! A chat with Morningstar’s Aron Szapiro
- Updates from the States: Oregon, Illinois, Massachusetts, Maryland and Wisconsin
- And, Pix! for your enjoyment
|
View as Webpage. Comments or content suggestions?
Yes please!. Have something about your program you’d like to share? We are all ears.
|
Retirement Program Innovation - CITs - Why You May Care If You Don't Have Them
|
|
 |
Aron Szapiro, Director of Policy Research, Morningstar
|
|
|
|
Would CITs make your retirement savings program leaner and less expensive
– while preserving the integrity of your investment strategy and providing a high quality experience for your savers?
This week we talk with
Aron Szapiro
, who’s been studying this on your behalf. Aron is the director of policy research for Morningstar, responsible for developing research reports on policy matters, coordinating official responses to regulatory proposals, and providing investor-focused comments on policy issues to clients and the press. He also chairs Morningstar’s Public Policy Council. And he’s a bit of a man about town when it comes to the press. His research has been covered in
The New York Times,
The Wall Street Journal,
The Washington Post,
The Journal of Retirement,
and on
National Public Radio.
|
|
|
|
As usual, we covered a lot of ground. You’ll find a few highlights below, and our full conversation
here
.
Aron – first and foremost - what the heck is a “CIT” and why do we care about them?
That’s a great place to start! “CIT” stands for Collective Investment Trust. These are pooled investments that are exempt from the
Investment Company Act of 1940
. They tend to be registered through banks either at the state or federal level. And, from the perspective of the end investor they look an awful lot like any other pooled investment, including the registered open-ended mutual funds that investors have become so familiar with.
CITs have fewer regulatory requirements than mutual funds, however, and for these and other reasons they are a streamlined, simpler way to offer a pooled investment – and therefore generally a less expensive vehicle than mutual funds. That’s one reason we care about them.
I like a good bargain. Can anyone, and any plan, invest using CITs?
The short answer is “no.” In today’s environment these investments are generally only available to and through certain types of retirement plans – like 401(k)s, 401(a)s and 457(b) plans. It turns out that about 25% of 401(k) assets are now invested in CITs. The trend to use CITs is now moving from the large plans into the midsize plans. These are the vehicle of choice for a lot of 401(k) plans right now and I think more going forward.
That must make the other types of plans jealous.
Well, other plan types are interested in using CITs in order to gain those efficiency and price benefits. When we look at the US Department of Labor Form 5500 data, we see that a few 403(b) sponsors have tried to get CITs into their plans through various arrangements that seem pretty complex. But as a practical matter, very few are attempting to find ways to get around the general prohibition. However, there’s bipartisan thinking that having access to CITs could benefit these plans. And in fact, in March there was
a bill
introduced in Congress relating to the use of CITs in 403(b) plans.
[continued below]
|
|
State Facilitated Retirement Programs in Rollout and Study Mode
|
|
The implementing states are working away with Board meetings generally set for July and August. Over the past several weeks, many states have shared key updates and best practices thinking via NAST’s
Treasury Management Training Symposium (TMTS)
. Last week’s session on
Empowering Savers: Results and Updates on States’ Pioneering Retirement Programs
, moderated by Andrea Feirstein, covered some important ground:
|
|
Pew Charitable Trust’s
John Scott
reporting out highlights from this year’s OregonSaves Employer Survey. Upshot, most employers are satisfied to neutral about the program despite the fact that it requires something of them; 80% of employers find they get no or very few questions or concerns from employees, and 78% of employers report that they have no out of pocket expenses related to the program.
We’ll be covering this survey in more detail and with more color later this year.
|
|
Illinois Secure Choice’s
Courtney Eccles
provided current program stats ($25.7 million in assets and 65,267 funded accounts as of June 18). All three implementation waves are complete in Illinois; the program does have proposed legislation which would take its lower threshold down from 25 employees to a lower level. Ms. Eccles’ comments focused on the success Illinois is having with its Employer Onboarding Team and their simplified, single point of contact approach.
|
|
Massachusetts’ CORE Plan’s
David Lynch
hit the highlights of this MEP program, offered to nonprofit employers with 20 or fewer employees. Launched in October of 2017, the program has over $5.5 million in assets from 80 committed or funded employers covering 600 eligible employees. Massachusetts has legislation proposing the extension of this program to more employers in the state.
|
|
The
MarylandSaves
program is completing its interviews shortly following closure of its investments and program administration RFP on
April 30
. The program is aiming for a board recommendation and decision/s in July
|
|
Wisconsin’s
(workforce 2.6 million) retirement security task force has met three times this year – in January, April, and June. Information and perspectives considered include those of small business owners – through surveys and direct testimony; a focus on how people save for retirement, including behavorial scientists’ insights and individual testimony; and considerations in the COVID-19 environment including the impact of racial inequality and retirement security differences by race. There’s too much to cover here, but we’re dedicating our next edition to a focus on Wisconsin and what they’re learning.
Please bookmark us two weeks from now.
|
|
. . .
CITs - Why you may care,
continued from above
|
|
So, given that the regulatory requirements are lighter – maybe “much” lighter – would you say CITs as a vehicle are inherently more risky than an equivalent 40 Act mutual fund?
Well we think they could be pretty useful – if used effectively.
In our recent paper
, we get into a bit more detail about the characteristics of CITs, how they could be used by 403(b) plans to improve outcomes for savers, and we suggest some guardrails that aren’t part of the current legislation.
We know you’ve been really busy. Tell us about some of the other things you're focusing on at Morningstar.
Interestingly, we are in the middle of three regulatory efforts with 30 day comment periods at the moment.
The US Department of Labor (DOL) has a
request for information
on the extent to which pooled employer plans (PEPs), which will go live on January 1, 2021, should be able to skirt current prohibited transactions regulations.
Related to PEPs – the new pooled employer plans authorized by the SECURE Act, we have a paper coming out shortly that looks at multiple employer plans asking, what do we see in the data here? And what we find is really interesting. I’ll bottom line it. There's a lot of promise for pooled employer plans. As they scale, fees come down. We’re publishing on July 23 – stay tuned and read for yourself.
And as you know, on June 23 the DOL introduced a
proposed rule
on ESG (investing based on Environment, Social and Governance criteria) and retirement plans. We see this space not as a hippie dippie, tree hugger kind of thing, but more mainstream because those risks really drive the ability of an entity to continue to generate profit or cash flows for investors. So, we’re still framing this one up, but we expect it to be a major feature of our team's work this summer.
And, how is the pandemic treating you?
Well we’ve learned that when you are parents looking after a four-year-old and a one-year-old while you are working at home, it turns out you're bad at both things! We’ve had some funny Zoom blooper moments together which I’m sure your readers can relate to.
Thank you Aron Szapiro!
This is an excerpt from a longer conversation. For the rest of our chat, and more detail,
check this out
. And if you’re interested in talking with Aron yourself, you can reach him
here
.
|
|
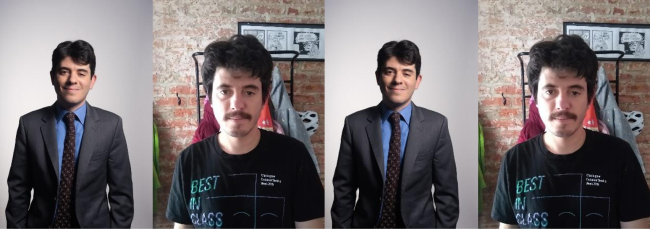
Let’s kick this off with a before and after. Before – after – before – after. Love your new look, Aron – expecting to see a drumkit somewhere nearby! #pandemia
|
|
|
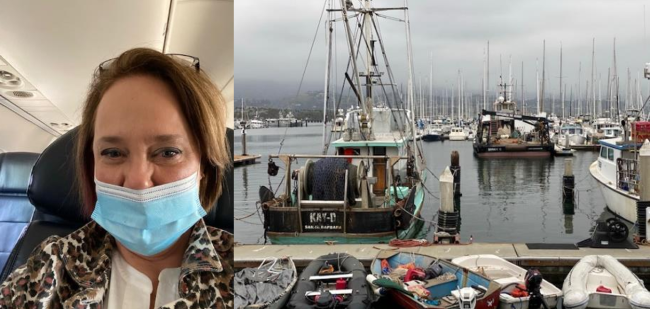
We sneak off on a short flight, safely, just to see what it’s like and to remind ourselves that the ocean still exists. Yes, if you can see your nostrils, #youredoingitwrong. We fixed that.
|
|
|
|
|
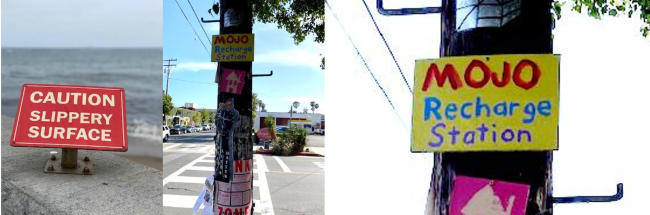
Wouldn’t it be great if you always got this warning when headed into tricky territory. And what if you could find one of these power supplies on every street corner?
|
|
|
|
|
When you get back home, it’s always nice if someone missed you.
|
|
|
|
♥
OK, that's a wrap.
If you like this piece, please stick with us. We’ll be back in about two weeks. If you don’t like it, please unsubscribe. Comments for us? Please
let us know. Want your own subscription? Request one
here. All information shared is from public sources or used with express permission.
|
|
If you want a great source of broad-based, consumer-focused retirement news, Jeffrey H. Snyder’s
The Morning Pulse
is your ticket. You can
subscribe here
.
|
|
|
|
|
|
|