|
Tariffs have tightened, untightened, and will continue to evolve as the Trump administration navigates global negotiations.
Whew... There's still A LOT to unpack here, so hold on for the roller coaster ride.
A little background on where all of this started and what it means. Tariffs are duties placed on foreign goods, paid by domestic importers to Customs and Border Protection at ports of entry. President Trump introduced tariffs on select Chinese goods in his first term back in 2018, which President Joe Biden later maintained, along with duties on steel and aluminum from most countries. In February of 2025, Trump reinstated tariffs—10% more on Chinese imports, bringing them to 35%, and 25% on Mexican and Canadian goods (except for oil, taxed at 10%). From there, it has been an ever-changing environment with tariffs going up and down from month to month based upon negotiations with other nations.
Tariff update for May 2026
A lot has happened in the courts over the last 90 days. Here is where things stand as of May 2026 and what it means for you.
The Section 122 Ruling
On May 7th, the U.S. Court of International Trade issued a 2-1 ruling that the Trump administration's 10% across-the-board global tariff, imposed under Section 122 of the Trade Act of 1974, was unlawful. The court found that the administration's justification did not meet the statutory requirement of a "large and serious balance-of-payments deficit." Trade deficits, the court said, are not the same thing as balance-of-payments deficits. That is an important legal distinction, and the court drew a hard line on it.
The ruling currently applies only to the named plaintiffs. It does not establish a nationwide injunction. The administration is expected to appeal. And critically, Section 122 tariffs were already scheduled to expire on July 24, 2026, making this more of a legal signal than a market-moving event.
That signal matters. This is the second major court rebuke of broad executive tariff authority in 2026. The Supreme Court struck down IEEPA tariffs in February. The Court of International Trade struck down Section 122 tariffs in May. The courts are drawing clear lines. The power to tax is Congress's power. Period.
Section 232
None of the above pertains to Section 232, which governs tariffs on steel, aluminum, and copper. It was written specifically to authorize tariff action on national security grounds. It has survived every legal challenge to date and remains fully in effect.
The April 6th framework remains the operative structure:
- Raw mill products, plate, sheet, tube, pipe, and fittings at 50% on the full customs value.
- Derivative articles substantially made of steel, aluminum, or copper at 25% on full customs value.
- Certain metal-intensive industrial equipment at a temporary 15% through December 31, 2027.
- Products made with 100% U.S.-origin metal at 10%.
- Products with 15% or less metal content by weight are not subject to Section 232 tariffs.
How Does This Affect Imported Pressure Vessels and Heat Exchangers?
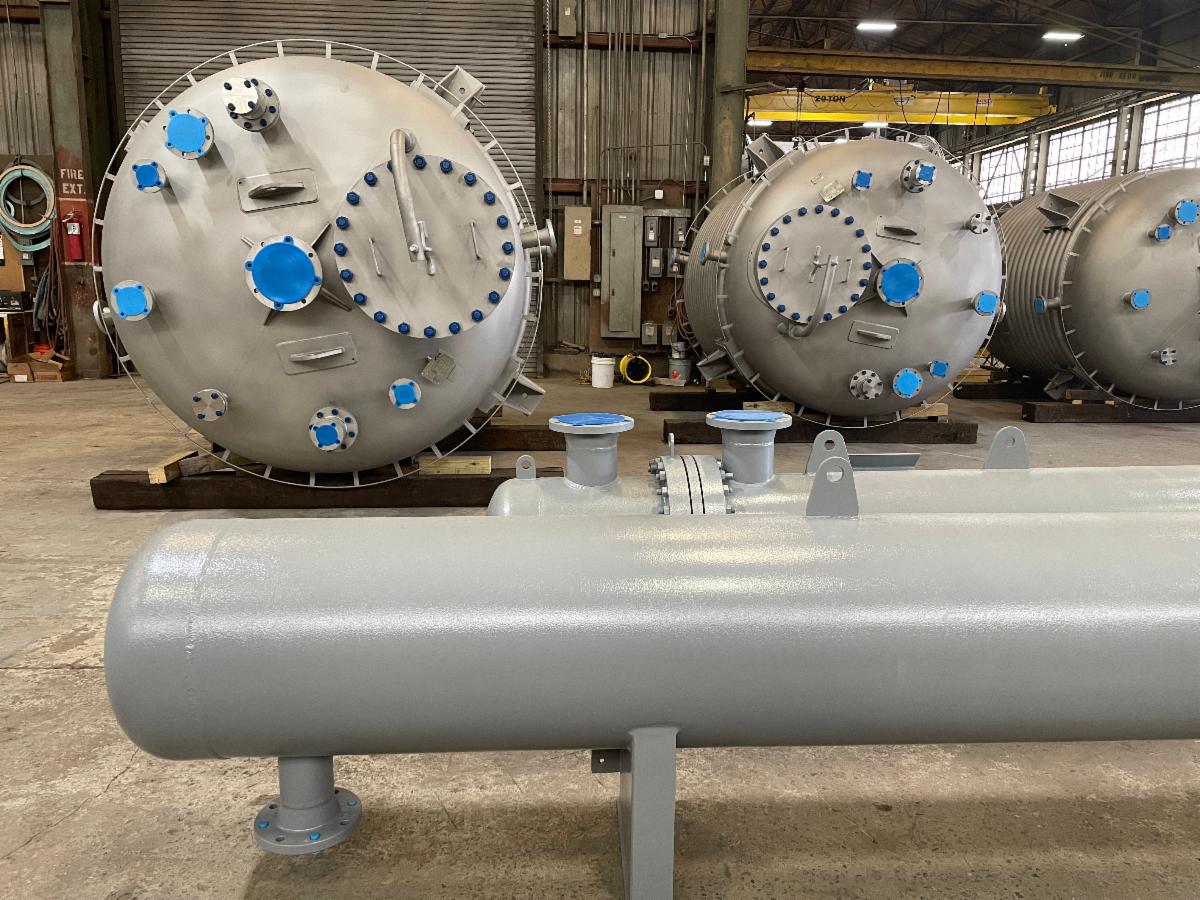
Per our understanding, pressure vessels and heat exchangers are fabricated equipment classified under HTS Chapter 84 (industrial machinery), not Chapters 72 through 76 (raw steel mill products). This distinction matters significantly under the April 6th Section 232 overhaul.
For aluminum heat exchangers, the picture is clear. HTS subheadings 8419.50.10 and 8419.50.50 are explicitly listed as aluminum derivative articles in the April 6th proclamation, meaning imported finished aluminum heat exchangers are subject to a 25% tariff on the full customs value of the unit, not just the metal content. On a $500,000 imported aluminum heat exchanger, the tariff base is the full $500,000.
For stainless steel, alloy, and carbon steel heat exchangers, and for pressure vessels of any material, the situation is less settled. These products typically classify under HTS 8419.50.50 and 8419.89, respectively, neither of which appears in the steel derivatives section of the April 6th annexes. This creates a genuine gray area. Imported finished steel heat exchangers and pressure vessels may not currently be explicitly covered by the Section 232 derivative tariff on the finished unit.
It is also worth noting what the Annex language does and does not say about tanks and vessels under Chapter 73. Two codes are listed under Annex I-A at the 50% rate. HTS 7309.00.00 covers iron or steel reservoirs, tanks, vats, and similar containers with a capacity exceeding 300 liters, but only those not fitted with mechanical or thermal equipment. HTS 7311.00.00 covers iron or steel containers for compressed or liquefied gas.
While these codes may appear to cover pressure vessels at first glance, the critical limitation in 7309 is that phrase: "not fitted with mechanical or thermal equipment." A fabricated ASME pressure vessel with nozzles, instrumentation, internals, and process connections would almost certainly not qualify under that language. Neither code uses the word "vessel" at all. A purpose-engineered ASME Code vessel is fundamentally different from a simple storage tank or container. The customs classification of fabricated pressure equipment under Chapter 73 versus Chapter 84 is a fact-specific determination, and Chapter 84 typically governs process equipment of this nature.
What is unambiguous for all product types is that the raw material inputs (i.e. stainless plate, carbon steel plate, seamless and welded tubing, and pipe fittings) are covered at the full 50% rate under Annex I-A, regardless of how the finished equipment is ultimately classified.
One Process Change Worth Noting.
The petition-based inclusion process that previously allowed domestic manufacturers and trade associations to formally request that specific HTS codes be added to Section 232 scope has been terminated. Going forward, Commerce and USTR will adjust product coverage on a rolling basis at their own discretion. There is no formal submission window anymore.
That means if you believe imported finished pressure vessels and heat exchangers should be explicitly covered under Section 232 derivative tariffs, the path forward is direct engagement with your elected officials. Not a petition. A phone call. A meeting. A letter.
As pressure vessel and heat exchanger fabricators, we need to continue pushing for protection to be in place for manufacturers of steel products, not just for domestic suppliers of raw material. We encourage every customer and partner in this industry to make that contact.
What This Means for Ward.
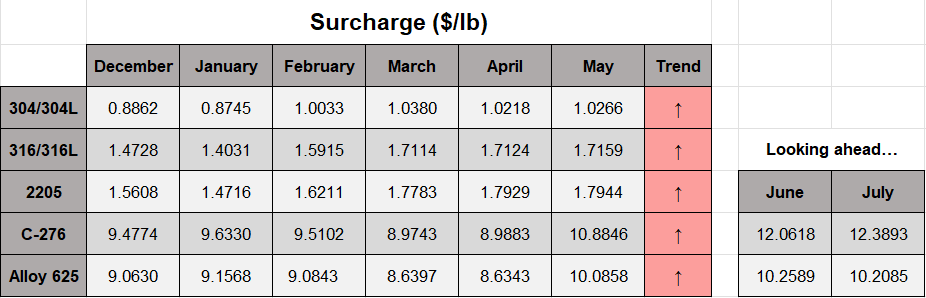
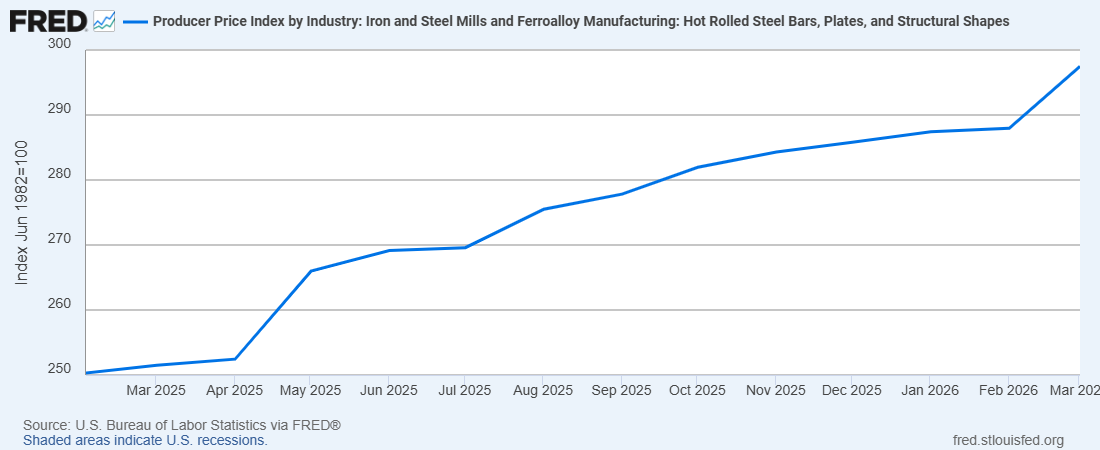
Nothing changes in our cost structure today. We purchase 80 to 90 percent of our material domestically depending on the project. Our total material spend has increased approximately 10 to 20 percent since Section 232 tariffs were enacted, resulting in a 5 to 15 percent overall unit price increase after labor. We are absorbing what we can. We are passing through what we must. And we will continue to monitor the evolving situation and update you each month on the latest developments.
|