|
|
|
IN THIS ISSUE
UNDUE INFLUENCE?
REFRAMING THE
START DATE DECISION
EXTENSION OF TIME
FOR QDOT NOTIFICATION
ARTICLES OF INTEREST
|
| |
Protecting Against Financial Exploitation and Poor Financial Decisions
As we enter retirement, our financial concerns often change. During our working years, the focus usually is on accumulating wealth, saving for retirement, and building financial security. Later in life, the focus increasingly becomes protecting what we have accumulated and making sure it continues to serve us--and our heirs according to our wishes.
A concern that deserves greater attention is financial exploitation. Financial exploitation can take many forms. It may involve an outside scammer, an unscrupulous individual, or even someone the family knows and trusts. But exploitation is not always intentional. As we age, circumstances can arise in which an otherwise responsible person becomes vulnerable to making poor financial decisions.
Financial vulnerability does not necessarily mean someone is incapable of managing his or her affairs. A person may remain fully capable of handling everyday finances while becoming more susceptible to a sophisticated investment opportunity, an aggressive sales pitch, a fraudulent request for money, or pressure from someone close to them.
Poor financial decisions can also result from circumstances that have nothing to do with fraud. A significant market decline, an unexpected medical expense, an overly generous gift to a family member, or an ill-advised investment can have lasting consequences.
For individuals who have spent decades building their financial security, protecting those assets deserves the same thoughtful attention as accumulating them.
One of the most effective ways to address these risks is to plan before a problem arises. Estate planning documents can establish who is authorized to act if you become unable to manage financial affairs. As we have written many times before, Trusts can provide another layer of oversight and continuity, particularly when assets are intended to benefit heirs over an extended period.
The choice of who will have these responsibilities is equally important. A family member may be the right person in some circumstances. In others, an independent fiduciary may provide valuable perspective and continuity. A corporate trustee has no personal family relationship with the beneficiaries and is obligated to administer the trust according to its terms and applicable fiduciary standards.
There is another important consideration: sometimes the person managing the money needs to be willing to say "no." Family members can understandably find it difficult to refuse a request from a parent, child, or sibling. An independent fiduciary can provide an objective voice when a financial decision may not be consistent with the individual's long-term interests or the purposes of the trust.
That does not mean taking control away from the individual. Proper planning is about preserving appropriate independence while establishing safeguards for circumstances in which additional oversight may be necessary.
Protecting wealth in retirement requires more than investment management. It also means establishing safeguards against financial exploitation and ensuring that important financial decisions remain aligned with an individual's long-term interests.
For families, this can be particularly important when substantial assets are involved. Clear fiduciary arrangements can provide accountability and continuity while creating an additional layer of oversight when circumstances make someone more vulnerable to financial pressure, manipulation, or poor decision-making.
At Garden State Trust Company, we believe thoughtful fiduciary planning can help families protect not only the wealth they have accumulated, but also the intentions behind that wealth. Establishing appropriate oversight before concerns arise can provide an important measure of protection against financial exploitation while helping ensure that assets remain available for the purposes for which they were intended.
| | MONTHLY QUESTION & ANSWER | | |
Q. Can you explain to me in simple terms what an Investment Policy Statement is and why it is important.
A. An Investment Policy Statement (IPS) is a written plan that explains how your investments should be managed. It outlines your financial goals, how much investment risk you are comfortable taking, the types of investments that may be used, and how your portfolio should be monitored.
Why is it important? An IPS provides a clear roadmap for making investment decisions. It helps to keep your investments aligned with your goals and provides consistency during changing market conditions. Most importantly, it can help prevent emotional or impulsive decisions when markets decline or become unusually volatile. An IPS helps keep everyone focused on the long-term plan.
| | HAVE A QUESTION ON TRUSTS, WILLS, OR INVESTMENT MANAGEMENT? | | For general informational purposes only. This information does not constitute legal advice. | | |
Do you know when you should start your Social Security benefits? Did you know that for an estimated 57% of beneficiaries the best choice would be to delay benefits to age 70, but only 10% of this group does so? Learn more in this month's Informational Article, Reframing the Start Date Decision.
Another one of this month's informational articles, Undue Influence, highlights a recent Michigan court decision and the importance of having a licensed attorney prepare a Will.
Each year as we approach Halloween, I share the following with you because of its importance.
Did you know that child pedestrian injuries are more likely on Halloween than on any other night of the year? Help keep Halloween fun and safe for your family with these tips from healthychildren.org.
-
Always accompany young children on their neighborhood rounds. If trick-or-treating doesn't start until after dark where you live, consider checking with your town or park district for Halloween activities offered earlier in the day. Evenings from 6 p.m. to 9 p.m. are the riskiest times of day for child pedestrians.
-
If your older children are trick-or-treating alone, plan and review the route that is acceptable to you. Agree on a specific time when they should return home and get flashlights with batteries for everyone.
-
Talk with kids about the risk of distracted walking. This includes text messaging, talking on or looking at the mobile phone and listening to music.
-
Cross the street as a group in established crosswalks. Most (62%) child pedestrian traffic fatalities occurred mid-block, rather than at intersections. Make sure kids know not to cross the street between parked cars or out of driveways or alleys.
-
Don't assume cars will stop just because pedestrians have the right of way. Motorists may have trouble seeing trick-or-treaters.
-
Stay on well-lit streets and always use the sidewalk. If no sidewalk is available, walk at the far edge of the roadway facing traffic. Only go to homes with a porch light on and, ideally, a well-lit pathway.
Have a happy and safe Halloween!
| | |
Lawrence executed his will on July 22, 2016, dividing his estate between his sisters, Gloria and Frances. Gloria was named his guardian and conservator, and she was joint on his bank accounts.
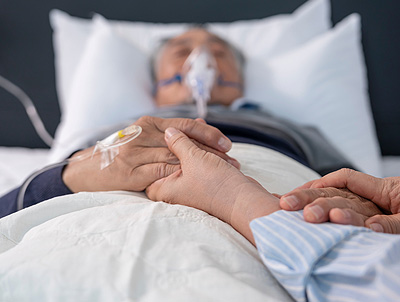
In May 2022 Lawrence was diagnosed and hospitalized with cancer. While he was in the hospital, Gloria removed funds from the bank account. She testified that it was at Lawrence's direction, but when Lawrence became angry about it the funds were replaced.
Frances' daughter, Latricia (Lawrence's niece), was in the hospital room when he talked to the bank about the joint account. She testified that Lawrence told her that he needed to give someone a power of attorney to have Gloria removed from the account. Latricia obtained a power of attorney form, had Lawrence execute it, and used the power of attorney to open a new account with her name on it. All the funds from the joint account were transferred to the new account.
On June 16, 2022, Lawrence was discharged from the hospital and returned home. Latricia and her husband moved in with him, and she became a 24-hour care provider. On June 22, 2022, Lawrence executed a quit-claim deed for his home, adding Latricia to the deed as a joint tenant with a right of survivorship. On June 25, 2022, Lawrence executed a new will leaving his entire estate to Latricia, and naming her as the executor. The will had been obtained by Latricia with a computer and was witnessed by Latricia's husband. The deed and new will were not disclosed to other family members.
In July 2022, Lawrence told Frances that he was leaving the house to her son, his nephew, Willie. When Latricia heard this news she became very upset, claiming Frances must have misheard. Latricia testified that Lawrence told her she was to rent the house to Willie, not that Willie would inherit it.
Lawrence died July 28, 2022, about two months after the cancer diagnosis, a month after the new will was executed.
Latricia offered the 2022 will for probate, and Gloria and Frances objected that it was obtained through undue influence. They argued for probate of the 2016 will.
In Michigan, where these events happened, undue influence may be inferred if there is a fiduciary relationship between the grantor and the beneficiary, the fiduciary gains a benefit from the exercise of fiduciary power, and the fiduciary had an opportunity to influence the grantor's decision. Latricia was a fiduciary under the power of appointment, she benefitted from the will, and she was with Lawrence around the clock and so had the opportunity. These factors create the presumption of undue influence, but Latricia had the chance to rebut that presumption with her own evidence. Unfortunately, her only evidence was her own testimony and that of her husband, which the trial court found not credible. Under those circumstances, and considering that Latricia and her husband had been in financial distress and only took any interest in Lawrence's welfare after the cancer diagnosis, the trial court held that the 2016 will controls the distribution of the estate. The Michigan appeals court affirmed.
Had Latricia employed the services of an estate planning attorney to prepare the new will and document carefully the reasons for the changes in his estate plan, there might have been a different result.
(October 2026)
© 2026 M.A. Co. All rights reserved.
| | Reframing the Start Date Decision | | |
When should you start your Social Security benefits? This is a crucial decision that will have an effect throughout your retirement. According to some studies, only 4% of retirees make a choice that maximizes their wealth. For an estimated 57% of beneficiaries the best choice would be to delay benefits to age 70, but only 10% of this group does so.
Why do so many people tend to choose an earlier than optimum start date? Perhaps it's because they are anxious to start cashing in on the benefits they have been paying taxes for throughout their working lives, they don't want to lose out on any of their benefits. That point of view overestimates the risk of death early in retirement, and fails to appreciate the longevity risks retirees face.
The decision may be reframed by the Claiming Age Clarity Act, which has passed both houses of Congress. Under the new legislation:
"Early eligibility age" becomes "minimum benefit age." The positive feel of "eligibility" is replaced by the negative connotation of "minimum." The age for minimum benefits, 62, is not changed.
"Full retirement age" and "Normal retirement age" are replaced by "Standard benefit age."
"Delayed retirement age" becomes "Maximum benefit age," once again reframing the effect of delay in a more positive light. Who doesn't want to maximize their benefits?
The legislation enjoyed bipartisan support, as well as from advocates for retirees such as AARP. Whether the reframing of the timing decision for Social Security benefits will influence more people to delay their benefits remains to be seen. The larger question, in most cases, is how prepared the individual is with retirement income from other sources.
(October 2026)
© 2026 M.A. Co. All rights reserved.
| | Extension of Time for QDOT Notification | | |
In general, a married couple is treated as a single economic unit for federal estate and gift tax purposes. The marital deduction for transfers between spouses has no dollar limit, for the most part.
An exception comes into play when one of the spouses is not an American citizen. When the limits on the marital deduction were removed some Congressmen were concerned that a fortune left to a noncitizen spouse might be taken out of the country, removed from the reach of the IRS and the federal estate tax. Accordingly, for a noncitizen spouse a bequest must be in the form of a Qualified Domestic Trust (QDOT) with a U.S.-based trustee. As such, the QDOT has additional transfer tax exposures. However, those exposures may be eliminated if the beneficiary spouse later becomes a U.S. citizen.
In a recent private letter ruling from the IRS, Spouse was the beneficiary of a QDOT and Bank A was the trustee. Spouse then achieved U.S. citizenship, but did not inform the trustee of the changed status. Soon after, Bank A was acquired by Bank B. Neither Bank A nor Bank B informed the IRS about Spouse's new status by filing Form 706-QDT within the required time period.
Much later the oversight was discovered, and so Bank B asked for an extension of time to file the required Form. The IRS determined that the taxpayers had acted reasonably and in good faith, and an extension of 120 days was granted.
(October 2026)
© 2026 M.A. Co. All rights reserved.
| | |
WALL - MAIN OFFICE
732-255-5000
SOUTH JERSEY / PHILADELPHIA REGION
856-281-1300
| | |
LEBANON REGION
908-287-7188
LINWOOD / SOUTH JERSEY REGION
856-281-1300
| | Because of the rapidly changing nature of tax, legal or accounting rules and our reliance on outside sources, Garden State Trust Company makes no warranty or guarantee of the accuracy or reliability of information contained herein nor do we take responsibility for any decision made or action taken by you in reliance upon information provided here or at other sites to which we link. ©2026. All rights reserved. | | | | |