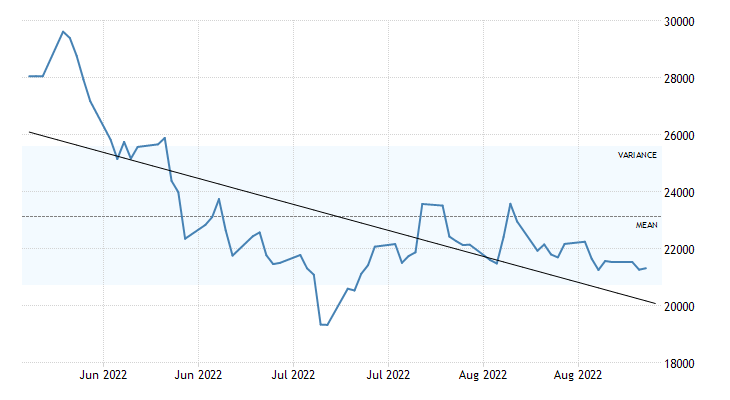
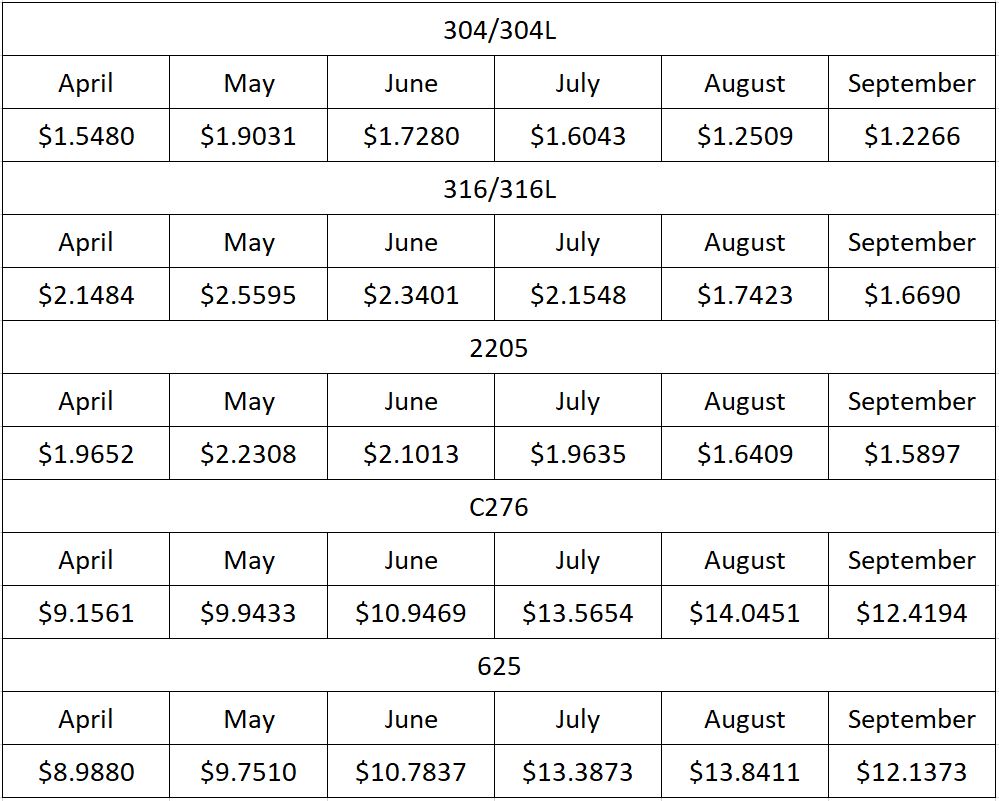
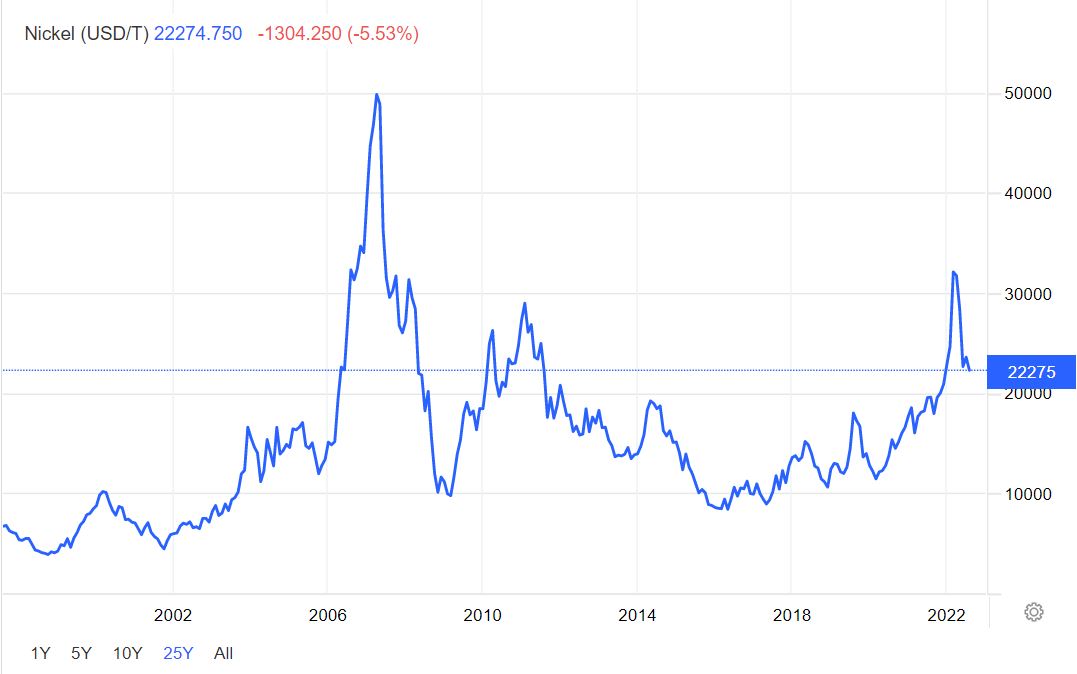
Nickel activity was largely uneventful in August, with an average value of $9.98/lb. The commodity started the month at $10.73/lb. yet spent most days below the $10/lb. threshold, ultimately closing the month at $9.69/lb. The stainless steel production outlook is somewhat cloudy for the balance of 2022, which should keep values in the $10/lb. range or perhaps slightly lower.
Domestic steel mills stayed mum in August, with no increase or decrease. Barring some unforeseen events, look for prices to stay stable in the near term as supply and demand approach equilibrium.
Commodity stainless and Duplex plate deliveries remain in the 8 to 12 week range, while Nickel alloy plates range from 11 to 26 weeks. Carbon Steel plate mill deliveries reside in the 6 to 10 week delivery range.
Welded tubing –Stainless strip supply has plateaued, keeping smaller quantity deliveries in the 10 to 16 week range, with larger quantity orders still in the window of 18 to 25 weeks. Carbon steel tubing deliveries have lead times ranging anywhere from 12 to 20 weeks when strip is available. Welded nickel alloy tubing ranges from 16 to 26 weeks, with some cases of 30 week deliveries.
Seamless tubing - Current schedules reflect 8 to 22 weeks or more for carbon steel (26 to 30 weeks for Western European carbon seamless) and 8 to 30 weeks for stainless. Seamless nickel tubing is being offered at the 10 to 12 week delivery window so long as hollows are in stock. If hollows are not readily available, anticipate deliveries of seamless nickel tubing in the 20 to 32 week timeframe.
The metal market is still in a tremendous state of uncertainty and price volatility, so please don't hesitate to reach out if you have any questions.