GDP Growth Much Stronger Than Expected |
|
Stocks were down at least 2% for the second consecutive week as a wave of earnings reports did not live up to expectations. The S&P 500 lost 2.53% and finished at the lowest levels since April. In fact, the S&P 500 closed Friday in correction territory, down 10.6% from its recent highs. A correction is known as a pullback of at least 10% from recent highs. Meanwhile, the NASDAQ, which has a higher weighting from growth stocks, has seen a 12% pullback as earnings reports have so far been underwhelming, with guidance that has been mostly cautious. Companies that have reported better than expected results are seeing their stock rewarded in a smaller way than in the past, while companies that have reported less than expected results are getting punished more than usual.
Microsoft, Alphabet (Google), Amazon, and Meta (Facebook) all reported their quarterly results last week and Microsoft was the only one that saw its shares higher afterward. Cloud business was the focus for the first three, with Microsoft seeing an acceleration in revenues in that segment, while cloud revenue growth at Alphabet and Amazon underwhelmed, despite their core businesses (ad revenue) remaining strong. Meta was down on much better than expected results because it said it was seeing “softer” advertising trends so far in the fourth quarter, citing geopolitical events.
Volatility wasn’t just seen in stocks, it continued in the bond market as well. Treasury yields on the 10-year note moved over 5% again early in the week. Yields finished nine basis points lower to 4.84% though, after hedge fund manager Bill Ackman said he closed his short position ("shorting" is when an investors bets a security will lose value), saying there is “too much risk in the world to remain short bonds,” adding that the economy is slowing faster than the data suggests. Remember, bond prices and interest rates are negatively correlated – a downward move in rates pushes prices higher.
Bonds look more attractive and we could make the case an overweight position is making more sense. First, they are now providing attractive yields with interest rates higher. They have sold off significantly over the past three years, in fact seeing the worst three year performance ever. In addition, if the economy slows, there is a high probability rates would be cut (to stimulate growth) and that would lead to rising bond prices. In a recessionary environment investors typically prefer bonds over stocks, leading to increased demand and higher prices.
As we mentioned last week, anecdotal evidence is painting a different picture on the economy than actual economic data. This was seen again last week with the third quarter GDP report. According to the Bureau of Economic Analysis, GDP (gross domestic product – which is typically associate with economic growth) increased at an annualized pace of 4.9% in the three-month period from July through September. Aside from the pandemic quarters, this was the strongest growth rate since 2014.
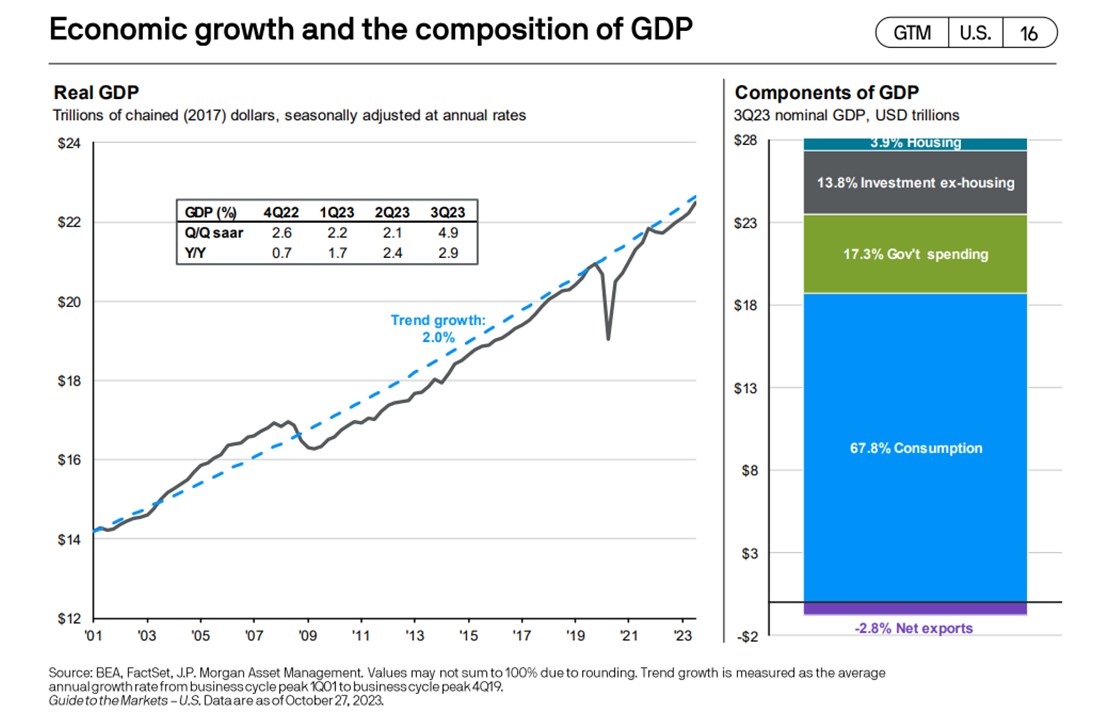
The U.S. is a consumer and services driven economy and as a result consumer spending makes up roughly 70% of GDP. Consumer spending increased 4.0% in the quarter, due to spending on goods bouncing back and increasing 4.8% while spending on services rose 3.6%. The strong consumer spending contributed 2.7% to the headline 4.9% GDP reading. Government spending has been high since the pandemic and a 4.6% increase in government spending contributed 0.8% to GDP. Meanwhile, businesses did a lot of restocking, particularly automakers ahead of the UAW strike, with the growth in inventories contributing 1.3% to GDP. Business investment and housing investment contributed a combined 0.2%. Finally, the change in the deficit detracted 0.1% from GDP as imports grew more than exports (higher exports contribute to GDP as that is what the U.S. produces).
Those are the categories that make up our economy (and GDP), as shown on the right half of the chart below, and is how we got to 4.9% (annualized) growth in the quarter. The left half of the chart shows that GDP is now in line with its long-term trend line.
One of the better measures of core economic growth, final sales to domestic purchasers, grew a still very solid 3.5%, driven by strength in consumer spending.
|
|
Looking ahead, it will be another very important week for the markets. The main event is the Federal Reserve’s FOMC meeting. The Committee concludes its meeting Wednesday with a policy announcement at 2:00. No change in rates are expected, but we expect Chairman Powell to lean slightly more hawkish in his post-meeting press conference, due to the recent streak of strong economic data, which could put additional upward pressure on Treasury yields and downward pressure on stocks.
It will also be a week full of labor market data. The main data release is the employment report on Friday where economists expect another roughly 185,000 jobs were added in October.
On the corporate side, it will be another busy week of earnings. The highlight of the week will be Apple’s earnings results Thursday after the market close. Expectations have diminished going into the report after recent reports that iPhone 15 demand was weak.
|
|
Week in Review:
Stocks opened the week lower and attempted to reverse course and end the day higher for the 16th consecutive Monday, but a reversal failed to gain traction with the S&P 500 ultimately ending the day down 0.17%, ending the streak. Treasury yields on the 10-year note moved over 5.00% in the morning, but that appeared to bring in buyers, which also coincided with a tweet by hedge fund manager Bill Ackman that “there is too much risk in the world to remain short bonds at current long-term rates” which brought more buying and sent the yield lower, finishing down 7 basis points on the day to 4.85%. Energy was in the headlines after Chevron said it would buy Hess, semiconductors with Nvidia reportedly starting to build Arm-based CPUs, and Apple over iPhone 15 demand concerns.
Earnings began piling in on Tuesday, with consumer staple companies like Coca-Cola and others like 3M and GE posting better results than expected, helping move stocks higher. In other news, the UAW expanded its strike to Stellantis’ largest US plant and GM’s most profitable plant, while Meta was sued by 42 attorney generals for it creating an addictive platform targeting kids. Outside of individual company headlines, it was a fairly quiet day. The S&P 500 broke its five day losing streak, the longest of the year, with a 0.73% gain with Treasuries mixed.
Another batch of earnings came in overnight into Wednesday’s trading, with results more mixed than the prior day. It included Microsoft’s strong results, particularly cloud services, but Alphabet’s slowing growth, particularly in cloud which offset strength in its Search and YouTube businesses. These and other earnings reports created additional worries about tech with growth and tech stocks selling off and sending broader markets lower. The NASDAQ experienced its worst day of the year with a 2.43% decline while the Dow fell just 0.32%. Meanwhile, news from Washington was the House finally elected its Speaker, Mike Johnson (Representative from Louisiana).
GDP data Thursday morning showed economic growth of 4.9% (annualized growth rate) in the third quarter, the strongest since 2014 if the pandemic recovery quarters are excluded, thanks to strong consumer spending and inventory restocking. Treasury yields moved higher over the better than expected data. Higher yields, worries about an escalation in the Israel/Hamas war after Israel said it was preparing for a ground invasion, and worries over earnings after more disappointing and mixed earnings results sent stocks lower again on Thursday. Defensive sectors outperformed growth again as the NASDAQ lost another 1.76% while the Dow fell 0.76%.
It was a mixed day on Friday which started with consumer data in the morning that showed inflation and income growth that was roughly in line with expectations but consumer spending that surprised again to the upside. However, additional geopolitical concerns and earnings growth worries were an overhang on markets with stocks ending 0.48% lower, despite a solid report from Amazon. At the same time, oil moved over 2% higher as Israel expanded its ground invasion of Gaza.
It was another down week for stocks as the earnings picture became more mixed and markets moving to a more risk-off stance as defensive sectors outperformed. Treasuries were mixed, starting the week selling off but seeing buying later in the week. The 2-year yield fell 8 basis points to 5.03% while the 10-year yield fell 9 basis points to 4.84%. The dollar index rose 0.4%, gold was up 0.2%, and oil was down 2.9%. Stocks fell more than 2% for the second consecutive week with the major indices finishing as follows: Dow -2.14%, S&P 500 -2.53%, Russell 2000 -2.61%, and NASDAQ -2.62%.
|
|
Recent Economic Data
- Sales of new homes in September surprisingly rose 12.3% to a seasonally adjusted annualized rate of 759,000, well above the expectations of 680,000. Sales are up 33.9% from a year earlier. New home sales are based on signed contracts so this reflects people that were out shopping for homes in September, which comes at more of a surprise because that’s when rates spiked. Reports say builders are buying down mortgage rates aggressively though, which may be contributing to the improving sales pace. Inventory of new homes was 435,000, which has been relatively unchanged all year, and represents a supply of 6.9 months at the current sales pace, with homebuilders said to be continuing to work through backlogs. In addition, a higher share of new home buyers is coming from all-cash buyers.
- New orders for manufactured durable goods for September increased 4.7%, well above the expectations of a 1.0% increase. However, new orders of transportation equipment rose 12.7%, including a 92.5% increase in aircraft, skewing the index to the upside. Excluding transportation, durable goods orders were up 0.5%, still strong and still over double the expectation. Meanwhile, the input to GDP, shipments of nondefense core capital goods excluding transportation, was flat in the month. These shipments rose at an annualized pace of 1.3% in the third quarter, a positive for GDP as mentioned below.
- Growth in the US economy, based on the initial GDP estimate, during the third quarter was at an annualized rate of 4.9%, and excluding the pandemic bounce was the fastest growth rate since 2014. Once again consumer spending saw strength with other major categories contributing. Consumer spending rose at an annual rate of 4.0% in the quarter with a 4.8% increase in spending on goods and a 3.6% increase in spending on services. The strong consumer spending contributed 2.7% to the headline 4.9% GDP number. Business fixed investment grew 0.8%, driven by a 2.6% increase in intellectual property, while residential investment grew 3.9%. Business investment had no contribution to GDP while residential contributed 0.2%. Businesses were busy restocking as investment in inventory contributed 1.3% to GDP. Government spending grew 4.6%, driven mostly by defense spending, and contributed 0.8% to GDP. Finally, the change in the trade deficit was a 0.1% contractor to GDP due to imports increasing 5.7% and exports increasing 6.2% (the dollar amount is what matters, and imports were still larger than exports). One of the better measures of core economic growth, final sales to domestic purchasers, grew a still very solid 3.5%, driven by strength in consumer spending.
- The number of unemployment claims filed the week ended October 21 was 210,000, up 10k from the prior week, although still very low levels. The four-week average increased slightly to 207,500. The number of continuing claims was 1.790 million, up 63k from the prior week, bringing the four-week average up 31k to 1.723 million.
- Consumer spending remained strong in September, according to the latest personal income and outlays report released on Friday.
- First, personal income increased 0.3% in the month, slightly lower than the 0.4% expected and matching the increase seen in August. The all important wages and salaries category rose 0.4%, slightly lower than the 0.5% increase in the prior month. Incomes are up 4.9% from a year earlier, cooling from the 5.1% pace in August.
- Consumer spending surprised again to the upside, rising a healthy 0.7% in September, above the 0.5% estimates and accelerating from the 0.4% increase in August. Spending was driven by both goods and services, with goods spending up 0.7% and services spending up 0.8%. Goods spending is now up 4.6% over the past year while services spending is up 7.9%. With these numbers, it is likely we see an upward revision to GDP next month in the second estimate.
- Consumers are spending 44% more in interest costs compared to 12 months ago, which was 2.7% of disposable income, up from 2.0% of disposable income a year ago, which is expected to continue to increase and will cut into discretionary spending.
- The PCE price index, the Fed’s preferred inflation reading, rose 0.4%, slightly stronger than the 0.3% expected. The index is up 3.4% from a year ago, cooling further from the 3.5% rate in August. Core prices rose 0.3% as expected and are up 3.7% from a year ago, cooling from the 3.9% pace in August.
- Personal savings fell 15% in the month, resulting in the personal savings rate falling to the lowest level of the year at 3.4%, after a steady increase to a two-year high of 5.4% in May.
- Money supply saw another decline in September, now down for the second consecutive month, coming after three straight months of increases, which was after nine consecutive months of declines. Money supply of $20.755 trillion was down $70.4 billion in the month for a 0.3% decline, and down 3.6% from a year ago. Money supply is still up a staggering $5.304 trillion, or 34%, since the pandemic started, one of the most obvious reasons we have had persistent inflation. The good news is money supply is down 4.4% since the peak on February 2022, which will help cool inflation. The bad news is a decline typically leads to lower economic growth.
|
|
Company News
- Reuters reported Nvidia has quietly begun designing CPUs (central processing units – the main chip/brains of computers) that would be able to run Microsoft’s Windows operating system and will use technology from Arm Holdings. Intel, which currently still dominates the CPU market, shares were down on the news, while AMD, who has been taking large market share over the past several years, and Nvidia shares were higher. The report says the plan is part of Microsoft’s effort to help chip companies build Arm-based CPUs for Windows built PCs. Qualcomm currently makes Arm-based chips, and AMD is said to have joined as well. It says the efforts are aimed to counter Apple’s plan on building its own in-house chips for its Mac computers.
- Facebook’s parent company Meta is being sued by a bipartisan group of 42 attorney generals who say features on Facebook and Instagram are targeted at young users which make the platforms addictive and keeps users on for longer and repeatedly coming back, causing harm to the mental health of young people. The attorney generals said Meta does this by the design of its algorithms, frequent alerts, notifications, and its infinite scroll through feeds.
- Early last week, the United Auto Workers (UAW) said 6,800 Stellantis workers at the Sterling Heights assembly plant walked of the job to join the ongoing UAW strike. This is the company’s largest US plant and is known for producing the profitable Ram 1500 model. Separately, hours after General Motors reported its third quarter earnings, the UAW said it expanded its strike to the GM Arlington plant where it builds all of their full size SUVs and is its most profitable plant. GM now has 42% of its production shut down from the ongoing UAW strikes.
- Late in the week, Ford said it had reached a tentative contract agreement with the UAW, which brings the nearly two-month long strike to an end. Over the weekend, it was announced Stellantis, then GM, reached tentative agreements with the union as well. Among many other benefits, the agreement includes a 25% hourly pay raise, plus cost of living adjustments, over the new four year contract.
|
|
Other News
- China said it will issue 1 trillion yuan (about $140 billion) in new sovereign bonds, which will put its budget deficit ratio at about 3.8% from 3.0%, in another effort to provide stimulus to its economy over slowing growth worries. The government is targeting infrastructure, where it said would benefit industries that it believes will replace those that used to drive the economic growth, like its property sector. Separately, one of its largest property developers, Country Garden, officially defaulted on its dollar bond, sending a notice to bondholders that its failure to pay interest on the bonds within its grace period “constitutes an event of default.”
- The European Central Bank kept its policy rates unchanged after its latest policy meeting last week, the first unchanged meeting after 10 consecutive rate increases. Policymakers agreed to start discussing early next year the possibility of ending its Pandemic Emergency Purchase Program early, which started during the pandemic to maintain functioning of the bond market. Some policymakers have made the case the program is working against the central bank’s efforts to tighten monetary policy in order to bring inflation lower. The opposing argument is the program is needed for weaker Eurozone economies like Italy because it protects them from undue market volatility.
- The Bank of Canada said in its latest policy meeting last week it would keep its policy rates unchanged as well, adding that it is seeing growing evidence that past rate increases are beginning to work on “dampening economic activity and relieving price pressures.” It added that consumption has been “subdued” and housing and durable goods have seen softer demand. However, it said it is concerned that progress toward bringing inflation to target has slowed and risks of inflation reaccelerating have increased.
- Late last week the House elected Mike Johnson, Representative from Louisiana, as Speaker of the House in a 220-209 vote. The big question now will be if Congress can pass a continuing resolution beyond the November 17 deadline which would give Congress more time before a more crucial deadline.
|
|
WFG News & Events:
Medicare Open Enrollment
Medicare Open Enrollment period runs from October 15 to December 7 each year
- During this period, individuals are able to make changes to their current Medicare coverage. Individuals on Medicare should receive an Annual Notice of Change and/or Evidence of Coverage for Medicare Advantage or Part D plan. This is a good time to review coverage, as medical needs, benefits, and premiums may have changed over the year. During this time here are some things to consider:
- Will your primary doctor still accept you Medicare Advantage Plan?
- Have your medical needs changed? Different plans offer different benefits and different costs
- Are there comparable, lower cost plans available? Don’t forget to consider out-of-pocket costs when comparing options
- Are you medications still on your plan’s list of covered medications?
Office Update
Please take note Wentz Financial Group will be closed Friday November 24th, the day after Thanksgiving.
Toys for Tots Toy Drive
Wentz Financial Group is excited to have partnered with the United State Marine Corp on their Toy for Tots toy drive in 2023. Starting next week we will begin collecting toys to be donated to the Marine’s efforts. In addition we are hosting an open house the Friday before Thanksgiving focused on the project. Please stop by WFG on November 17th between 11:00 AM and 2:00 PM to help us in this worthwhile endeavor.
Marine Corp Toys for Tots Drop Off – November 17th 11:00 AM – 2:00 PM
Career Development Day
Monday, December 18, 2023 - All Day
Do you know someone in high school or college looking to get real life work experience from the finance industry? Wentz Financial Group will be hosting its 3rd Career Development Day at our office on December 18. The day will not only be for those looking to get a first look into financial services field but is open to any student wanting to get their feet in the door of the professional world. Don’t forget to RSVP by responding to this email or calling the office at 330-650-2700.
|
|
Many labor market indicators will be released this week including the job openings and labor turnover survey, ADP employment report, and the Department of Labor employment report for October. The consensus of economists sees about 185,000 new jobs added in the month, a slowdown from the first half of the year but still signaling strong labor market growth. Elsewhere on the economic calendar, on Tuesday we will see the employment cost index for the third quarter, the consumer confidence reading for October, and a reading on home prices with the Case-Shiller home price index which is expected to show another 0.7% increase in home prices in September. Wednesday will see manufacturing readings with the PMI and ISM manufacturing indexes, and data on September construction spending. On Thursday the first read on third quarter productivity and labor costs is released along with October vehicles sales. The main economic event will be the employment report on Friday. On the earnings front, another 30% of the S&P 500 is expected to report quarterly financial results. Earnings estimates have come down in recent days, and this week will include key reports from companies such as McDonald’s, Pinterest, SoFi on Monday, AMD, Busch, Caterpillar, Pfizer on Tuesday, Airbnb, CVS, Kraft, PayPal, Qualcomm on Wednesday, Moderna, DraftKings, Starbucks on Thursday, and Dominion on Friday. But all eyes will be on Apple’s results on Thursday afternoon. Finally, the main event for investors will be the Federal Reserve FOMC meeting that ends on Wednesday with a policy announcement at 2:00. No change in rates are expected, but market participants may, after recent stronger data, may be looking for hawkish commentary after the recent stronger economic data.
|
|
|
Securities offered through Raymond James Financial Services, Inc., member FINRA/SIPC. Investment advisory services are offered through Raymond James Financial Services Advisors, Inc. Wentz Financial group is not a registered broker/dealer and is independent of Raymond James Financial Services. The information contained within this commercial email has been obtained from sources considered reliable, but we do not guarantee the foregoing material is accurate or complete.
The S&P 500 is an unmanaged index of 500 widely held stocks that is generally considered representative of the U.S. stock market. The Dow Jones Industrial Average (DJIA), commonly known as “The Dow” is an index representing 30 stock of companies maintained and reviewed by the editors of the Wall Street Journal. The Russell 2000 Index measures the performance of the 2,000 smallest companies in the Russell 3000 Index, which represent approximately 8% of the total market capitalization of the Russell 3000 Index. The NASDAQ composite is an unmanaged index of securities traded on the NASDAQ system. The Nikkei 225 is a stock market index is for the Tokyo Stock Exchange (TSE). It is the most widely quoted average of Japanese equities. Bitcoin issuers are not registered with the SEC, and the bitcoin marketplace is currently unregulated. Bitcoin and other cryptocurrencies are a very speculative investment and involves a high degree of risk. Every investor's situation is unique and you should consider your investment goals, risk tolerance and time horizon before making any investment. Sector investments are companies engaged in business related to a specific sector. They are subject to fierce competition and their products and services may be subject to rapid obsolescence. There are additional risks associated with investing in an individual sector, including limited diversification. Information contained herein was received from sources believed to be reliable, but accuracy is not guaranteed. Information provided is general in nature and is not a complete statement of all information necessary for making an investment decision and is not a recommendation or a solicitation to buy or sell any security. Investing always involves risk and you may incur a profit or loss. Keep in mind that individuals cannot invest directly in any index. Past performance does not guarantee future results. There is no guarantee that these statements, opinions or forecasts provided herein will prove to be correct.
The foregoing information has been obtained from sources considered to be reliable, but we do not guarantee that it is accurate or complete, it is not a statement of all available data necessary for making an investment decision, and it does not constitute a recommendation. Any opinions are those of the authors and not necessarily those of Raymond James.
Bond prices and yields are subject to change based upon market conditions and availability. If bonds are sold prior to maturity, you may receive more or less than your initial investment. There is an inverse relationship between interest rate movements and fixed income prices. Generally, when interest rates rise, fixed income prices fall and when interest rates fall, fixed income prices rise.
Holding stocks for the long-term does not insure a profitable outcome. Investing in stocks always involves risk, including the possibility of losing one's entire investment.
An investment in a money market fund is neither insured nor guaranteed by the FDIC or any other government agency. Although the fund seeks to preserve the value of your investment at $1.00 per share, it is possible to lose money by investing in the fund.
Investors should consider the investment objective, risks, charges, and expenses carefully before investing. The prospectus, which contains this and other important information, is available from your Financial Advisor and should be read carefully before investing.
|
|
|
|
|
|
|