|
Here's something many homeowners don't realize:
A STANDARD HOMEOWNERS INSURANCE POLICY TYPICALLY DOES NOT COVER FLOOD DAMAGE.
Flooding isn't limited to homes located next to rivers or streams.
Heavy rainfall, rapidly melting snow, overwhelmed drainage systems, runoff, changing landscapes and severe storms can all contribute to flooding.
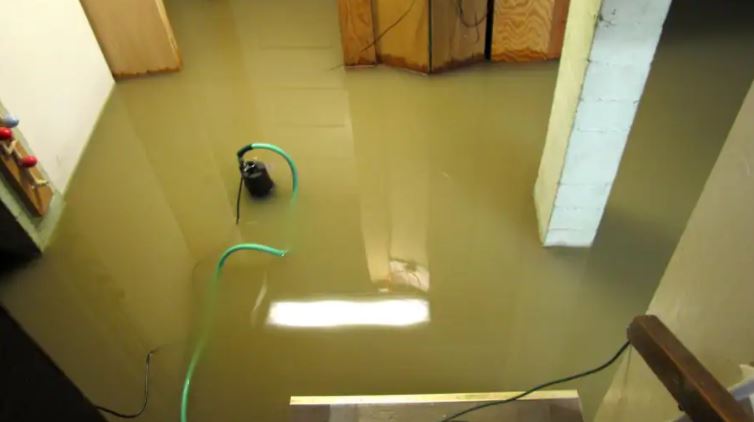
And even a relatively small amount of water entering your home can result in significant damage.
WHAT CAN FLOOD INSURANCE HELP PROTECT?
Depending on the policy and coverage selected, flood insurance can provide protection for the building, including items such as:
✔ Foundation and structural components
✔ Electrical and plumbing systems
✔ Furnaces and water heaters
✔ Permanently installed carpeting
✔ Built-in appliances
✔ Certain permanently installed fixtures
Separate contents coverage may help protect personal belongings such as:
✔ Furniture
✔ Clothing
✔ Electronics
✔ Certain appliances
✔ Other covered household belongings
Coverage, exclusions, deductibles and limits vary by policy and carrier.
“BUT I'M NOT IN A HIGH-RISK FLOOD ZONE.”
That's one of the most important conversations to have with your insurance agent.
Living outside a designated high-risk flood area does not mean your property has zero flood risk.
Flood maps are an important tool, but weather, drainage, construction and development can change how water moves through an area.
DON'T ASK ONLY:
“Am I required to have flood insurance?”
Also ask:
“What would happen financially if my
home flooded and I didn't have flood coverage?”
That's a very different question.
Contact FRM Group and Financial Services for details.
|