|
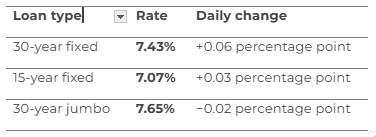
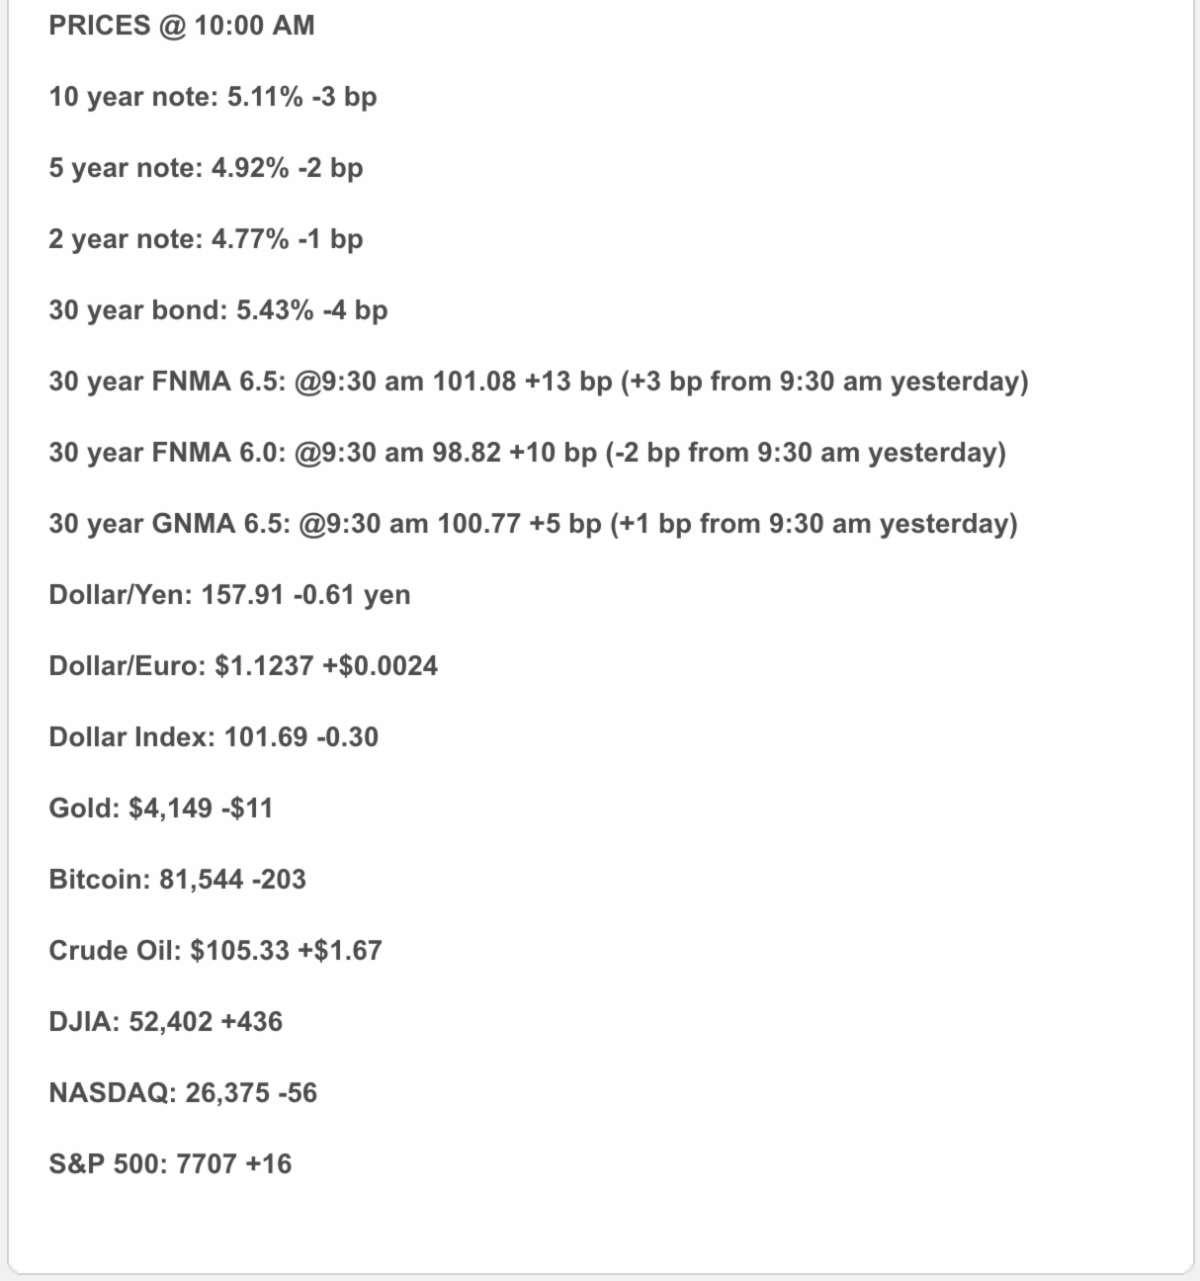
The 30-year benchmark has given back 0.10 percentage point since Thursday. At 7:00 a.m. ET today, the 10-year Treasury was 5.118%, down roughly 1.7 basis points, with mortgage bonds modestly stronger.
These are national benchmarks, not personalized quotes or APRs. Actual pricing varies by borrower, property, product and points and can change intraday.
🏠 Housing: Contracts Took a Hit
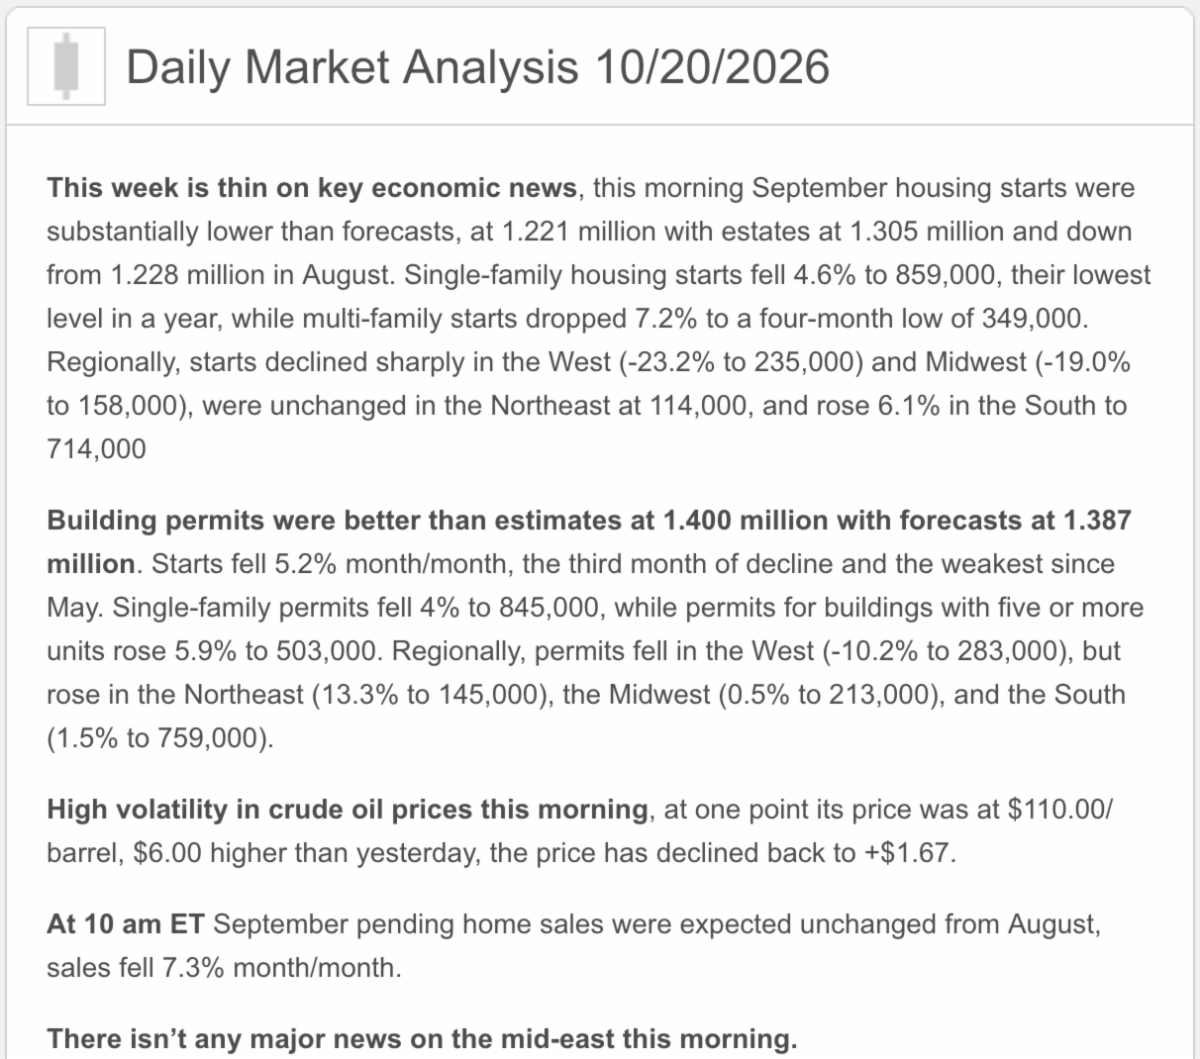
September pending home sales fell 7.3% monthly and 11.3% annually. All four regions declined, led by the West at −9.2% monthly.
These are signed contracts, not completed closings. The message: buyers remain highly sensitive to monthly payments. Slower demand can create negotiating room, but it does not guarantee falling prices.
🏗️ Construction: A Smaller Pipeline
September housing starts were estimated at 1.221 million annualized, down 5.2%. Single-family starts fell 4.6% to 859,000, while single-family permits dropped 4.0% to 845,000.
Starts are volatile and subject to revision. Nevertheless, weaker building activity alongside weaker contracts adds to the evidence of affordability strain—and fewer starts can limit future supply.
🏦 Fed Watch: Pause Does Not Mean Finished
A new Reuters survey found 94 of 100 economists expect an October hold at 3.75%–4.00%. All 100 expect a December increase.
Those are forecasts, not Fed promises. Mortgage rates still respond to longer-term inflation expectations and bond-market pricing.
📈 Markets: Oil Reverses, Stocks Rise
At 10:45 a.m. ET:
-
Dow: +1.3%
-
S&P 500: +0.6%
-
Nasdaq: +0.5%
-
Brent crude: $106.78, down 2.5% after approaching $112 earlier
Strong earnings helped stocks. Sustained energy relief would help inflation; one volatile morning does not settle the issue.
🏛️ Politics & Policy
A Reuters/Ipsos poll published Monday put President Trump’s approval at 31%, with living costs weighing on voters ahead of November 3.
Today, Treasury Secretary Scott Bessent argued that a Democratic House would have limited ability to block the administration’s agenda, citing tariff authority. That is the administration’s position; the election and subsequent policy outcomes remain uncertain.
For housing, energy prices, trade policy and borrowing costs remain the practical issues to watch.
🎯 Your Tuesday Game Plan
-
Buyers: Compare seller credits and price reductions using your actual payment.
-
Agents: Show cash to close and explain the payment increase when a temporary buydown ends.
-
Homeowners: Evaluate refinance costs, savings and break-even using a current quote.
🔒 Lock vs. Float
-
Closing within 15 days? Consider protecting a payment that works.
-
Floating longer? Set a clear trigger and allow room for higher payments.
-
Further out? Compare financing structures and concessions now.
|