|
Greetings!
The Founder Left, the Index Held
By Eli Gal Levy, Senior Analyst
Week of November 9–13, 2026 · Cannon Intelligence Desk
A week that lost Nvidia's founder ended with every major index higher. The S&P 500 rose 2.51% to 7,561.67, the Nasdaq Composite 2.27% to 25,136.27, the Dow 2.07% to 52,347.55 and the Russell 2000 1.32% to 2,790.49. The SOX gained 8.05% to 10,146.32 even as Nvidia fell 12.75% to 162.85; AMD rose 18.9% and Broadcom 18.2%. The VIX ended at 19.30, down from 25.64. The S&P now sits 3.3% under its October 6 record close of 7,818.93.
The bill arrived in bonds instead. The ten-year closed Friday at 5.15%, up 29 basis points on the week.
The week in sequence
Monday Nvidia's board opened an investigation into chief executive Jensen Huang, and the stock fell 4.27% to 178.67. The rest of the market rallied anyway: the S&P gained 2.35% to 7,549.94, the Russell 3.15%, and the semiconductor ETF SMH 5.05% as AMD led the chip rebound. Up volume was 77% of the total.
Tuesday October CPI rose 0.4% for the month, after 0.6% in September, with core up 0.3% for a third straight month. There was no year-over-year figure: October 2025 prices were never collected during last year's funding lapse. Governor Waller said a half-point December hike "should be considered," and Dallas Fed President Lorie Logan wants at least two more quarter-point hikes. The ten-year rose 12 basis points to 4.98%, the S&P slipped 0.38%, and Nvidia fell another 5.47% to 168.89. After the close CoreWeave grew revenue to $3.66 billion from $1.37 billion and raised its full-year guide to $13.0–$13.3 billion.
Wednesday, with the bond market closed for Veterans Day, CoreWeave jumped 24.7% and Micron 11.9%, and the S&P rose 1.31% to 7,619.38 — back above 7,600. After the close, reports said Nvidia's board was preparing to replace Huang.
Thursday the board accepted Huang's resignation. CFO Colette Kress became interim chief executive and director Harvey Jones the first board chair. Money rotated within AI: AMD rose 5.86% and Broadcom 5.54% while Nvidia fell 4.34% to 166.19, and the neoclouds, CoreWeave and Nebius, took the losses. By then Baird's Tristan Gerra, Bernstein's Stacy Rasgon and Oppenheimer's Rich Schafer had all stepped back on Nvidia. The index lost only 0.35%, but the Russell fell 1.66% as the reopened Treasury market repriced the inflation report: the ten-year closed at 5.10%, and the 30-year auction cleared at 5.441%. After the close Cisco reported record revenue of $18.5 billion, up 24%, and raised its outlook, and Applied Materials posted record revenue of $10.41 billion, up 53%.
Friday October producer prices rose 0.3% for the month and 6.5% from a year earlier, with core up 0.5% and 4.9%. The SOX gave back 3.43%, AMD 8.75% and Broadcom 4.76%, and the S&P slipped 0.40% after an intraday low of 7,499.40. Up volume was 47.7%, and 64.1% of members held above their 200-day.
What the rest of the market said
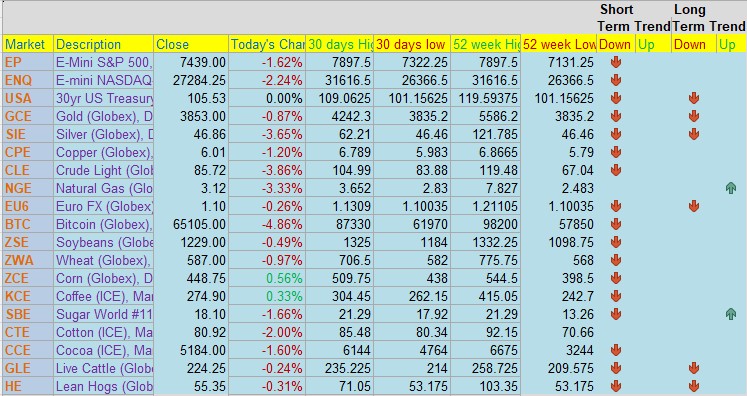
Rates did the damage, led by the two-year: a market pricing Fed hikes, not deficits. The dollar index rose 1.1% to 103.41 and gold fell 4.7% to 3,887.60. December WTI slipped 1.6% to 88.92.
Credit never flinched: the high-yield spread sat at 3.30% midweek, little changed. Net liquidity added for a second straight week, to $5.85 trillion, up $35 billion.
Who moved
Mike Wilson (Morgan Stanley) said the correction "looks much closer to the end than the beginning," with the index in the 7,100–7,300 support range he set in August. He allows one more test of the lows, favors quality cyclicals led by industrials, and warns a more hawkish Fed could stretch the bottoming into December.
Ed Yardeni went from caution to buyer. His note "Time To Sound The All Clear Signal?" called last Thursday's selloff the buying opportunity he expected. He holds 7,900 for year-end — and now expects the Fed to hike a half point in December.
Tom Lee (Fundstrat) called a December hike a mistake and wrote that "markets bottom on bad news." He told followers to buy the dip in Nvidia and signed the letter backing Huang's reinstatement. Dan Ives (Yorkville Ives) cut his Nvidia target to $225 from $300 but kept his Buy, calling roughly 10 times 2028 earnings "way too cheap once Nvidia gets through this storm."
Mark Newton (Fundstrat) moved from "no exhaustion, no capitulation" to long technology on a three-to-six-month view, seeing the decline ending around November 20. Friday's note added that tech's decline is in the ninth inning but needs more patience.
David Keller (Sierra Alpha) watched the S&P reclaim his 7,600 line Wednesday, then wrote he is "not yet in the 'all clear' camp" with the index and its RSI stalled at 7,600 and 50. Jonathan Krinsky (BTIG) says the rebound has not cleared technical risks. Michael Hartnett (BofA) stays risk-off until the ten-year falls below 4.5% and oil reaches $70, with a bull case above 8,000 and a bear case below 7,000.
Into next week
Nvidia reports Tuesday after the close, with an interim chief executive who is also its finance chief and no reaffirmed guidance. Friday is November options expiration.
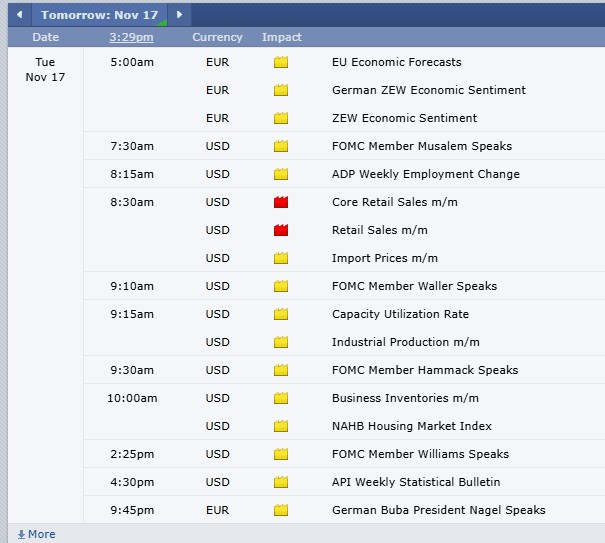
On the calendar: Empire State Monday (forecast 16.7, prior 25.5) with Chair Warsh at noon. Tuesday brings retail sales (0.2% vs 0.8%), import prices and industrial production, with Waller, Hammack and Williams speaking. Wednesday has housing starts and the FOMC minutes at 2:00. Thursday brings the Philadelphia Fed survey (18 vs 20.9) and claims (200K). Friday has final Michigan sentiment (52.2 vs 48), Waller and Cook.
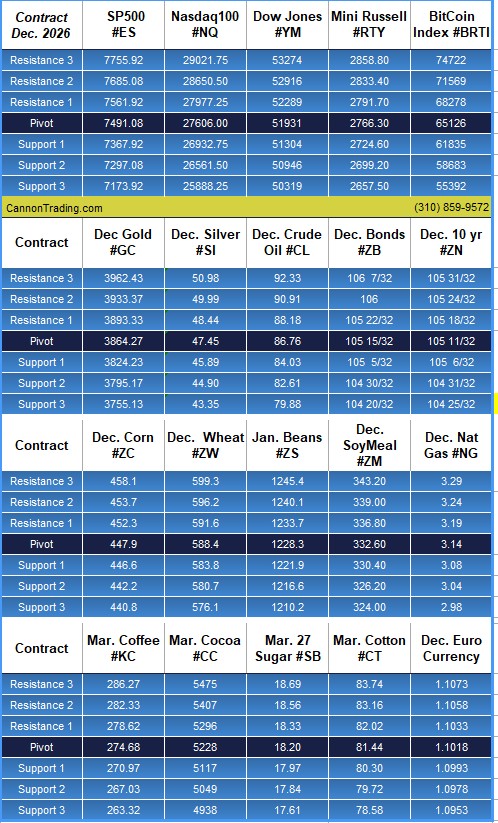
On the map: the public dealer-gamma model on Thursday's close put the put wall at 7,500, the call wall at 7,700 and the flip at 7,652.56, so Friday's close sits under the flip, inside the walls. Keller's 7,600 is the line overhead, Wilson's 7,100–7,300 the zone below, and Friday's 7,499.40 low tagged the put wall, well above last week's 7,361 Fibonacci level. The ten-year above 5.1% is now the number the bulls have to get through.
I am biased toward the tape. I follow what the market does, not what I think it should do. Right now, the tape is a percent off its highs with volatility at a year-to-date low, the front-end pricing a hike, and breadth thinning underneath — and I will keep watching the ten-year, the credit spreads and the equal-weight index and ETF-HYG to tell me when those changes.
View Charts and Analysis for SP, Nasdaq, Dow, Gold, Crude Oil, Dollar Index, VIX, Bonds, BTC and More!!
Need help looking at different markets? get some insight from an experienced series 3 broker?
The call is free and we are here to assist - try us!
+310 859 9572
|