BLUME'S BULLS & BEARS
By: Jake Blumenthal
October 30th, 2026
#149
Note for my Arizona readers: Next week's newsletter will come out at 10:00 a.m. as we transition out of daylight saving time. Football kickoff times will move back, and so will Blume's Bulls and Bears! Market hours in Arizona will also shift to 7:30 a.m.–2:00 p.m. starting Monday.
| |
Weekly Recap
This week, major market indexes were down for the most part, as the tech sector sold off sharply to end the week. The Nasdaq fell around 1.5%, followed by the Dow Jones and S&P 500, each down closer to 0.5%. The Russell 2000 was the bright spot, gaining about 1.3%. Healthcare was the best-performing sector, up over 3%, while communications and technology were the two main laggards.
The Fed decided to keep interest rates at their current range of 3.75% to 4%.
Lastly, we saw a slew of major earnings movers this week. Let's start with the stocks selling off. ServiceNow is getting crushed, falling 25% after issuing very weak guidance. Intel and Reddit also got crushed following very underwhelming reports. GOOGL dropped more than 10% after missing on several metrics. Caterpillar (CAT) fell roughly 7% as higher costs from tariffs and rising inventories raised concerns about a potential slowdown, although the company beat revenue and EPS estimates. Fortinet, the cybersecurity company, also sold off roughly 20% after a disappointing quarter. I think CrowdStrike and Palo Alto Networks are taking market share and stealing their lunch.
On the upside, Vertiv, Chipotle, Eli Lilly, L3Harris, Merck, and others moved higher following strong earnings reports. Two notable moves unrelated to earnings were Oracle, which popped on positive commentary from its investor day, and Marvell, which fell sharply on rumors that it may try to acquire Lumentum (LITE). I actually like the strategic rationale behind a potential deal.
|
|
Hot Topic:
"Anthropic (Claude) IPO"
| |
The hot topic this week was Anthropic, the company behind Claude’s AI models, filing its S-1 (attached here) as it prepares for an IPO. No date has been announced or confirmed yet, but the company is taking steps to get ready.
This would make Anthropic the second of three major private companies expected to go public. First, we had SpaceX. Next up could be Anthropic, which is expected to trade under the ticker ANT, followed by OpenAI, potentially sometime next year.
A couple of thoughts to share. First, I hope we can remind ourself of the lessons learned from watching SpaceX go public at such a high valuation. Anthropic is expected to command a similar valuation, potentially between $1.5 trillion and $2 trillion. We saw SpaceX begin trading around $160, climb to $220 within two weeks, and then fall to approximately $105 within the next month or two. It has since rebounded to around $140-$150, slightly below its initial trading price. IPOs take time to settle. They have historically launched with tremendous demand, but insiders also gain opportunities to sell shares. Expect similar volatility with Anthropic, and give the stock time to find its footing after it goes public.
Second, the amount of competition concerns me, especially at such a high valuation. Don't get me wrong: I personally think Claude may be the best AI model available today. However, Anthropic is competing against Google, OpenAI, Tesla, and others. Those are formidable competitors, and I worry about whether Anthropic's valuation reflects its long-term potential or too much hype.
That said, the numbers have impressed me. Anthropic reportedly generated $16 billion in revenue during the first half of 2026, up 1,300% from the prior year. That is incredible growth. The question is where growth settles over the next few years: will it remain in the triple digits, or eventually slow to around 50%?
One detail that caught people's attention was the diversity of Anthropic's customer base. No single customer accounted for more than 10% of revenue, and 79% of revenue came from customers outside its top five. That is an encouraging sign.
Anthropic reported:
- More than 11,900 customers spending $100,000 or more over a 12-month period.
- More than 1,900 customers spending $1 million or more over a 12-month period.
- Approximately 250 customers spending $10 million or more over a 12-month period.
Here is why this supports the investment thesis for me: Anthropic is generating revenue from a broad range of customers, with significant room for expansion. Gavin Baker highlighted that Fortune 500 customers spending at least $100,000 annually were spending an average of just 0.1% of their total expenses on Anthropic during the September 2026 quarter.
Think about that. If Claude continues improving and Anthropic finds more use cases, what happens if businesses increase their spending from 0.1% of total expenses to 1% or even 5%? That could create a substantial runway for potential future growth.
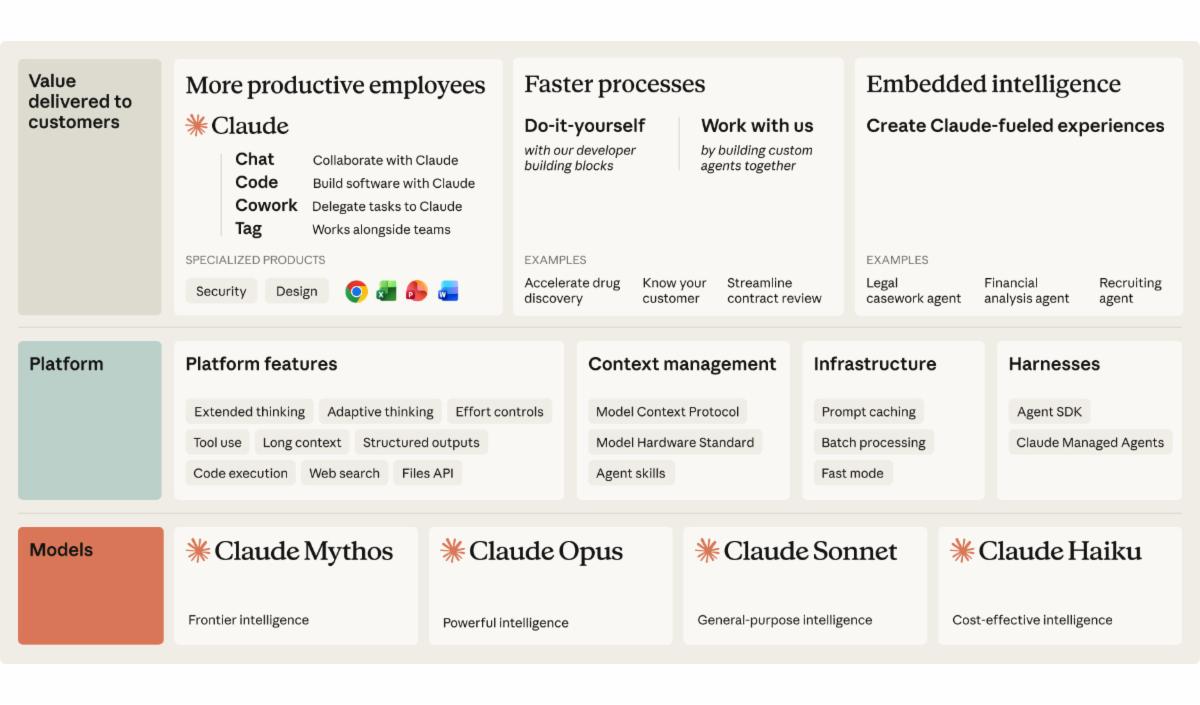
Anthropic's models, listed below, have the potential to make employees and businesses more productive while reducing costs. That gives companies a reason to spend significantly more on these products over time. It is an exciting opportunity, but Anthropic will need to keep improving its models to stay ahead of competitors.
P.S. If you see reports claiming Anthropic has approximately $80 billion in debt, that figure may be misleading. It reportedly includes convertible notes associated with Amazon that are expected to convert into equity following an IPO. Its actual debt burden may be substantially lower, reportedly closer to $6 billion.
| | |
Next week, we'll get an updated unemployment number to kick off November. The unemployment rate for September edged up to 4.2%, from 4.1%, which we had seen over the previous two months. I expect it to remain at 4.2% for October, with little impact on the markets. Inflation is the big number we'll need to keep an eye on later in the month. We'll also have the midterm elections next Tuesday, November 3. It will be nice to finally have those behind us soon. As I've continued to say, I don't think the results of the midterms should matter as much as simply getting them over with and knowing who won and lost.
Earnings to Watch:
- Tuesday: AMD, Amgen, Arista Networks, Pfizer, Eaton, Progressive, Marathon Petroleum, Booking Holdings, Block, Yum Brands, Leidos, & More
- Wednesday: Qualcomm, McDonald's, Uber, CVS, Datadog, Emerson Electric, AppLovin, TKO Group, Global Foundries, & More
- Thursday: ConocoPhillips, Parker-Hannifin, Cloudflare, Airbnb, The Southern Company, Duke Energy, Monster Beverage, Lumentum Holdings, Devon Energy, Live Nation, Kimberly-Clark, Axon Enterprise, & More
Another big week ahead, kicking off Monday with two exciting reports from Palantir and Apple. I love when companies report on a Monday because they get the day to themselves, allowing investors to focus solely on their results. Palantir's last quarter was extremely strong and helped drive the stock higher to where it is today. I think we could see another report with numbers coming in above expectations. For Apple, I think much of the conversation will center around the new Duo phone. I'm curious to see how that launch is going and what management has to say about it.
Tuesday: There are plenty of big names reporting, but my eyes will really be on AMD, which I am very excited about. AMD has had a great year and a strong Q3 despite many other chip names struggling. I expect continued steady demand for its chips to show up in the numbers, but I wonder whether that is already priced in. I believe they are stealing market share from Intel.
Wednesday: This is the interesting one in the middle of the week. McDonald's has been struggling. What will the numbers say? Do they support a turnaround yet? As for Uber, are they feeling the pressure from Waymo and Tesla? Do the numbers show any cracks? The stock price sure thinks so...The Dog (DDOG) is the one I expect to be the highlight of the day, potentially popping after earnings. AppLovin has been awful as it faces stiff competition from Google. I would avoid it and don't have much confidence in its report.
Thursday: Another day with some big names reporting, but Axon will be the main one drawing my attention. The stock has sold off hard over the past year, and I think it looks very interesting around $425. It has been resilient at this level, and a good quarter could be the catalyst for a breakout.
Friday: I'm very, very interested in Vistra. I've said this has been one of the most frustrating stocks of the year for me, right alongside Netflix, and I'm waiting for a breakout to the upside. Is this the quarter? Doubtful, lol.
| |
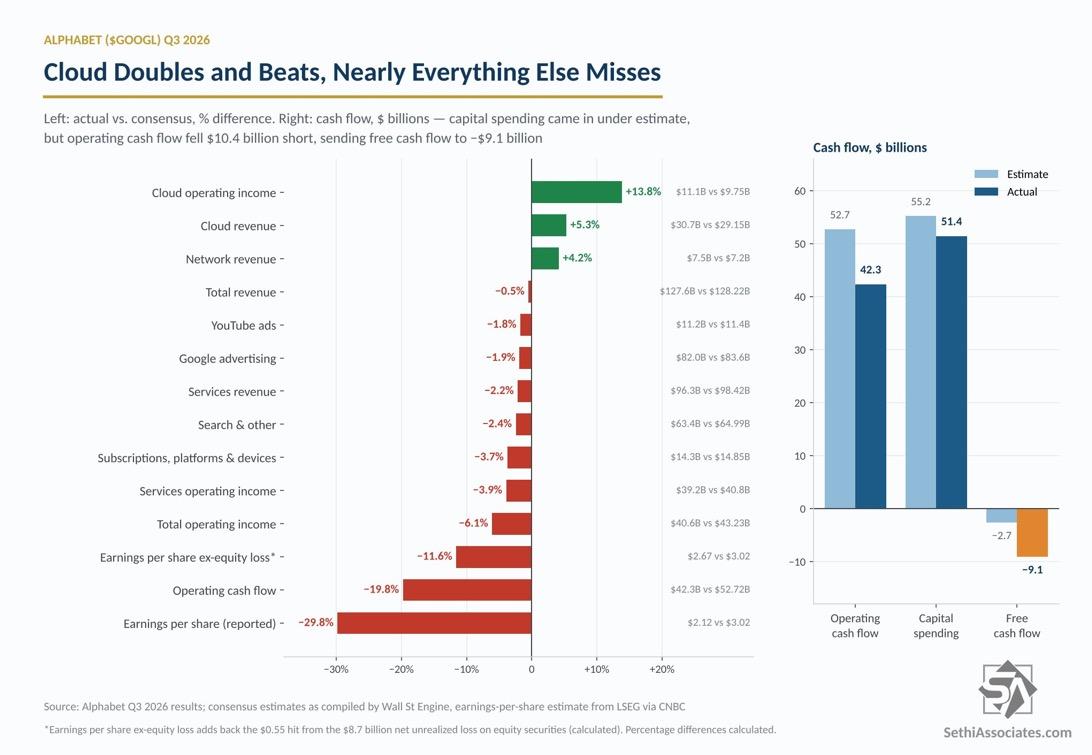
 | | Alphabet Inc (GOOGL) - Buy, buy, buy! That’s the jingle going around in my head that Jim Cramer always says. GOOGL dropped roughly 12% following what many viewed as an underwhelming earnings report. As you can see in the chart, only three metrics beat estimates, while the rest missed. Honestly, I’m not too concerned. Sure, they may have had a bad quarter, or perhaps analyst expectations got too high, too quickly. Either way, to me it seems Alphabet (Google) is well positioned to capitalize on AI. Cloud revenue grew 103%, which is incredible strength, and the Gemini app now has 1 billion users. CapEx also came in below expectations. However, analysts are hung up on negative free cash flow (FCF) because the company is investing heavily in itself, along with an EPS miss partly driven by a tough comparison to last quarter, when earnings benefited from gains on its SpaceX investment. At 19x earnings, 19x!!!, I would be a buyer of GOOGL after this drop. The stock is more than 25% below its high and it is holding around its April low. I think the $270–$290 range is a golden zone to load up on shares. Take this sell-off, as painful as it may be, as an opportunity.
Vertiv Holdings (VRT) - Can earnings season save AI stocks? VRT provided a sign that it might. After dropping nearly 50% from its highs earlier this year, the stock jumped more than 15% on an absolutely stellar earnings report. They beat revenue and earnings expectations by a solid margin, expanded profit margins, and raised their guidance for the upcoming quarter and full year. The results underscored the continued strength of spending on AI data centers. As a provider of cooling systems and power management equipment, Vertiv is still seeing tremendous demand and remains well-positioned to benefit from the AI buildout. This suggests that demand for the physical infrastructure supporting AI expansion remains strong, and we shouldn't overlook it. The numbers back that up, with revenue rising 61% this quarter and earnings climbing 78%. That helps justify the stock trading at around 30x earnings, and honestly, it could command an even higher valuation given its growth rates, expanding margins, and competitive moat. Oh, and did I mention that management said on its earnings call that we're in the middle of the largest infrastructure buildout in history, and that it's ACCELERATING? This is a name I love for the AI buildout, and despite jumping more than 15% this week, it remains roughly 35% below its all-time high.
Robinhood Markets (HOOD) - They reported earnings this week, and while the results were okay, the stock sold off a little. However, after digging into the numbers, I have some concerns about where the company generates its revenue. Yes, it's nice to see that they have around $400 billion in assets under management, but did you know that roughly 50% of the company's revenue comes from transactions involving options, cryptocurrency, and gambling—sorry, I mean "event contracts" or "prediction markets"? That worries me. This figure doesn't even include equity transaction revenue, which could add a few more percentage points. My concern is twofold. First, I believe transaction fees will continue to move lower and lower, potentially approaching zero over time. Second, if a significant portion of the company's revenue comes from these three activities, it suggests a reliance on customers who may reduce their trading activity if they lose money, markets decline, or their trades don't go as planned. That could put pressure on the company's revenue. To put things into perspective, cryptocurrency transaction revenue was already down 55% year over year. I'll continue to keep an eye on this name. I do think it could be a tradable short-term opportunity, but I still have doubts about the long-term business model. That said, the company's brand reputation among younger generations is strong, which I believe is a positive.
| | * Disclaimer - It's important to highlight that, on occasion, I may have existing positions in the stocks I highlight in my newsletter. This disclosure aims to be transparent about potential conflicts of interest. Additionally, any stocks identified in this section are for informational purposes only and nothing in newsletter should be construed as a recommendation to buy or sell any security. Although I strive for unbiased analysis, my ownership of certain stocks may influence those that I highlight. Rest assured, my commitment to providing well-researched insights remains unchanged. | | |
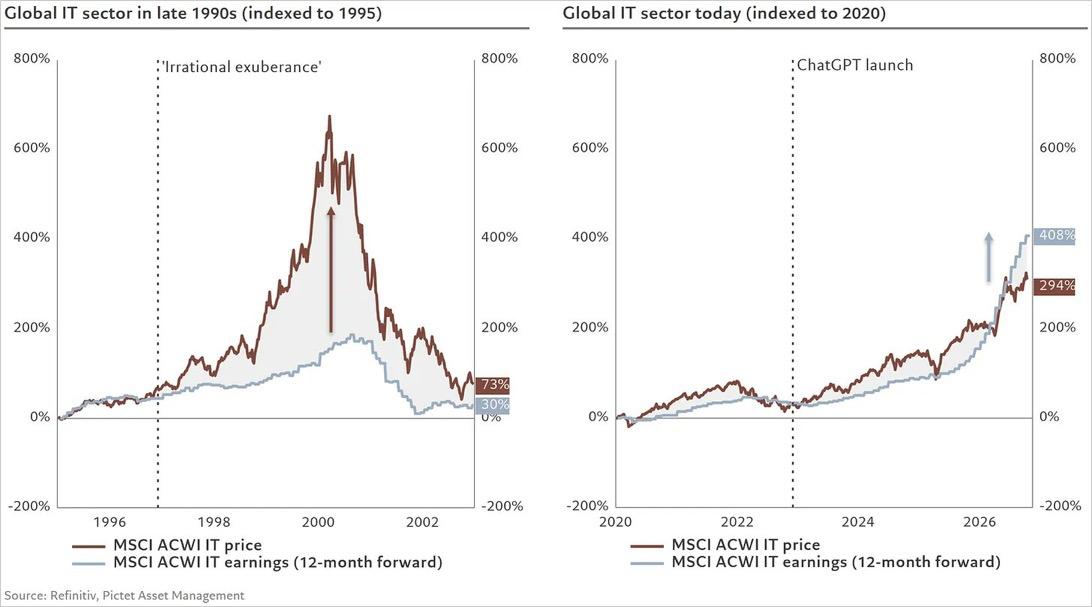
I am very excited about this chart this week! To me, it clearly illustrates why the so-called AI "bubble" that the media and some analysts are trying to portray is nothing like the dot-com bubble.
On the left, the chart shows stock prices in the tech sectorduring the dot-com era in brown and earnings growth for that stock index in gray/light blue. You can see that stock prices surged far beyond earnings growth, inflating valuations and creating what was, in fact, a bubble. The dot-com bubble was ultimately a story of too much supply and not enough demand.
Now, look at today's market. Stock prices have risen significantly, but earnings growth has been strong as well. In fact, earnings growth has outpaced stock prices, supporting the argument that this isn't simply a speculative bubble. Real earnings, real profits, and strong momentum are driving stocks higher. I mean, NVIDIA is cheaper today than it was five years ago, before this AI boom really took off, because earnings have grown that much.
Today, we're facing a different problem than we did during the dot-com bubble: we have more demand than supply. We need time and capital to build out the infrastructure necessary to meet the incredible demand for new AI technologies, from AI agents to intelligent robots.
So don't be fooled by what I believe is fearmongering and a misleading narrative. In my view, today's AI boom is fundamentally different from the dot-com bubble.
| | |
In Weekend Favorites, I share my thoughts on events I'm attending, the new series I'm planning to marathon, the movie I'm dying to see, restaurant craving to taste, trend that ticks me off, or the big game I won't miss.
A couple of things... First, last week I finally got to try Wildflower on Oracle for the first time, and I thought it was okay. I loved their crispy rice appetizer. It was fantastic, and I could have eaten 100 of those things! The calamari appetizer was crispy and good, but it wasn't my favorite. The dumplings, however, were fantastic. I highly recommend them. For dinner, I got the braised short rib, and it was just okay. Nothing too crazy, but the bar is set pretty high after having my favorite short rib dish at that French restaurant in Boston's North End. It was the best meal I've had in a long time, so my standards are high! All in all, Wildflower was good, but if I were to go back, I'd probably get the New York strip. If I'm in the area, though, I'd definitely rather go to Charro Steak.
Second, the new season of Nobody Wants This is back, and I literally binged the entire thing last weekend. It was so good, as every season has been, and it might even be the best one yet. Netflix is pumping out these seasons while the show is hot and has momentum, and I ain’t complaining! I highly recommend this comedy-romance series. The new season of Tulsa King has been FANTASTIC as well. I just hate having to watch one episode a week, but maybe that’s healthy. Then again, maybe not, because now I eagerly wait for every weekend to watch the next episode! Thankfully, I’ve been filling the rest of the week with Season 4 of The Diplomat, which I just finished last night, and it was phenomenal. The twists and turns each season keep the show exciting and leave viewers guessing. This season, in particular, was very aggravating, thanks to the president, but man, was the ending good! I highly recommend it to anyone interested in politics or international conflicts. This season has been great!
| | To learn more about Jake and what the Meridian Team can offer you, use the links below! | | | To read more of Jake's Analysis on Seeking Alpha where he shares his thoughts, opinions, stock ratings, and price targets on different stocks and ETFs, use the link below! | |
Sources:
- https://app.koyfin.com/home
- https://seekingalpha.com/
- https://www.blackrock.com/us/financial-professionals
- https://www.cnbc.com/
- https://x.com/home
- https://www.virtus.com/our-thinking/insights?
- https://www.franklintempleton.com/
- https://www.globalxetfs.com/insights
- https://datatrekresearch.com/?v=0b3b97fa6688
|
Disclaimer:
Advisory services offered through Meridian Wealth Management, LLC, a Registered Investment Advisor. Seek tax, legal, insurance, and investment advice from a licensed professional relative to your situation. The information and opinions voiced in this material are strictly for general information only and are not intended to provide any security recommendations, specific advice, or recommendations. Any views or opinions presented in this material are solely those of the Author and do not necessarily represent those of Meridian Wealth Management, LLC. Any mention of the use of a particular company, organization, or website is merely an opinion of the Author and is not a paid endorsement or advertisement. Securities and insurance products are not insured by the FDIC or any federal government agency, are not a deposit of or guaranteed by a bank or any bank affiliate and may lose value. No one connected with Meridian Wealth Management, LLC, can ensure the tax consequences of any transaction. All investing involves risk, including loss of principal. Past performance does not guarantee future results. No strategy ensures success or protects against loss. Further, readers should be aware that websites or sources listed in this work may have changed or disappeared between when this work was written and when it was read.
| | | | |