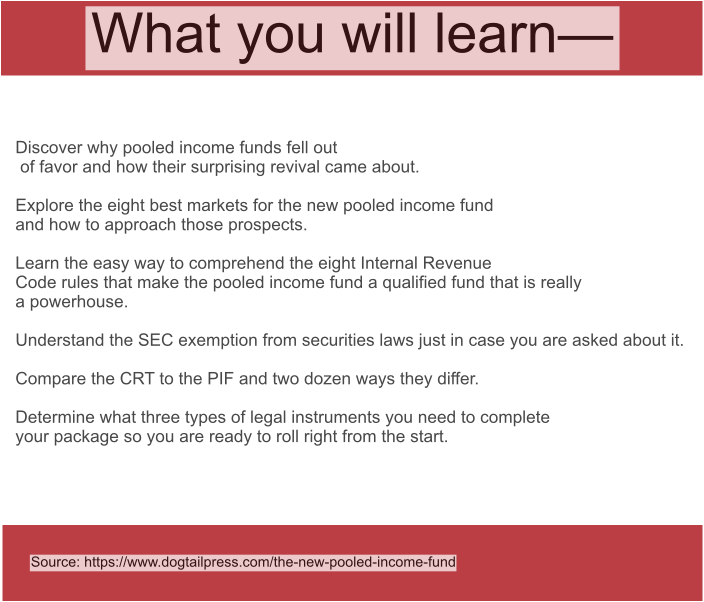
Maybe you or your organization have slept through the transformation of this highly lucrative, easy-to-operate gift vehicle. It’s not your grandmother’s Pooled Income Fund from 1969 or 1979 or 1989, or even 1999.
It has undergone a complete shift in the underlying concept of “income” and how you and your donor will share it. Your donor does not need to hire an attorney to draft a charitable remainder trust or put out big bucks to set it up. This gift vehicle is ready-made and ready to go, easy for donors to understand, and can take in gifts of $50,000 or $5,000,000!
Plus, there is no 100% confiscatory tax on UBTI as with CRTs, no minimum 10% remainder rule as for gift annuities and CRTs, and you can even use the power of adjustment to allocate earnings between income and principal. Income can be redefined to include capital gain.
This course is an on-demand video course with lots of materials provided.