Wentz Weekly | Volume 8 Issue 34 | September 8, 2026 | | |
Job Growth Strong
For August,
Markets Move Higher,
But Inflation Data Ahead
| | |
US stocks squeezed out a weekly gain, but up only slightly with the S&P 500 rising 0.09% for the fifth weekly increase of the past six. It was a fairly mixed week – energy and tech were the top performing sectors, up 2.3% and 1.1% respectively, driven by higher oil prices and solid earnings from several software and semiconductor companies. Underperformance was led by consumer discretionary and materials, down 2.1% and 1.6%, led by apparel after underwhelming earnings results from Lululemon and weakness in containers and packaging from global trade.
In the fixed income markets, Treasury yields rose through the course of the week as the situation in the Middle East showed signs of escalating again, sending oil prices higher and continuing to push inflation expectations and rate hike expectations higher.
Oil prices rose nearly 10% last week, to the highest levels since early June, most of that coming the first half of the week after the US and Iran traded airstrikes again. The US hit two Iranian launchers after Iran attempted putting more mines in the Strait of Hormuz, then struck about 100 targets after Iran attacked several commercial ships in the Strait. Things calmed later in the week with the US seeing more control of the Strait after reports said oil flows through the Strait are nearly back to pre-war levels from January.
Latest reports say President Trump has been considering whether to declare the war over, in a move to deescalate the situation in the Middle East ahead of the Midterm elections. There have been additional reports saying military action could ramp up after the election to force a deal. Media reports say Iran is expected to escalate militarily rather than negotiate as the US blockade in the Strait is hurting Iran more than Iran’s blockade is hurting the US and allies.
Upside was driven by solid earnings reports, highlighted by the sixth largest US company - chipmaker Broadcom, which reported 86% overall revenue growth and a 221% increase in AI semiconductor revenue. The company said it expects AI semiconductor revenue to double to approximately $115 billion in fiscal 2027 and again to $230 billion in fiscal 2028. Despite these extraordinary growth rates, Broadcom shares declined as investor expectations had already risen to exceptionally high levels.
The story has been quite different for software companies, where investors continue to grapple with how significantly AI could disrupt the industry and how that risk should be reflected in valuations. However, recent results suggest the disruption may be taking longer to materialize than initially feared, or that some are finding a path where AI can improve their services. Snowflake was a notable standout, with revenue increasing 35% to $1.55 billion and product revenue rising 37%, helping drive a 20% rally in the shares.
Aside from semis and software, the AI narrative remained positive after a number of model releases were announced last week, like those from OpenAI, Google, and Meta. Goldman Sachs even called one of the models breakthrough intelligence that helps revitalize the desire and necessity to spend.
The week ended with an update on the employment situation with the latest data for August. The Department of Labor reported payrolls grew 162,000 in the month, about triple the expectations and well above the prior 12-month average of 31,000. In addition, job growth in the prior two months was revised higher by 55,000, including the 23,000 loss that was initially reported in July.
The US labor market has remained in a low hire, low fire mode for much of the past two years. Part of the reason is change in immigration policy and part that Americans are staying put longer. Workers are switching jobs at the lowest rate since the years after the Financial Crisis. The separation rate from the monthly job openings and labor turnover survey has been stuck at the lowest levels in 14 years.
The separations rate includes those laid off plus those leaving their jobs voluntarily. In July, the rate fell to 3.2, the lowest since 2012. It was just four years ago the rate hit 4.4, one of the highest levels on record as people switched jobs at record pace amid a hiring frenzy.
On the other hand, the hiring rate has remained low too, likely the result of AI and less people looking for jobs. The level of hires has been trending around the lowest levels since 2014. The rate of hires is similar, in February it was 3.1, the lowest since 2010 (it ticked up to 3.2 in August).
The low hire, low fire economy has led to slower growth in wages. In August the average wage growth was 0.3%, with the 12-month increase at 3.1%, tying the lowest since the pandemic early 2020.
The stronger jobs report, combined with stubbornly high inflation, is lifting the chance for rate hikes. The implied probability of an interest rate increase at the Fed’s next meeting next week, based on futures contracts, is about 60%, rising steadily over the past month.
We see the probability about the same, but believe it will depend on the outcome of this week’s inflation data. The consumer price index is the main event this week. Released Friday morning, it is expected to show an increase of 0.4%, pushed higher from the bounce in energy prices, with the 12-month change at 3.4%.
Aside from inflation, there are many brokerage conference on the calendar, along with Apple’s product event where it is expected to unveil its new foldable phone.
| | |
Recent Economic Data
-
Employment Report: The Department of Labor reported in its monthly employment summary that August saw an increase of 162,000 payrolls in the month, well ahead of the expected 50,000 increase. In addition, the prior two months saw upward revisions – June’s payroll gains were revised up 11,000 to 31,000 while July’s 23,000 decline was revised up to a 21,000 increase. The unemployment rate remained unchanged at 4.1%. However, the labor market remains relatively subdued, with participation only edging higher and job losses continuing in the information sector, including computing infrastructure and data-processing businesses. Wage growth was 0.3% in the month and 3.1% from a year ago, matching the increase from July.
-
ADP Payrolls: ADP payroll data reported an increase of 38,000 payrolls in August, near expectations and relatively unchanged from the gain seen in July, though the lowest pace of job creation since January.
-
Job Openings and Labor Turnover Survey: The job opening and labor turnover survey report showed the number of job openings the last day of July was 7.271 million, little changed from the prior month and up about 200k from a year earlier. Job openings fell to a low of 6.5 million late 2025, but since 2024 have flattened out and remained in a tight range around 7.0 million. The number of hires fell about 280k in the month to 5.054 million, near the lowest level since the pandemic in 2020. Separations fell about 250k to 5.072 million, with the decline split between quitters and layoffs.
-
Jobless Claims: The number of jobless claims the week ended August 29 was 206,000, an increase of 2k from the prior week with the four-week average up slightly to 207,250. The number of continuing claims increased 8k to 1.779 million, with the four-week average down slightly to 1.782 million.
-
PMI Manufacturing Index: The PMI manufacturing index was 53.9 for August, matching the reading from July, indicating US manufacturing activity remained solid and firmly above the 50 level that signals expansion. New orders and output continued to increase but the pace of growth moderated. Employment improved, but companies continue to face elevated input costs, particularly for metals and electronic components, while companies continue to deal with persistent supply chain constraints.
-
ISM Manufacturing Index: The ISM manufacturing index was 54.6 for August, a two point drop from July, indicating continued growth in the manufacturing sector and still above the key 50 breakeven level. The report noted moderate growth in new orders, strong growth in production, a bounce in employment, but price pressures that intensified amid higher costs for metals, energy, and other inputs.
-
Construction Spending: Spending on construction was weak again in July, declining 0.5% in the month. The decline was driven by a 1.3% decline in residential spending, offset only somewhat by a 0.1% increase in nonresidential. Over the past year, construction spending is down 3.8%, with residential down 7.3% and nonresidential down 1.3%. The office category, which includes data centers, has driven much of the gain in nonresidential spend – rising 16.9% over the past year.
-
Trade Balance: The US trade deficit jumped in July by 24.4%, with the US seeing a deficit of $88.6 billion in the month, the widest since the trade Liberation Day 16 months ago amid increased computer/accessories/semi imports. The number of exports fell 2.1%, or $6.6 billion, to $310.7 billion, while the number of imports rose 2.8%, or $10.8 billion, to $399.3 billion. Year-to-date, the trade deficit is 29.6% lower than the same period last year, mostly due to the spike in imports ahead of tariff announcements last year.
-
ISM Services Index: The index on the ISM services survey was 55.4 for August, about one point more than expected and one point higher than from July, indicating services activity in the economy continued to increase at a moderate pace in the month. The report noted business activity and new orders both reached their highest levels in several years, while backlogs increased sharply, suggesting solid underlying demand. However, employment contracted for a second straight month, and the prices index climbed to 72.6, its highest level since August 2022.
|
|
Company News
-
Amazon: Shares of Amazon moved lower after the Federal Trade Commission (FTC) and 22 states sued the company, alleging it secretly manipulated its online advertising auctions to overcharge businesses by more than $20 billion. The core issue is that Amazon told advertisers it used a “second-price” auction, meaning the winning advertiser would generally pay just slightly more than the second-highest bid. The FTC says the practice affected roughly 1.2 million advertisers, with the higher advertising costs ultimately being passed on to consumers through higher product prices.
-
SpaceX: SpaceX said it is building an in-house foundry in Texas to manufacture specialized gas-turbine blades in effort to solve a major supply-chain bottleneck and bring natural-gas turbines online up to 18 months faster for its growing AI data-center operations. The news sent other turbine-related stocks such as GE Vernova lower.
-
Uber: Uber announced it is cutting about 10% of its workforce, or roughly 3,300 jobs, as its management seeks to make the company leaner and faster after years of rapid expansion. It said the cuts are not driven by weak demand, and are focused on management and organizational complexity, with Uber aiming to reduce overhead and redirect resources toward growth initiatives including autonomous vehicles, ride-hailing and delivery.
-
Nvidia: Nvidia announced it has agreed to acquire Hugging Face, which operates a platform for developing, sharing, and deploying open source AI models, datasets, and applications. The acquisition includes a $11.9 billion purchase price plus a $1.0 billion equity-based retention program for Hugging Face employees.
-
Google: A federal judge ordered Google to change certain ad-tech practices after finding that the company illegally maintained monopolies in parts of the digital advertising market, but rejected the Justice Department’s request to force a sale of its ad exchange. The ruling means Google avoids a major breakup of the company, avoiding what would be a worst-case scenario, while still facing restrictions on how it operates its advertising marketplace.
| | |
Other News
-
Venezuela Oil Deal: Trump announced an oil deal with Venezuela that would give the US significant control and access to 65 billion barrels of Venezuela’s oil reserves. The agreement involves a new private Venezuelan oil company, with the U.S. receiving a 35% stake and the right to purchase 20% of its oil at production cost, while the company plans to invest as much as $100 billion to rebuild Venezuela’s degraded oil infrastructure. Trump says the arrangement will boost Venezuelan production, provide cheap crude for U.S. refineries and help replenish the Strategic Petroleum Reserve.
-
Government Shutdown Averted, For Now: The House passed a stopgap bill that will keep the government funded through December 11, avoiding a government shutdown before the November Midterms. The bill goes to Trump, who said he will not sign it unless it includes new voter identification requirements. The bill will still become law after 10 days as long as Trump does not veto.
| | |
WFG News & Events
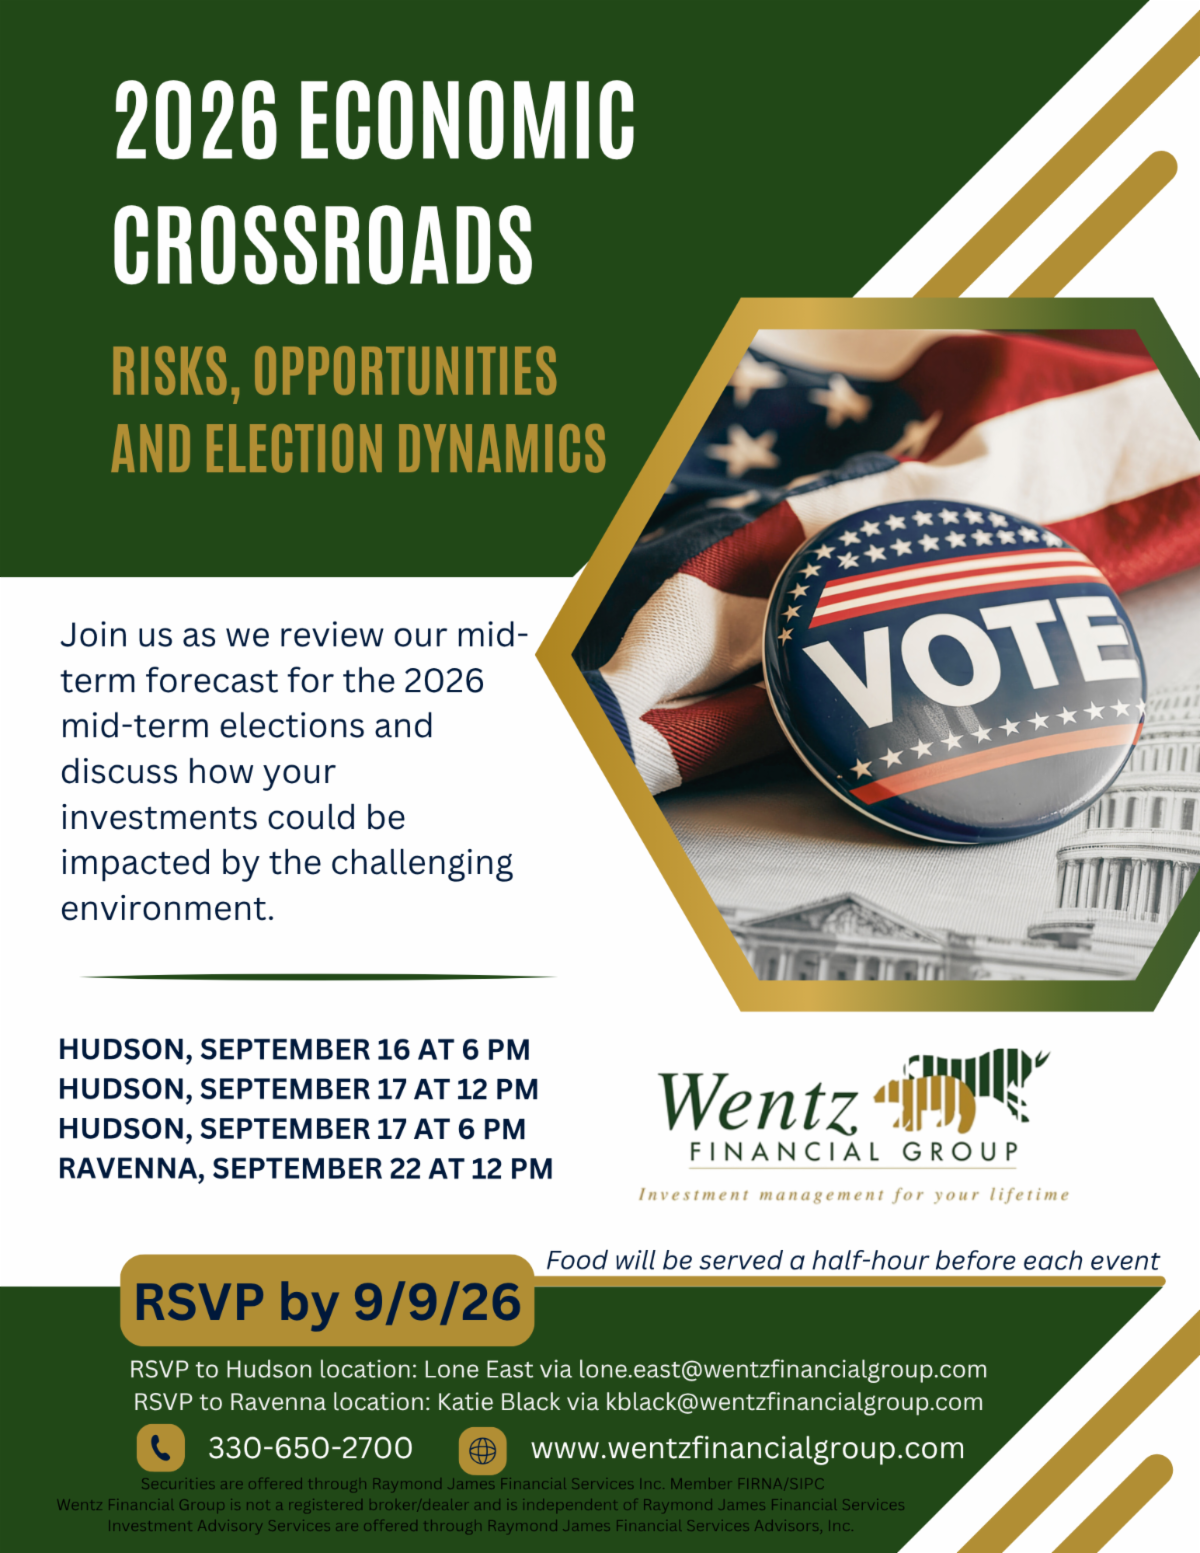
2026 Market Overview & Midterm Election Preview:
Join us for our upcoming seminar where we will review the first half of 2026 and provide our forecast for the remainder of the year, while previewing the 2026 Midterm elections. Multiple times are available, see bleow for details & RSVP today!
| | The main event this week will be the next inflation report which is released on Friday. The consumer price index for August is released in the morning and consensus expectations are looking for a 0.4% increase in the headline index, with the annual rate at 3.4% which would match July’s increase. Elsewhere, it is a lighter week of data with the only other notable reports to note include the producer price index, existing home sales, jobless claims, and consumer sentiment. The corporate calendar begins to pickup after a summer lull, mainly with brokerage conferences. This week’s conferences include those focused on healthcare, energy/power, consumer staples, communication and tech. Apple will hold its product launch, which will be the first with John Ternus as CEO, where it is expected to unveil its foldable phone. Earnings are light this week – notable companies reporting quarterly financial results include Oracle, Adobe, Kroger, Chewy, Signet Jewelers, American Eagle, and Macy’s. On the central bank side, the European Central Bank holds its policy meeting this week, while Fed policymakers begin their quiet period ahead of next week’s FOMC policy meeting. | |
| |
Information contained herein was received from sources believed to be reliable, but accuracy is not guaranteed. Information provided is general in nature and is not a complete statement of all information necessary for making an investment decision and is not a recommendation or a solicitation to buy or sell any security. Investing always involves risk and you may incur a profit or loss. Keep in mind that individuals cannot invest directly in any index. Past performance does not guarantee future results. There is no assurance these trends will continue, or forecasts will occur. Any opinions are those of Wentz Financial Group and not necessarily those of Raymond James. Expressions of opinion are as of this date and are subject to change without notice.
The S&P 500 is an unmanaged index of 500 widely held stocks that is generally considered representative of the U.S. stock market. The Dow Jones Industrial Average (DJIA), commonly known as “The Dow” is an index representing 30 stock of companies maintained and reviewed by the editors of the Wall Street Journal. The Russell 2000 Index measures the performance of the 2,000 smallest companies in the Russell 3000 Index, which represent approximately 8% of the total market capitalization of the Russell 3000 Index. The NASDAQ composite is an unmanaged index of securities traded on the NASDAQ system. Every investor's situation is unique and you should consider your investment goals, risk tolerance and time horizon before making any investment. Sector investments are companies engaged in business related to a specific sector. They are subject to fierce competition and their products and services may be subject to rapid obsolescence. There are additional risks associated with investing in an individual sector, including limited diversification. This is not a recommendation to purchase or sell the stocks of the companies pictured/mentioned.
Gold is subject to the special risks associated with investing in precious metals, including but not limited to: price may be subject to wide fluctuation; the market is relatively limited; the sources are concentrated in countries that have the potential for instability; and the market is unregulated. The LBMA Gold Price and LBMA Silver Price are the global benchmark prices for unallocated gold and silver delivered in London. SS&P GSCI Crude Oil is an index tracking changes in the spot price for crude oil. Investing in oil involves special risks, including the potential adverse effects of state and federal regulation and may not be suitable for all investors.
Prior to making an investment decision, please consult with your financial advisor about your individual situation. The prominent underlying risk of using bitcoin as a medium of exchange is that it is not authorized or regulated by any central bank. Bitcoin issuers are not registered with the SEC, and the bitcoin marketplace is currently unregulated. Bitcoin and other cryptocurrencies are a very speculative investment and involves a high degree of risk. Investors must have the financial ability, sophistication/experience and willingness to bear the risks of an investment, and a potential total loss of their investment.
| | | | |