WEL NEWSLETTER January 2025, Vol. 14, No. 10 | |
|
Dear Kenneth,
I hope and trust you had a salubrious holiday. Since we are now more than a few weeks into 2025, I want to wish you a healthy, prosperous, successful, and rewarding New Year. May your 2025 dreams and ambitions all come to fruition!
The holidays were busy. Notably, though we all say “Happy Holidays” to each other, I am here to say that the lead up to and through December with the meeting client end of year expectations, and familial commitments, shopping, wrapping, food planning, purchase and cooking, cooking, did I say cooking? and more cooking-they are in my view anything but holidays-it’s a grand misnomer! Yet, somehow, these so-called holidays are a good change of pace for sure.
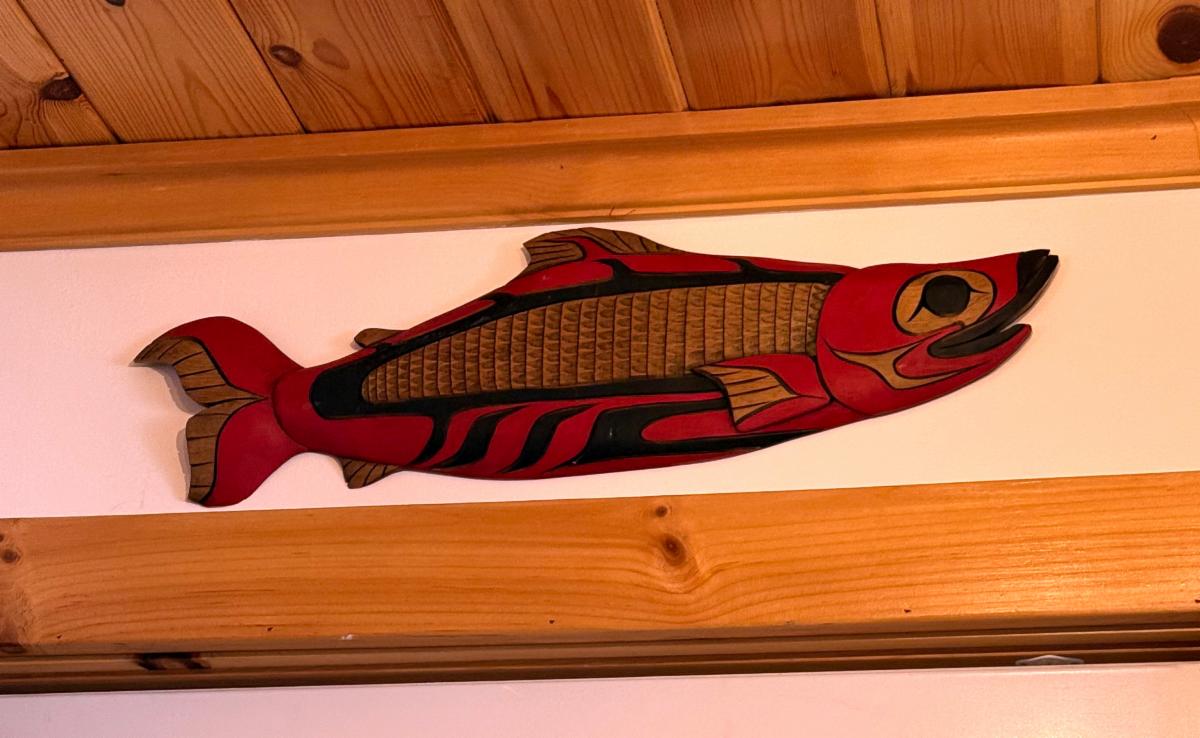
Sammi, Charlie & I headed up to the cottage on the 27th and for the third year running-it rained. A mucky, warm, dark, foggy, dreary, dog dirtying mess! I am going to Costa Rica next year, come what may. If anyone wants to join me, great, but I am categorically not sitting around waiting for it to snow! The one great thing about having visited the cottage was that I finally hung my gift from Judith Wahl over my doorway and it looks brilliant. It makes me smile and smiles are a hot commodity.
| |
|
This month as we embark on new things, and new files, and new staff, and new experiences, I continue to think about and consider how 2025 can be different and better. We are working diligently at WEL to make a difference both internally and externally.
I intend on prioritizing Kim a bit more in 2025. We will see how that goes. I hope with the efforts and ideas of our team and young energy that our firm continues to be successful and to exceed client expectations and I will continue to work on this.
I look forward to impending learning experiences and to connecting with new clients, collaborating with colleagues, and enjoying friends and family. In a new year approach to hope, I hope that everyone is healthy and happy in 2025.
For all of you asking after my mom, 9 weeks on, she has recovered like a superstar. She is rocking the cane on the stairs, kicking the heck out of the PT and determined to be better than before. I have come to expect no less from her, having now beaten 9 cancers. She is aid free as in no cane but for the stairs now. Anyway, thanks for all the well wishes.
I don’t often receive notes from colleagues like the one I will share in part below (deleting identifying words to ensure anonymity), but what a wonderful, uplifting kind note which made me smile, and warmed my heart:
“Hi Kim and happy new year! I wanted to write to you personally and thank you. You inspire me more than you know on a constant basis! Since day one of meeting you, you have been so kind to me and without knowing it, really inspired and motivated me to do more, be more, and achieve more. I have so much respect for your work and accomplishments, all while raising an incredible daughter! You represent that it IS possible for women to run a successful law firm and so much more. You are an extraordinary role model and have an impact on people of all ages. I truly appreciate you and am proud to say you influenced my journey in such a meaningful way. Thank you! Best to you in 2025!!”
My Sammi turned 26 this month. We celebrated with friends and family, had cake, and karaoke, but also her holiday and birthday gift included a trip to NYC to see some more shows: The Great Gatsby; Death Becomes Her; Maybe Happy Ending by Will Aronson, and Our Town by Thornton Wilder. Sam has not been home for her birthday in a few years because of University abroad so it was nice to celebrate with her. Its hard to believe 26 years have been enjoyed. Let’s hope there are many more. The Broadway was spectacular-my favorite was The Great Gatsby, starring Jeremy Jordan as Jay Gatsby who was spectacular. What a voice! Had some great meals including at SESAMO which was Asian-influenced Italian fusion and was delicious! Sammi is already looking for an occasion aka an excuse to return for more Broadway!!
Lastly, thank you to all of those who delivered wonderful holiday treats and gifts to our offices in December for us all to Enjoy.
As Ever,
Enjoy The Read,
Kim
| |
1. WEL PARTNERS GUEST LECTURE AT YORK UNIVERSITY, OSGOODE HALL LAW SCHOOL | On January 28, 2025, Kimberly Whaley had the privilege of providing a guest lecture at Osgood Hall Law school, on the topic of Elder Law and Predatory Marriages in Canada. Kimberly was accompanied by Jordan Atin of Hull & Hull LLP, Professor of the course and Alexander Procopoe of Perez Procope Leinveer LLP. | |
2. ONTARIO LEGAL CONFERENCE: FAMILY, ESTATES AND BUSINESS LAW | |
WEL Partners’ Nima Hojjati has the honour of presenting at the Ontario Bar Association’s Ontario Legal Conference: Family, Estates and Business Law, on February 5, 2025. Nima, alongside Hilary van de Kamer (Moderator) of Robinsons Law, Matthew Urback of Shibley Righton LLP, and Nicole Cianci of Loopstra Nixon LLP, and will discuss the topic of current trends and case law updates in Estates and Trusts Law. For more information on this conference, please visit the link below:
https://www.cbapd.org/details_en.aspx?id=on_on25olc01c
| |
|
By: Chhavi Monga
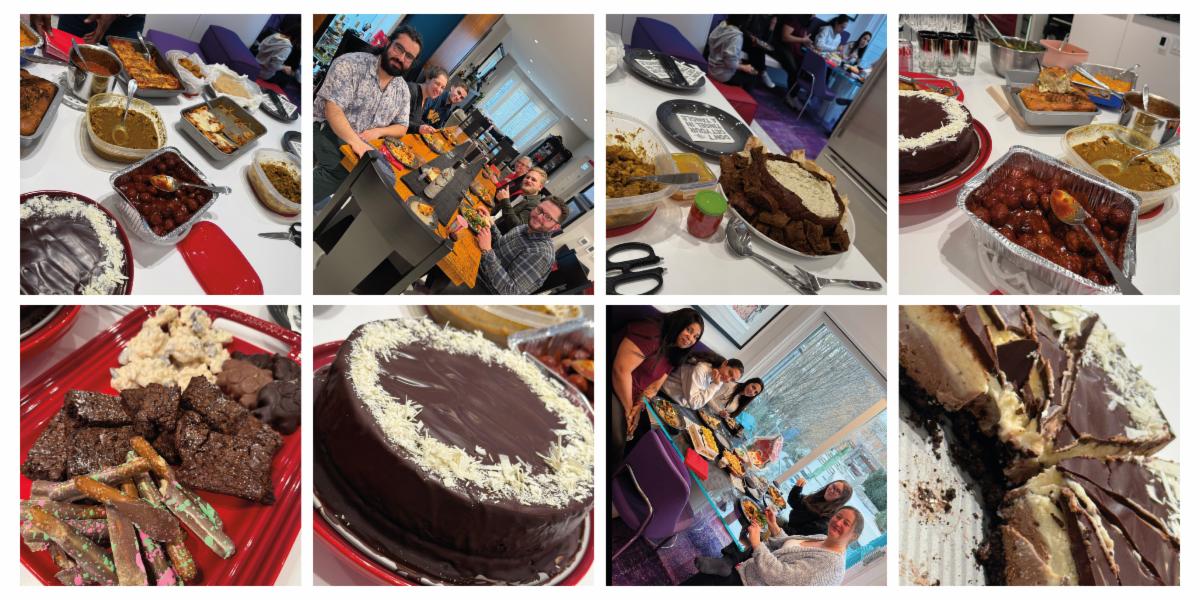
On Friday January 24, our team gathered at Kim's house for a cozy potluck, and it was a wonderful time! The table was filled with delicious food from all around the world, and some amazing desserts, each dish better than the last. However, our favourite part of the evening was Bryan and Jordan's little impromptu musical performance — it felt like our own little private concert! The evening was filled with shared stories, laughter, good vibes, and great company making the night truly special.
| |
WEL PARTNERS’ JOHN POYSER PROVIDES INSIGHT ON LITIGATION MITIGATION IN STEP ARTICLE | |
|
John Poyser TEP, and Fabiana Araujo Kennedy, provided an article on mental capacity planning tips to prevent future litigation in Canada and beyond in their article Litigation Mitigation, found in the STEP Journal: Issue 1, 2025, released January 2025. The article provides advice on avoiding the cost and stress of litigation, with a focus on contentious trusts and estates, as well as the capacity and vulnerability of clients. For more details, or to read the article, please click the link (available to members) below:
https://journal.step.org/step-journal-issue-1-2025/litigation-mitigation
| |
(i) RECOVERY OF FRAUDULENTLY OBTAINED FUNDS | |
|
By: Albert H. Oosterhoff
1. Introduction
A person obtains funds from a bank through fraudulent misrepresentation. What means are available to the bank to recover the funds, or damages? The court explored these issues in The Bank of Nova Scotia v Rosario Rosado.[1]
2. Facts
The Bank makes a line of credit available to students who are enrolled in qualifying professional study programs in which they pursue a professional designation. In 2022, the Bank advanced such a line of credit to the Defendant. In support of his application the Defendant represented to the Bank that he was enrolled in a Doctor of Dental Surgery program at the University of Toronto and provided documentation in support. All the representations and back-up documents were fraudulent and false.
By Statement of Claim, the Bank sued the Defendant for liquidated damages and fraud. It sought repayment of the credit line, an accounting and tracing order together with interest, punitive damages, a declaration that the debt arises from fraudulent misrepresentations and false pretences, and costs on a full indemnity or substantial indemnity basis.
The Bank was unable to effect personal service of the Claim and had to obtain an order for substituted service. The Defendant did not file a Statement of Defence and in September 2023 the Bank noted him in default and then brought this Motion for default judgment.
Under Rule 19.02(1)(a) of the Rules of Civil Procedure[2] a defendant who has been named in default is deemed to admit the truth of all allegations of fact made in the statement of claim. The allegations included: (1) the fact that the Defendant produced a letter from the Faculty Registrar at the Faculty of Dentistry stating that the Defendant had been offered a position in the Doctor of Dental Surgery program, and a confirmation of enrolment letter signed by the University Registrar stating that the Defendant was registered in the program; (2) that the documents were forgeries or falsified, and that the Defendant made the representations and produced the documents to the Bank knowing that they were false, with the intention that the Bank would rely on them; and (3) that Bank relied on the representations and documents, which caused the Bank to suffer losses and damages.
Rule 19.06 provides that a plaintiff is not entitled to judgment on a motion for judgment merely because the facts are deemed to be admitted, unless the deemed admission of facts and the facts adduced at the hearing entitle the plaintiff to judgment. Further, under Rule 19.05(2) a motion for judgment must be supported by evidence given by affidavit if the claim is for unliquidated damages.
The deemed facts were supported by the affidavit of a law clerk who contacted the Faculty of Dentistry and was told that while the Defendant had applied to the Faculty, he was not admitted. Moreover, correspondence from the Faculty, appended to the affidavit, confirmed that the Faculty documents submitted by the Defendant to the Bank were fraudulent. Finally, the Plaintiff submitted an affidavit of a Bank officer attaching a payout statement showing that the Defendant remains indebted to the Bank in the principal amount of the Line of Credit plus interest.
3. Analysis and Judgment
Justice Charney held that the deemed facts together with the affidavits filed in support of the motion for default judgment, are sufficient to support judgment in favour of the Bank. Accordingly, his Honour ordered the Defendant to pay the Plaintiff the amount of the funds advanced, plus pre- and post-judgment interest.
Fraudulent Misrepresentation
His Honour noted[3] that a plaintiff who asserts a claim for fraud must prove the following: (1) a false representation by the defendant; (2) some level of knowledge of the falsehood of the representation (either through knowledge or recklessness); (3) that the false representation caused the plaintiff to act; and (4) that the plaintiff suffered a loss. He went on to hold that the deemed admissions together with the affidavit evidence proved these elements. Thus, his Honour was satisfied that the Plaintiff was entitled to default judgment and to a finding that the Defendant induced the Bank to advance the funds to him through fraudulent misrepresentation.
Punitive Damages
His Honour then turned to the claim for punitive damages. The Plaintiff sought punitive damages of $200,000 because of the Defendant’s fraudulent, malicious and premeditated conduct. He noted that punitive damages are an extraordinary remedy and may be awarded only if compensatory damages are inadequate to deter the Defendant’s conduct. The amount awarded must be proportionate to the compensatory damages.[4] He concluded that in this case the Bank’s entitlement to punitive damages ‘appears well justified’, and that the perpetrated fraud meets the standard of “high-handed, malicious, arbitrary or highly reprehensible misconduct that departs to a marked degree from ordinary standards of decent behaviour”[5]. In a similar case, Bank of Nova Scotia v Anirudh Kumar,[6] the court awarded $200,000 in punitive damages and Justice Charney concluded that this amount is the appropriate and proportionate award of punitive damages in this case.
Tracing Order
On the motion the Bank seeks only an accounting order and an order preserving its right to elect between a constructive trust or other proprietary right and damages. That is because if the Bank is able to trace the proceeds into any identifiable property it will be entitled to a declaration of a constructive trust, but such a declaration cannot be made if the Bank is unable to trace the proceeds. Hence the Bank seeks an accounting order to obtain further information about how the Defendant used the funds. The court granted the order, as well as an order for disgorgement of any funds or profits found in the process, and an order that the Bank may elect in whole or in part between (1) the imposition of a constructive trust, or an equitable lien, or both, and (2) damages.
Declaration That the Debt Arises Due to Fraud
The Bank seeks this declaration because of s 178(1)(e) of the Bankruptcy and Insolvency Act (BIA’).[7] It provides that a discharge from bankruptcy releases the debtor from any pre-bankruptcy debts, except for ‘any debt or liability resulting from obtaining property or services by false pretences or fraudulent misrepresentation’. Thus, the Bank is asking for this declaration for the event that the Defendant should declare bankruptcy. However, the Plaintiff advised the court that there are divided Superior Court decisions on whether the court can make such a declaration before a defendant makes an actual assignment in bankruptcy. In one line of cases the courts have granted the declaration in these circumstances. In a second line of cases the courts have refused to grant a declaration that the debt survives a bankruptcy discharge, but are willing to declare that a debt results, inter alia, ‘from obtaining property or services by false pretences or fraudulent misrepresentation’ (using the language of s 178(1)(e)). In a third line of cases the courts have refused to grant the declaration.
Justice Charney stated that he preferred the second line of cases, but did not wish to make a ‘declaration’, because it is, by definition, ‘a statement confirming the existence of a legal right’. However, since he has made a finding of fraudulent misrepresentation, the court can rely on it in a future proceeding in which the application of s 178(1)(e) arises.
Costs
Justice Charney awarded costs on a substantial basis. Such costs are available when a party has engaged in reprehensible conduct, and the Defendant’s fraudulent conduct amount to reprehensible conduct.
---
[1] 2024 ONSC 4395.
[2] RRO 1990, Reg 194.
[3] Citing Bank of Montreal v 1886758 Ontario Inc, 2022 ONSC 4642, para 3.
[4] Citing Gennet Lumber Co v John Doe, 2019 ONSC 1345, para 54.
[5] Citing Boucher v Wal-Mart Canada Corp, 204 ONCA 419, para 59.
[6] 27 October 2022, CV-22-00682274-0000 (unreported)
[7] RSC 1985, c B-3.
| (ii) SHANNON V HRABOVSKY APPEAL | |
|
By Albert H. Oosterhoff
1. Introduction
In 2018, I wrote a blog on the proceedings at first instance in this case.[1] The judge at first instance granted the testator’s daughter’s application to set aside a will for lack of capacity and to restore an earlier will but did not give effect to the daughter’s alternative argument that the testator’s son had subjected him to undue influence. The testator’s son and his brother appealed, and the Court of Appeal dismissed their appeal.[2] Since I wrote the blog on the proceedings at first instance, it behoves me to write one on the appeal decision as well.
2. Facts
The testator died in November 2014. He had two adopted children, Gayle Shannon (‘Gayle’), the respondent in the appeal, and Glenn Hrabovsky (‘Glenn’). Glenn and the testator’s brother, Michael Hrabovsky (‘Michael’) were the respondents.
The testator made a series of wills over a period. In the 2002 Will he made a bequest of $30,000 to Michael, and equal bequests of 10% of the residue of his estate to Gayle and Glenn’s children. The Will left the remainder equally between Gayle and Glenn and named Glenn and Michael the executors. In the 2006 Will the testator increased Gayle’s share by also devising the title to his Toronto house to her. (Earlier, he had made Glenn a joint tenant with him of a cottage.) The 2006 Will also named Gayle as the third executor, and increased Michael’s bequest to $35,000. Then, in July 2007, the testator made a new will (the ‘2007 Will). It disinherited Gayle and removed her as executor. The Will increased the percentage share of the bequests to Gayle and Glenn’s children to 15% and left the balance entirely to Glenn. However, it went on to state that if Glenn predeceased the testator, the balance of the residue would pass entirely to his children, so that Gayle’s children would get nothing. The 2007 Will also stated that the testator forgave a debt owed by Gayle for money lent her that she had not repaid. And the will increased Michael’s bequest to $100,000.
In December 2016 Gayle brought an application in which she challenged the validity of the 2007 Will.
On the application the appellants filed a 2017 affidavit from Ms. Woodruff, the drafter of the testator’s wills, in which she stated that the testator did not exhibit any impairment of capacity when he made the 2007 Will.
The appellants presented two grounds of appeal:
(1) That the application judge should have found that Gayle’s application was statute-barred because it was not brought within the two-year limitation period in s 4 of the Limitations Act 2002.[3] The appellants sought to present fresh evidence in support.
(2) That the application judge failed to give sufficient weight to the evidence supporting their argument that the testator had testamentary capacity. They also sought to present fresh evidence in support of this ground.
It was established in evidence at first instance that in 2005 Gayle had used her father’s credit card to make certain purchases. Gayle mentioned that she had done so with his knowledge and permission. Ms. Woodruff sent Gayle a letter in 2005 in which she demanded repayment. However, she did not mention this letter in her 2017 affidavit. She testified that she met with the testator and received his instructions to send the letter, but she had no notes of the meeting.
In his decision, the application judge stated that while the limitation period for a will-challenge is presumed to begin on the date of the testator’s death, that presumption is subject to the discovery principle in s 5 of the Act. He held that while Gayle had the facts necessary to commence her application before the testator’s death, she did not know of the existence and contents of the 2007 Will until January 2015, when she received a copy of the will, and those were essential elements of her application. This meant that the two-year limitation period did not begin to run until January 2015 and thus her application was not statute-barred.
3. Analysis and Judgment
The Limitations Issue and Fresh Evidence
The appellants sought to introduce a new 2019 affidavit by Ms. Woodruff who drafted all of the testator’s wills. She appended a letter to the affidavit from Mr. Pease who acted for Gayle (the ‘Pease Letter’) in which he states that Gayle called Ms. Woodruff and was told that Gayle was no longer an executor under the testator’s new will. He also states in the affidavit that Gayle suspected that Glenn is the sole residuary beneficiary.
Justice Dawe quoted from St Amand v Tisi,[4] which outlines the test for admitting fresh evidence. It requires the party seeking to introduce the fresh evidence to show that it:
- Is credible;
- Could not have been obtained by reasonable diligence before trial or application; and
- If admitted, would likely be conclusive of an issue in the appeal.
His Honour held that the fresh evidence in Ms Woodruff’s 2019 affidavit bearing on the limitations issue does not meet the last two prongs of the test.
On the reasonable diligence issue, he found that the appellants could have put the Pease Letter into evidence themselves, and they failed to explain why they did not.
On the conclusive issue, his Honour noted that the Pease Letter showed that Gayle already knew in 2014 that her father had made a new will, so the statement in her 2016 affidavit that she did not become aware of that will until 2015 was incorrect. Although the application judge appears to have relied on that statement, his Honour concluded that this error did not go to ‘to the very core of the outcome of the case’, since Gayle did not learn of the contents of the 2007 Will until January 2015. Besides the degree of knowledge required to realize that one has a claim does not depend on ‘mere suspicion of speculation’. Further, Ms. Woodruff’s telephone conversation with Gayle did not disclose important information about the Will’s contents, and Gayle only decided to challenge the Will when she learnt from the Will that she was disinherited, and her children would potentially also lose their share of the estate.
The Application Judge’s Conclusion That the Testator Lacked Capacity
Justice Dawe noted that the application judge held in accordance with the authorities[5] that Gayle bore the initial burden of introducing evidence of suspicious circumstances with respect to its preparation and execution, and if she met that burden, the burden of establishing testamentary capacity would shift to the propounders of the will. He held that Gayle had met the threshold burden by reference to the following circumstances:
(1) The testator changed his Will in 2006 and increased Gayle’s share, which undermined the appellants’ theory that he was still angry with her in 2007 about the charges she had incurred on his credit card.
(2) The testator had no other known reason for disinheriting Gayle.
(3) The 2007 Will was ‘unusually spiteful’ in eliminating Gayle’s children’s share of the estate if Glenn predeceased the testator.
(4) The application judge found that there was ‘reason to doubt’ that the Demand Letter sent to Gayle in September 2005 represented the testator’s intention.
(5) The application judge accepted Gayle’s evidence that shortly after signing the 2007 Will he told her about his concern about signing a document when he was unaware of the contents.
(6) The application judge accepted the evidence that in May 2008 the testator had given Gayle the deed to his house, thinking that this would protect her entitlement to the house if any other documents he had signed, including a will, would provide otherwise.
The application judge held that the appellants had failed to meet the burden to prove capacity because: (1) medical evidence suggested that the testator suffered from dementia when he signed the 2007 Will; and (2) the overall impression based on the suspicious circumstances was that the Will was sufficiently inexplicable and out of character, so that it was more probably than not that the testator was in a confused state and therefore lacked testamentary capacity.
The appellants sought to introduce fresh evidence in the form of Ms. Woodruff’s April 2019 affidavit in which she dealt with the 2005 Demand Letter and the 2007 Will. She portrayed Gayle in a negative light and suggested that the testator never much cared for her and always preferred Glenn. Thus, the application judge found her to be highly partisan and held that her opinion evidence should not have been included.
Justice Dawe found that this fresh evidence also failed the second and third prong of the test for admitting fresh evidence.
On the reasonable diligence issue, his Honour found that the appellants failed to provide an explanation for not placing the information in Ms. Woodruff’s 2019 affidavit before the application judge.
On the conclusive issue, his Honour noted that the Demand Letter was not central to the issue, which was whether the testator had capacity. In his view there was no realistic prospect that the new evidence about the Demand Letter would have affected the result. In his reasons, the application judge gave the following reasons for holding that the testator lacked capacity when he signed the 2007 Will:
(1) The medical evidence of a geriatric specialist closely linked to the relevant events in 2007 and 2008.
(2) The conclusion that the evidence does not support the appellants’ argument that the loans to Gayle in 2005 explain the provisions of the 2007 Will.
(3) Gail’s evidence that the testator told her that he did not understand the document he signed.
(4) The fact that the appellants’ assertion that the testator remained ‘mentally sharp’ conflicted with the medical evidence.
(5) His assessment of Ms. Woodruff’s evidence about the testator’s condition when he signed the 2007 Will.
Only the fifth point might possibly be affected by the proposed fresh evidence. However, the application judge’s concern about Ms. Woodruff’s failure to make any contemporaneous notes about the testator’s condition would be unaffected by the fresh evidence.
Thus, Justice Dawe concluded that based on the application judge’s reasons as a whole, there was no ‘realistic possibility that he would have found that the appellants had met their burden of establishing’ that the testator had capacity when he signed the 2007 Will.
Justice Dawe went on to dismiss the appellants’ second ground of appeal, holding that, in essence they sought to retry the case.
Hence, he dismissed the appellants’ motion to adduce fresh evidence and their appeal from the application judge’s order.
4. Costs Endorsement
The court delivered additional reasons in a Costs Endorsement.[6] It held that, as the successful party, the respondent is entitled to her costs of the appeal, as well as the costs on an unsuccessful mediation. She sought $83,620 for fees plus disbursements on a substantial indemnity basis, while the appellants sought more than $150,000 in fees and disbursements on a partial indemnity basis. Thus, they could not object that the amount claimed by the respondent is contrary to their expectations of what would be fair and reasonable in the circumstances. The court held that this was an appropriate case for awarding enhanced costs because the appellants made serious allegations of misconduct against the respondent. They accused her of giving ‘false and deceitful evidence’ and the court refused to accept that characterization. It held that litigants who make unsubstantiated allegations of misconduct or dishonesty can expect to pay enhanced costs.
The court held further that this was an appropriate case to order the appellants to pay the costs personally, rather than awarding costs out of the estate. The appellants stood to benefit under the 2007 Will, whereas the respondent was the largest beneficiary under the 2006 Will. Besides, in the court’s view the appeal was entirely without merit and was brought primarily for their own benefit rather than for the benefit of the estate.
However, the court noted that costs on a substantial indemnity scale should be determined by applying a factor of 1.5 to the amount of partial indemnity costs. Consequently, the court held that it was appropriate in this case to estimate substantial indemnity costs at 80% of full indemnity cost, and therefore it fixed the respondent’s costs at $80,000 all inclusive.
---
[1] Shannon v Hrabovsky, 2018 ONSC 6593. See http://welpartners.com/blog/2018/11/there-is-no-presumption-of-undue-influence-in-probate/
[2] Shannon v Hrabovsky, 2024 ONCA 120. J Daw JA wrote the reasons for the panel. LB Roberts and Sossin JJA concurred.
[3] SO 2002, c 24, Sched B.
[4] 2018 ONCA 106, para 8.
[5] Vout v Hay, [1995] 2 SCR 876, and Scott v Cousins (2001), 37 ETR 2d 113 (Ont SC).
[6] Shannon v Hrabovsky, 2024 ONCA 188.
| |
(iii) IS THE SHARE OF A CO-OPERATIVE HELD BY AN ESTATE SUBJECT TO TENANCY IN COMMON AND THEREFORE THE PRESUMPTION OF RESULTING TRUST? | |
|
By Gabriella Banhara
In Gruber v. Glickman Estate et al., 2025 ONSC 258[1] (“Gruber”), a couple, Anne and Jacob, jointly purchased during lifetime a share in a Co-operative Housing Corporation (the “Share”). Following each spouses passing, the estate trustee of Anne’s Estate (“Anne’s Estate”) brought forward a motion to determine whether the Share was held by the couple through joint tenancy or tenancy in common, and if so, was the Share subject to the presumption of resulting trust as outlined by s.14 in the Family law Act (“FLA”).
The court determined that the Share was owned by the couple jointly, and therefore joint tenancy applied. [2]
Background:
The Share:
Title to the Co-operative Housing Corporation, was not held directly through land title, but rather, by way of shares. The Share certificate set out the registered owners of the Share as both “Anne and Jacob”. The interest in the Share was not defined as jointly held between Jacob or Anne, or whether they were each entitled to a 50% interest.[3]
Anne’s Will and the Question for the Court:
Anne and Jacob were married for several decades but lived apart towards the end of their lives. Anne passed away on December 21, 2021, and Jacob passed away shortly after, on June 10, 2022. Anne’s Last Will and Testament (“Will”) provided Jacob with her interest in the Share, as well as bequests to 28 other family members and friends. This did not provide ample residue from the Anne’s Estate to pay her taxes and liabilities, particularly from the tax that arose from Anne’s rental properties. For this reason, Anne’s Estate sought to determine whether her Estate was fully entitled to the full interest of the Share.
Jacob’s Estate Trustee (“Jacob’s Estate”) was of the position that Anne’s Estate should transfer Anne’s interest in the Share to Jacob Estate.
The Issue:
The Family Law Act:
Jacob’s Estate asserted that s. 14(a) of the FLA settled the issue of ownership regarding the Share[4]. S. 14 out of the FLA states the following:
14 The rule of law applying a presumption of a resulting trust shall be applied in questions of the ownership of property between spouses, as if they were not married, except that,
(a) the fact that property is held in the name of spouses as joint tenants is proof, in the absence of evidence to the contrary, that the spouses are intended to own the property as joint tenants;
It is stated within s.14 of the FLA, that the presumption of resulting trust applies to married spouses, unless the property is held in joint tenancy. The court citing McManus v. Argiro[5], states that if it is unclear whether property is held in joint tenancy, “intention must be inferred from the circumstances”.[6] The Court went on to note that when determining joint tenancy, intention at the time of purchase must be considered.
Jacob’s Estate points to circumstantial evidence, including Anne’s intention to leave Jacob with the Share upon her death, despite not clarifying the percentage of ownership to be given to Jacob. Additionally, Jacob’s Estate notes that during her lifetime, Anne did not go through the efforts of altering or severing the Joint tenancy. On this basis, Jacob’s estate contended that the Share would pass to the surviving spouse unless the is evidence of any “contrary intention”. [7]
Anne’s Estate submitted that s.14 of the FLA may not be applicable as “the presumption of joint tenancy applies only to property where title is registered to spouses as joint tenants”.[8] Since the ownership of the Share did not specify the legal arrangement, Anne’s Estate asserted that s.14 does not entitle Jacob’s Estate to the entirety of the Share.
Equity:
The court then analysed the principles set out in Hardy v. Estate of Louise Winters Hardy[9], stating that equity will favour tenancy in common when two or more people purchase property without detailing how interest in title will be shared. The court stated the following:
[21] It is well established that the Courts of Equity did not favour joint tenancy; e.g ., because the entire property subject to such a joint tenancy at common law would belong to the survivor, and the representatives of the deceased would receive nothing. Such an outcome was not viewed as fair or "equitable", except - possibly - from the standpoint of pure chance determining which owner would take by right of survivorship.[10]
This was interpreted into legislation through s. 13(1) of the Conveyancing and Law of Property Act (“CPLA”), which asserts the following[11]:
13 (1) Where by any letters patent, assurance or will, made and executed after the 1st day of July, 1834, land has been or is granted, conveyed or devised to two or more persons, other than executors or trustees, in fee simple or for any less estate, it shall be considered that such persons took or take as tenants in common and not as joint tenants, unless an intention sufficiently appears on the face of the letters patent, assurance or will, that they are to take as joint tenants. R.S.O. 1990, c. C.34, s. 13 (1).
Importantly, the CPLA only deals with real property, meanwhile the Co-operative Corporations Act (“CCA”) asserts that shares of a co-operative are personal property.
Anne’s Estate asserted that the Share should be viewed as Land for the purpose of the CLPA, and therefore the presumption of tenancy in common would apply. The decision of Regina v. Labelle supports this assertion stating rights arising out of land are the same thing as Land (I.e. labelled in the decision as corporeal hereditaments). For this reason, Anne’s Estate submitted that “the rights arising from the land would include Anne and Jacob’s interest in the Share” because the agreement they signed provided them “rights to occupy the land owned by the Corporation”.[12]
Analysis:
The Court asserted that they could not expand the definition of land under the CPLA, to include shares in a co-operative housing unit, and therefore tenancy in common does not apply.[13]
The first reason being that the CCA defines shares in a co-operative as personal property. The second reason being those statutes in Ontario, such as the CPLA and the Ontario Business Corporations Act does not contemplate that a shareholding interest to a corporeal hereditament (rights arising out of Land) actually attaches to land.[14]
Instead, the court found that the presumption of the joint tenancy, found at common law applied, and therefore the Share was owned jointly between Anne and Jacob. On this basis, s.14 of the FLA applied. The court found that the presumption of resulting trust was rebutted given there was no evidence that the Share certificate indicated a division of interest, Anne’s Will bequeathed “all of her interest” in the share to Jacob, the spouses were not divorced, there was no evidence that Anne or Jacob contributed differently to the purchase price.[15]
For this reason, the entirety of the interest in the Share devolved to Jacob’s Estate since Jacob owned the Share in Joint Tenancy with Anne.
---
[1] Gruber v. Glickman Estate et al., 2025 ONSC 258 (Gruber)
[2] Ibid at para 3.
[3] Ibid at para 7.
[4] Ibid at para 14.
[5] McManus v. Argiro, 2021 ONSC 6385 at para 12
[6] Gruber at para 16.
[7] Ibid at para 17.
[8] Ibid at para 19.
[9] Hardy v. Estate of Louise Winters Hardy, 2022 ONSC 1966
[10] Ibid at para 21.
[11] Ibid at para 22.
[12] Ibid at para 27.
[13] Ibid at para 31.
[14] Ibid at para 31.
[15] Ibid at para 33.
| |
(iv) TESSARO V. GORA, ONTARIO SUPERIOR COURT CONFIRMS 15-YEAR LIMITATION PERIOD APPLIES FROM DATE OF NEGLIGENT WILL DRAFTING | |
|
By Oliver O’Brien
In the recent decision of Tessaro v. Gora (“Tessaro”),[1] Justice Myers provided clarity on the interpretation and applicability of the ultimate 15-year limitation period to claims made against negligent Will drafting lawyers.
Facts
In Tessaro, Leopold Rcyzkowksi (“Mr. Ryczkowski”) passed away on July 16, 2018. Mr. Ryczkowski had three sisters, Virginia Boyle (who is still alive), Irene Sedgewick (who survived Mr. Ryczkowski but has since passed away) and Monica Marzec (who predeceased Mr. Ryczkowski). Monica Marzec had two daughters, Kim Marzed and Lynn Tessaro.[2]
In 1991, Mr. Ryczkowski retained estate lawyer John Leonard Zigmund Gora (the “Defendant”). On November 6, 1991, Mr. Ryczkowski executed a Will prepared by the Defendant (the “Impugned Will”). Justice Myers singled out one provision in the Impugned Will which states:
To such of my sisters living at the time of my death, I give whatever real estate that I own or that may be in my possession at the time of my death, in equal shares per stirpes.[3]
The first underlined phrase appears to suggest that only Mr. Ryczkowski’s two sisters who survived him will receive a share in his real estate. However, the second underlined phrase “in equal shares per stirpes” suggests that Mr. Ryczkowski’s predeceased sister having a share that is then available to her daughters equally.[4]
Accordingly, this and other paragraphs in the Impugned Will create an ambiguity as to whether Mr. Ryczkowski’s two surviving sisters alone each take 50% of his real estate or whether it divides the real estate into thirds, with the share of the deceased’s sisters Monica Marzec being shared between two daughters.[5]
In 2020, two separate actions were brought against the Defendant by Mr. Ryczkowski’s sisters and his nieces, for negligent drafting of the Impugned Willm alleging that they received less than Mr. Ryczkowski intended for them to receive.[6]
Issue
The central issue in Tessaro was whether the Plaintiffs were statute barred from bringing their claim against the Defendant. The relevant limitation period being section 15 of the Limitations Act, 2002[7] which provides as follows:
Ultimate limitation periods
15 (1) Even if the limitation period established by any other section of this Act in respect of a claim has not expired, no proceeding shall be commenced in respect of the claim after the expiry of a limitation period established by this section. 2002, c. 24, Sched. B, s. 15 (1).
General
(2) No proceeding shall be commenced in respect of any claim after the 15th anniversary of the day on which the act or omission on which the claim is based took place. [emphasis added]
To address the issue in Tessaro, Justice Myers was required to interpret the meaning of “act of omission on which the claim is based” in section 15 of the Limitations Act, 2002. The answer to this question was necessary to determine whether the Plaintiffs were statute barred from bringing their claim for negligence or not.[8]
The Defendant argued that the 15-year limitation period began when the Impugned Will was drafted, namely November 6, 1991, and therefore the Plaintiffs were statute barred from bringing their claim. The Plaintiffs, meanwhile, argued that since a Will speaks from death, the limitation period began to run on Mr. Ryczkowski’s passing, which was July 16, 2018, and therefore they were within their rights to bring their claim.[9]
Justice Myers provides an in-depth analysis of the purpose of the Limitations Act, 2002, which was enacted as part of a reform of limitations law in response to the common law’s broad adoption of the “discoverability principle” as the driver of the commencement of limitation periods. The issue identified by the legislature was that the rule could effectively extend indefinitely the period for which potential defendants remain at risk of being sued. As highlighted by Chief Justice Strathy in Levesque v. Crampton Estate,[10] main point of limitations statutes from a public policy perspective is to avoid the risk of indeterminate liability.[11]
In Tessaro, liability was claimed based on the Defendant’s poor drafting of the Impugned Will. Using the modern principles of statutory interpretation, Justice Myers could not find that the “act or omission on which liability is based” began on Mr. Ryczkowski’s date of death, given he died more than 25 years after the Defendant last dealt with the Impugned Will.[12]
Justice Myers also noted that there is no omission in this case. An “omission” in tort law refers to an act not done when a person is under a duty to act. Omissions are actionable where the defendant had a duty to act and failed to do so. An omission does not refer to the quality of an act but, rather, to a failure to act when one was duty-bound to act.[13]
Decision
Accordingly, Justice Myers found that the Plaintiffs were statute barred from bringing their claim on the basis that the limitation period arose from the date of the drafting of the Impugned Will, not Mr. Ryczkowski’s date of death.
Justice Myers noted the importance that the law places on the ability of beneficiaries to sue lawyers for negligently drafting wills. Doing so properly holds lawyers to account and protects the integrity of the legal system of inheritance and succession. Generally speaking, people are entitled to rely on wills to carry out the intentions of their deceased parents, relatives, or benefactors. People may have waited their whole lives for an inheritance. They should not be disappointed by actionable negligence of a lawyer.[14]
The Plaintiffs submitted that if the 15-year limitation period applies, people who do the responsible thing and obtain a will while young will be penalized. The Defendant, by contrast, argued that perhaps wills lawyers should be counselling people to check their wills at least every 15 years. Ultimately, while recognizing the perceived unfairness with the result, Justice Myers noted that the main role of the court is to interpret legislation. Moreover, that the act of creating exceptions to the ultimate limitation period due to perceived unfairness is the role appropriately governed by Legislature, not the judiciary.[15]
Concluding Comments
The decision in Tessaro is informative to estate planning lawyers, litigators and beneficiaries as to the relevant limitation period that applies to claims brought against lawyers for negligently drafted wills.
---
[1] Tessaro v. Gora, 2024 ONSC 198 (“Tessaro”).
[2] Tessaro at paras 11 – 16.
[3] Tessaro at para 19.
[4] Tessaro at para 20.
[5] Tessaro at para 21.
[6] Tessaro at paras 23 and 24.
[7] Limitations Act, 2002, S.O. 2002, c. 24, Sched. B
[8] Tessaro at paras 30 – 32.
[9] Tessaro at para 31.
[10] 2017 ONCA 455 (CanLII)
[11] Tessaro at paras 42 – 55.
[12] Tessaro at para 59.
[13] Tessaro at para 60.
[14] Tessaro at para 94.
[15] Tessaro at paras 95 and 96.
| |
(v) CONSIDERATIONS IN THE DRAFTING OF TESTAMENTARY SPOUSAL TRUSTS | |
|
By Irit Gertzbein
WEL Partners works in association with Irit Gertzbein, LLB, TEP, to provide our clients, our referrals, and our team drafting, administration, and planning services. Irit hosts her practice at Gertzbein Law. Learn more: https://welpartners.com/gertzbeinlaw
In celebration of the New Year with all the positive energy and optimism it brings, this article is dedicated to honouring due diligence and best practice in drafting.
Historical Roots
The concept of a trust structure to “keep safe” property for the benefit of someone else is as old as ancient civilization. Property owners in biblical, ancient Greek and Roman times faced dangers which warranted relinquishing control and management of their property to a trusted person, the fiduciary, to safeguard, care and hold it in trust for the benefit of the intended beneficiary. In the Middle Ages, feudal landlords, the settlors of the trust structure, conveyed property to a trusted a friend to hold and care for that property to the benefit of the settlor or a third-party beneficiary, upon certain terms of management and distribution. A body of law evolved in England’s Courts of Equity protecting the settlor and the intended beneficiary from a dishonest trustee, advancing the English doctrine of trusts.
Fast forward to modern-day: The foundational purposes and principles embedded in the trust construct of ancient times remain the same. Technically, the trust structure arises upon the separation between the legal and the beneficial interests (bundles of rights) vis-a-vis property, with the three certainties – intention to settle a trust, description of the property, identification of the beneficiaries, clearly expressed. Not unexpectedly, tweaks and nuances have developed in the law of trusts addressing new social circumstances. Inter-vivos trusts, created during lifetime, and testamentary trusts, created as a result of death, are two distinct categories of trusts. However, they are both creatures of the Canada Income Tax Act (the “ITA”). This article focuses on the second category, the testamentary trust, and particularly, the testamentary trust created in a Will in favour of a survivor spouse only, during his or her lifetime (the “Spousal Trust”).
The Generic Testamentary Spousal Trust
At first blush, the gifting via a Spousal Trust by the first-to-die spouse to the survivor spouse, whether the gift is any or all of a residence, rental real estate, business interest or corporate shares, or non-registered investment accounts, appears to be an attractive strategy. Ideally, it is a gift which provides all that the survivor spouse may need or want during his or her lifetime - incapacity planning for the survivor spouse, protection of the assets from creditors, deferral of capital gains tax at the first death, elimination of the 21-year deemed disposition tax liability, provision of gifts to next generations, and reduction or elimination of probate tax at the survivor spouse’s death. The Spousal Trust structure seems to address all the important estate planning needs, concerns and goals spouses may have.
But as always, the devil is in the details and the details are in the drafting.
The Nature of the Gift
Unlike an outright testamentary gift which is delivered in one event, the Spousal Trust is a testamentary structure spanning the lifetime of the survivor spouse that requires lifelong attention and management.
As stated earlier, it is the splicing of legal from beneficial interests in the property, undertaken by the testator, that creates the Spousal Trust. This trust, for the benefit of the survivor spouse, who holds the beneficial interest, is to be managed and controlled by the trustee, who holds the legal interest. Consequently, the survivor spouse, unless he or she is the trustee of his or her own Spousal Trust, is not in control of the decision making with respect to the management, investment, generation of income, or distributions. Without proper legal advice, this outcome may be contrary to the survivor spouse’s expectations. Depending on circumstances, the survivor spouse may have cause to challenge the limitations of the gift as drafted, and may file a Spousal Election.
Why embark upon an estate planning endeavour which is clearly prone to challenge? Because embedded in the bundle of benefits of the Spousal Trust (creditor protection, preservation of capital, tax deferral), is a tax deferral, also known as the spousal rollover, the most sought-after benefit of the Spousal Trust.
For the Spousal Trust to be eligible for the ITA’s tax deferral, the following requirements must be met (the “ITA Requirements”):
1. The Spousal Trust must be created pursuant to the Will of the first-to-die spouse, at his or her death.
2. The survivor spouse must be i) entitled to receive all of the net income generated in the Spousal Trust, annually, during his or her lifetime, and must ii) receive all said net income, annually, subject to a written request to the trustee stating otherwise, as discussed below, under Tainted Spousal Trust section. Only the survivor spouse may receive any of the income from the Spousal Trust.
3. Only the survivor spouse may receive distribution of any of the capital of the Spousal Trust during his or her lifetime. No one else may receive distribution of any of the capital from the Spousal Trust while the survivor spouse is alive.
4. The property intended to comprise the Spousal Trust must “vest indefeasibly” in the Spousal Trust within 36 months of the testator’s death and before the death of the survivor spouse. Property vests indefeasibly when the survivor spouse acquires the absolute and unconditional legal or beneficial right to the property, such that no future event can deny him or her of that right. See discussion below under Obstacles to Indefeasible Vesting section.
5. The deceased testator must be a Canadian resident immediately before death and the Spousal Trust must be a Canadian resident trust immediately after indefeasible vesting.
If all of the above ITA Requirements are met, the Spousal Trust is settled at the adjusted cost base instead of the fair market value[1] and the capital gains tax ordinarily payable is deferred. This tax liability will be crystalized at future actual or deemed disposition of the assets.
The Principal Residence Exemption, the 21-Year-Rule and other Tax Benefits
The 2016 changes in the ITA have eliminated the availability of the principal residence exemption with respect to a residence held in a personal trust. However, there are a few important exceptions, one of which is where a Spousal Trust holds a residence. This exception makes the use of the Spousal Trust an effective planning strategy, whether in the context of an intact or a blended family, since the availability of the principal residence exemption, notwithstanding the 2016 changes in the ITA, is not lost.
The inapplicability to Spousal Trusts of the 21-year deemed disposition rule, which applies to most other trusts, is an additional tax advantage which makes the Spousal Trust an attractive long-term planning strategy.
Additionally, depending on circumstances, income generated in the Spousal Trust and distributed annually will be taxed in the hands of the survivor spouse at his or her marginal tax rate, and not in the Spousal Trust at the highest tax rate. Capital property of the Spousal Trust with embedded gain can be distributed to the survivor spouse at the cost base, therefore such tax liability is again deferred. So long as the survivor spouse is a Canadian resident and the Spousal Trust has not been tainted (see discussion below), the Spousal Trust incurs no tax liability upon income and capital distributions during the survivor spouse’s lifetime.
Obstacles to Indefeasible Vesting
Indefeasible vesting is one of the ITA Requirements for the creation of a Spousal Trust with eligibility for the spousal rollover.
A temporary obstacle to indefeasible vesting is the survivorship clause, requiring the spouse to survive the testator by a prescribed period of time (e.g. 30, 60 or 90 days)[2]. While this clause plays an important role in probate planning it also delays indefeasible vesting of the deceased’s property in the Spousal Trust, until the expiry of the specified time period.
If improperly drafted, the survivorship clause may not only be an obstacle to indefeasible vesting but it may also inadvertently interfere with the survivor spouse’s entitlements. The survivorship clause by virtue of the drafting prohibits all access to and use, occupation, enjoyment of, by the survivor spouse, to his or her home, bed, household contents, declared dividends on shares and other estate assets. These assets are intended to comprise the Spousal Trust but due to the survivorship clause they are not yet available to the survivor spouse’s benefit. To counteract this feature of the survivorship clause, best practice is to draft a “notwithstanding” paragraph which accompanies the survivorship clause, enabling access and use of by the survivor spouse, to all property intended to comprise the Spousal Trust, during the survivorship time-period.
Likewise, a direction in the Will which authorizes the executor to exercise discretion in determining which assets will comprise the Spousal Trust as discussed below in the context of planning for an intact family (“… as my Trustees shall select and allocate…”), delays the indefeasible vesting until such time as the executor completes the selection and allocation. If the executor’s exercise of discretion with respect to selection and allocation extends beyond the 36 months following date of death, indefeasible vesting will not have occurred within the ITA’s required timeline and the Spousal Trust will be ineligible for the spousal rollover[3].
Spousal Trust in the Context of an Intact Family
Intact families with high net worth - where corporate interests carry the bulk of the family’s wealth and typically, the bulk of the accrued capital gains - commonly utilize a particular succession strategy in the creation and management of the Spousal Trust. This strategy is both tax-driven and Family Law Act sensitive. To achieve maximum tax benefits and to minimize or even eliminate the risk of a challenge to the creation of the Spousal Trust, the testator shifts the decision making to the executor as to which assets of the estate will comprise the Spousal Trust.
To give effect to this strategy, the testator directs in the Will that the executor, who at the time of the testator’s death should have knowledge of the tax status of the various estate assets, shall settle a Spousal Trust with a prescribed amount, say $1.00. The settlement of the Spousal Trust is to be followed by the selection and allocation by the executor, at his or her discretion, of the specific assets to be transferred to the Spousal Trust. The intention is that the executor will select and allocate to the Spousal Trust, which had been created with $1.00, the assets with the greatest embedded capital gain. Therefore, the tax deferral will apply to most or all of the estate’s tax liability. Further to this step, the testator then directs the executor to settle a discretionary family trust with any of the remaining assets not yet allocated to the Spousal Trust, and typically, those assets which do not carry a significant tax liability. The discretionary family trust is created for the benefit of the survivor spouse and the common descendants of the spouses. The goals in using the strategy involving a Spousal Trust in conjunction with a family trust are to take advantage of the spousal rollover, and to ensure creditor protection for all estate assets while providing for all family members. This will promote family harmony and minimize the risk of dispute or litigation.
Spousal Trust in the Context of a Blended Family
Commonly, the testator in a blended family wishes to provide income and perhaps some capital for the survivor spouse, while maintaining some or most of the capital for the remaindermen beneficiaries, such as the testator’s children from a previous relationship. The testator achieves this goal by disallowing whole capital distribution providing for restricted, capped, capital encroachment in favour of the survivor spouse during his or her lifetime. This ensures preservation of capital cross-generationally.
To maximize the benefit of a Spousal Trust as a tool to protect assets from creditors of the survivor spouse, the survivor spouse should not be the appointed trustee. Creditors will then be unable to successfully argue that the survivor spouse is in control of the assets. In the context of a blended family where the survivor spouse and the remaindermen beneficiaries necessarily have adverse interests, the testator’s choice of the executor and trustee is often a source of contention and warrants careful discussion with the drafting lawyer.
To minimize the risk of the survivor spouse challenging the Spousal Trust, it is prudent to ensure that the drafting in the Spousal Trust includes an ousting of the even hand rule. It is also recommended to include trust language such as: “In connection with the foregoing authority to encroach on capital, I direct my Trustees to give primary consideration to the welfare of my Spouse and to ensuring that my Spouse continues to enjoy the same standard of living following my death as my Spouse enjoyed at the time of my death.”
The Spousal Trust in the blended family context enables the testator to provide for the lifetime financial needs of the survivor spouse, usually by way of unlimited access to income and limited access to capital. Upon the death of the survivor spouse, the remaindermen beneficiaries receive the balance of assets remaining in the Spousal Trust.
Tainted Spousal Trust
A Spousal Trust can be tainted by certain acts of the trustee or the language drafted in the Spousal Trust which are contrary to the ITA Requirements. A tainted Spousal Trust is ineligible for the spousal rollover or, if the tainting occurs some time after the establishment of the Spousal Trust, all previously deferred tax will immediately become payable. Some examples of such acts or drafting are:
1. Providing a loan to anyone other than the survivor spouse using Spousal Trust capital at a rate which is less than a commercial rate of interest;
2. Purchasing of a Life Insurance Policy with Spousal Trust capital on the life of the survivor spouse;
3. Limiting the distribution of income to the survivor spouse, thereby recapitalizing the Spousal Trust[4];
4. Drafting an expanded definition of the Division Date[5] of the Spousal Trust to include cohabitation or marriage of the survivor spouse as triggering events;
5. Paying of financial obligations which are not testamentary debts[6] by the trustee, using Spousal Trust income or capital.
In essence, the outcome of any one of the above acts or drafting errors (among others), is that Spousal Trust funds, whether income or capital, flow to a person other than the survivor spouse, while the survivor spouse is alive. If that occurs or if pursuant to the drafting it is possible, the Spousal Trust is tainted.
It is sometimes possible to untaint a tainted Spousal Trust by implementing a series of steps as prescribed by the ITA[7], such that the tainted Spousal Trust may regain its eligibility to the advantageous tax status.
Conclusion
There are many benefits to the use of a Spousal Trust in a family’s comprehensive, long-term estate planning, whether the family is intact or blended. The overarching goals when drafting a Spousal Trust are to avoid tainting of the Spousal Trust and to minimize the risk of litigation. The benefits of the Spousal Trust can be obtained with thoughtful planning and sophisticated drafting.
Happy New Year and to excellent drafting.
---
[1] ITA section 70(6)
[2] Where spouses die within a short time span of each other, the survivorship clause avoids duplicating the probate process and paying of probate tax on the same estate twice.
[3] Subject to an application to CRA for an extension, by the executor.
[4] A written request by the survivor spouse to the trustee disclaiming a portion (or all) of the net income in any taxation year will not taint the Spousal Trust, so long as the request is initiated by the survivor spouse and the survivor spouse can enforce payment of said disclaimed income any time before his or her death.
[5] Division Date marks the termination of the Spousal Trust at which time the remaining balance of the capital is distributed to the remaindermen beneficiaries.
[6] Testamentary debts include funeral expenses, deceased spouse’s tax owing to CRA, any outstanding debts of the deceased testator which existed at date of death, probate tax, and trustee compensation.
[7] ITA section 70(7).
| |
|
Osgoode Hall Law School Guest Lecture
Elder Law
January 28, 2025
Speakers: Kimberly Whaley, Jordin Atin and Alex Procope
Ontario Bar Association
Ontario Legal Conference: Family, Estates and Business Law
February 5, 2025
Speaking: Nima Hojjati
https://www.cbapd.org/details_en.aspx?id=ON_ON25OLC01C
Elder Law Newfoundland
February 10, 2025
Kimberly Whaley on Elder Law -Misuses & Abuses of POAS and Capacity to Instruct & Retain Counsel
Speaker: Kimberly Whaley
STEP Global Congress, Rome
February 25 - 26, 2025
Attending: Kimberly Whaley
https://congress.step.org/
STEP Bahamas
March 12 - 15, 2025
Capacity Issues
Speaking: Kimberly Waley
https://stepbahamasconference.com/
Osgoode Law School Guest Lecture
Predatory Marriage and Capacity to Marry
March 22, 2025
Speaking: Kimberly Whaley
LESA
April 12, 2025
Jointly Held Assets
Speakers: Kimberly Whaley, Nancy Lynn Golding KC, Helen R. Ward KC, Jennifer R. Lamb, Les Scholly
https://www.lesaonline.org/program/lesas-refresher-2025-wills-and-estates-victoria/
Osgoode Passing of Accounts & Fiduciary Accounting
April 15, 2025
Chair: Kimberly Whaley
Speakers: Albert Oosterhoff & Tracey Phinnemore
Cambridge Forum on Estate Planning & Litigation
April 27-29, 2025
Attending: Kimberly Whaley
https://www.cambridgeforums.com/forums/eplf/
Osgoode Powers of Attorney and Guardianship
April 29, 2025
Speaking: Kimberly Whaley
TIAETL – Greece
May 18 - 22, 2025
Speaking: Kimberly Whaley
University of Toronto: Medical Experts Course
The Role of the Medical Expert in Estate Litigation
September 11-12, 2025
Speaking: Kimberly Whaley, Bryan Gilmartin
| |
V. IN CASE YOU MISSED IT - RECENT BLOG POSTS | |
WEL NEWSLETTER January 2025, Vol. 14, No. 10 | | | | |