|
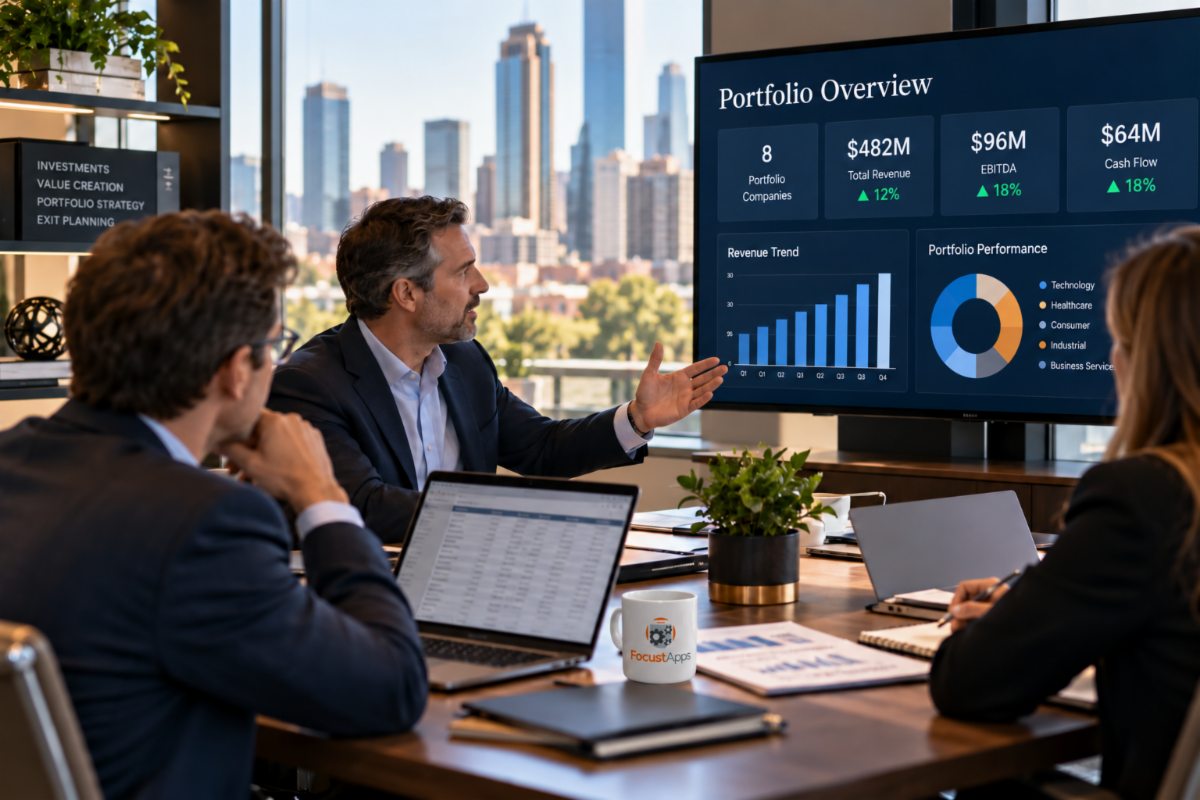
Growth is the goal of every private equity firm. More acquisitions, additional portfolio companies, and expanded investment opportunities create the potential for stronger returns and greater enterprise value. But as portfolios grow, the processes used to manage financial and operational reporting don't always keep pace. What worked when a firm managed three or four portfolio companies can quickly become inefficient when that number doubles or triples. Spreadsheets multiply, reporting formats vary, and investment teams find themselves spending more time collecting and reconciling information than analyzing it. The challenge isn't necessarily a lack of data. It's that the reporting process was never designed to scale with the portfolio. And when visibility becomes more difficult as assets under management grow, firms risk losing the operational agility they need to protect margins, identify opportunities, and maximize returns.
Consider the typical reporting cycle across a growing portfolio. Each company submits financial statements, operational KPIs, cash flow projections, and performance updates, often using different systems, definitions, and reporting schedules. Investment analysts must gather the information, standardize the numbers, reconcile inconsistencies, and prepare reports for operating partners, investment committees, and limited partners. As additional companies enter the portfolio, the workload increases, but the process often remains largely unchanged. The result is an expanding collection of spreadsheets, disconnected databases, and manual reporting procedures that require increasing amounts of time and oversight. Instead of evaluating EBITDA performance, working capital trends, revenue growth, and operational improvements, highly skilled investment professionals can spend valuable hours simply trying to determine whether the information they have is accurate and current.
One of the clearest warning signs that a reporting process has outgrown its usefulness is when portfolio performance becomes harder to evaluate as the firm grows. Perhaps monthly reporting takes longer despite additional resources. Maybe analysts repeatedly request clarification from portfolio company CFOs because financial metrics are calculated differently. Investment teams may struggle to
...Click the link below to finish the article
|