June 1, 2026

The Markets

It was a record-setting month.


“Sell in May and Go Away” was an investment strategy promoted by the Stock Trader's Almanac. The idea was based on historic research that suggested holding stocks, as represented by the Dow Jones Industrial Average (Dow), from November to April delivered better returns than holding stocks all year round.


“What [the research] didn't note is that if one used the S&P 500 index, which dates to 1927, one would have found the opposite: the summers almost always outperformed the winters,” reported Troy Segal of Investopedia.


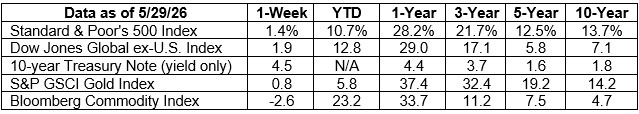
This year, most investors were happy with stock performance in May as the United States delivered one of the strongest monthly performances on record. Martin Baccardax of Barron’s explained, “The S&P 500…was on pace to power more than 5 [percent] higher…marking one of the best performances in May since the 1950s, on the back of surging chip and tech stocks that have carried markets through the worst of the U.S. war with Iran.”


However, the performance comes with an important caveat. Market breadth – the number of stocks participating in the rally – was low. A source cited by Connor Smith of Barron’s stated:


“While the overall market is at all-time peaks, only two of the eleven sectors have managed to reach that status…It is a very rare situation indeed to be talking about a stock market at record highs at the same time that the Financials, of all sectors, are very nearly in correction mode (down nearly -10 [percent] from the record highs).”


Last week, major U.S. stock indexes finished the month at record highs amid strong company earnings reports and hopes for peace between the U.S. and Iran, reported Avi Salzman of Barron’s. Yields on intermediate- and longer-term maturities of U.S. Treasuries moved lower over the week.

What's The Right Withdrawal Rate In Retirement?


One of the most common questions in retirement planning is also one of the most difficult to answer: How much can I safely withdraw from my portfolio each year? Many people hope for a simple answer, a percentage that will work for everyone, but different people have different needs.


The answer may be found between 3.9 percent and 5.7 percent


According to Morningstar’s The State of Retirement Income: 2025, a new retiree seeking a stable, inflation-adjusted income over a 30-year retirement could start with a withdrawal rate of about 3.9 percent. The estimate assumed the retiree’s portfolio was invested 30 to 50 percent in stocks with the rest in bonds and/or cash.


“Because a 3.9 [percent] withdrawal rate—or just $39,000 on a $1 million portfolio—might be a bitter pill to swallow for new retirees, we also examined how flexible strategies can help boost starting safe withdrawal rates. Flexible strategies are effective because they help to prevent retirees from overspending in periods of market weakness, while giving them a raise in stronger market environments,” reported Amy C. Arnott, Christine Benz, and Jason Kephart of Morningstar.


The researchers found that retirees who are willing to make modest spending adjustments over time may be able to support higher withdrawal rates. Some spending strategies supported initial withdrawal rates approaching 5.7 percent. However, the strategies generally required retirees to accept the possibility of variable income in each year of retirement.


Retirement income is not a simple math problem


Your retirement income strategy will reflect your lifestyle and legacy goals, as well as other factors. One retiree may prefer a stable income and choose a more conservative initial withdrawal rate, while another may be comfortable with variable income and choose to make systematic adjustments to spending. Retirement planning often involves tradeoffs.


If you would like to talk about your plan or discuss retirement income strategies, get in touch. We’re here for you.

Bruce Kuehl | 763.542.8884 | bruce.kuehl@avior.com

Please feel free to forward this commentary to family, friends or colleagues. If you would like us to add them to the list, please reply to this email with their email address and we will ask for their permission to be added.

Investment management and financial planning services offered through Avior Wealth Management, LLC a registered investment advisor. Investments involve varying degrees of risk and there can be no assurance that the future performance of any investment or investment strategy will be profitable or equal past performance results. All investments subject to loss including the loss of principle. Nothing contained herein should be construed as tax advice. Specific, individual tax questions should be asked of your CPA or accountant.


Please remember to contact Avior, In writing, if there are any changes in your personal/financial situation or investment objectives for the purpose of reviewing/evaluating/revising our previous recommendations and/or services, or if you want to impose, add, or modify any reasonable restrictions to our investment advisory services. Unless, and until, you notify us, in writing, to the contrary, we shall continue to provide services as we do currently. Please advise us if you have not been receiving account statements (at least quarterly) from the account custodian. A copy of our current written disclosure Brochure and Form CRS (Customer Relationship Summary) discussing our advisory services and fees continues to remain available upon request or at www.aviorwealthmn.com.