Rates continue their decline! Down 0.125% from last week!!!
Borg's Edge Weekly Rates
Chris Borg
NMLS#116995/#891464
Borg Edge Home Finance
503-481-1369
Chris@Borg-Edge.com
Mortgage Rates Dip Again as the Market Takes a Breather
Mortgage rates dipped again, and the bond market has been pretty calm this week.
After last week’s improvement, rates haven’t dropped a bir furthe. Investors are waiting to see what happens with the economy, the Fed, and big tech companies.
For now, the market is taking a breather, and we’re happy to see rates holding onto their recent gains!
TRUE - INDEPENDENT - MORTAGE BROKER
Rates as of [Wednesday October 21, 2026]
UNDERWRITING FEE WAIVED ON ALL SCENARIOS!!!
LOAN PROGRAM
RATE
APR/POINTS
30 YEAR FIXED
7.250%
7.508% / 0.570
15 YEAR FIXED
6.625%
6.901% / 0.598
FHA 30 YEAR FIXED
6.625%
7.644% / 0.630
VA 30 YEAR FIXED
6.375%
6.776% / 0.978
JUMBO 30 YEAR FIXED
6.750%
7.052% / 0.623
*APR=Annual Percentage Rate. Assumed 760 credit score, OR/WA purchase. Rates include pricing up to a 1% loan fee. Based on $600,000 purchase price with 20% down. FHA APR based on $600,000 purchase price with 3.5% down includes MI. VA with 0% down & 2.15% Funding Fee. Jumbo loan based on $1,125,000 sales price with 20% down/780 credit score. Rates are subject to change during the loan term. That change can increase or decrease your monthly payment. See Hood River Mortgage Group for details. Rates are subject to change without notice.
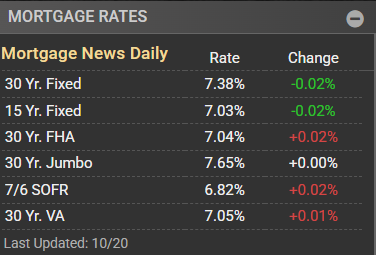
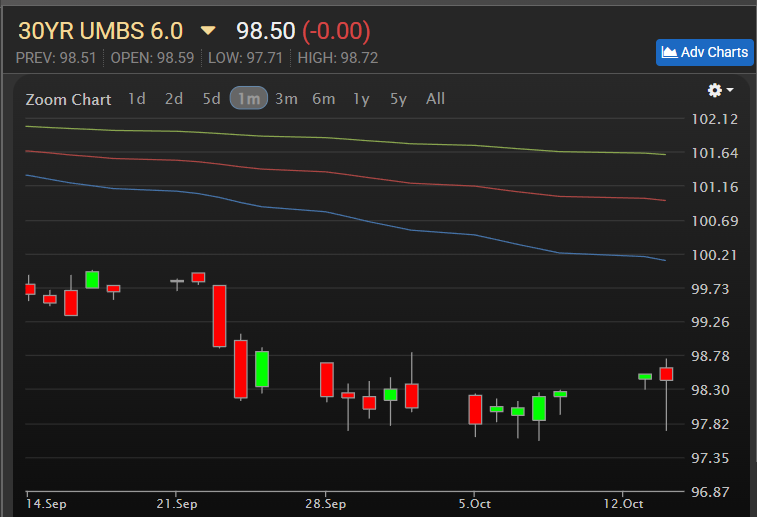
PUBLISHED NATIONAL AVERAGE RATES Mortgage backed securities chart
How Mortgage News Daily Calculates These Rates
Averages are based on actual rate sheets from a variety of wholesale, correspondent and retail lenders, using a consistent “top-tier” borrower scenario. Rates are updated daily as market pricing changes.
The typical scenario assumes:
780 FICO
75% LTV / 25% down
30-year fixed conventional conforming loan
Top-tier agency pricing
No unusual or program-specific pricing adjustments
Actual mortgage pricing can vary based on credit, down payment, loan amount, property type, loan program, points and other factors.
📈 Reading the MBS Chart
MBS prices and mortgage rates generally move in opposite directions.
MBS price ↑ = Good for mortgage rates — pricing improves, which can lead to lower rates.
MBS price ↓ = Bad for mortgage rates — pricing deteriorates, which can put upward pressure on rates.
The one-month chart helps show the overall trend rather than focusing on any single day.
When MBS prices are trending higher, that’s generally a positive sign for mortgage rates.
When prices are trending lower, rates are typically facing upward pressure.s are typically facing upward pressure.
This Week’s Program Highlight:
Temporary Buydowns — Help Buyers Buy and Sellers Sell!
With affordability still a challenge, a temporary buydown can make a home more attractive to buyers by lowering their monthly payments during the first few years of the loan. It can also give sellers another tool to help move a property without reducing the asking price.
Buydown Options:
1-0 Buydown: Payment is based on a rate 1% below the note rate in year one, then returns to the note rate.
1-1 Buydown: Payment is based on a rate 1% below the note rate for each of the first two years, where available.
2-1 Buydown: Payment is based on a rate 2% below the note rate in year one and 1% below in year two, then returns to the note rate in year three.
Temporary buydowns reduce the buyer’s initial payments; the permanent note rate does not change. Borrowers generally must qualify at the full note rate. Eligibility and terms vary by program and lender.
Sellers and buyers can benefit?
Sellers can contribute toward the buydown to help attract buyers, improve affordability, and make a property stand out. Eligible for conventional, FHA, and VA loans.
***I can also roll in a LENDER buy down without seller contribution and use seller paid concessions to cover closing costs.
Have a buyer or listing that needs a little extra incentive? Let’s look at the options and see how we can structure the deal to help get it done.
Give me a call and let's see !
Have First Time Home Buyers?
Ask me about my Oregon Housing Down Payment Assistance Programs
Mortgage Strategy Tips:
Encourage buyers to compare multiple lenders—rate quotes don’t require multiple full applications.
Mortgage brokers can’t mark up government loans (VA, FHA, USDA), making them especially competitive.
Proactively review past clients for refinance or cash-out opportunities.
Ask about DSCR and non-QM options for investor clients.