|
WITH INTEREST RATES OVER 7%, IS IT A GOOD TIME TO BUY?
When looking to purchase a home, determine what is your comfortable monthly payment. Then, work backwards to see what loan amount would result in that payment. This is very similar to rent. When you are looking to rent a home, you first consider what you can pay, and then find those homes that fit your payment.
For a mortgage, your total monthly payment includes principal and interest on the mortgage, plus pro-rated amounts for homeowners insurance and real estate taxes. If there is an HOA, you would have to include that number, too, although it is paid separately, not part of the mortgage payment.
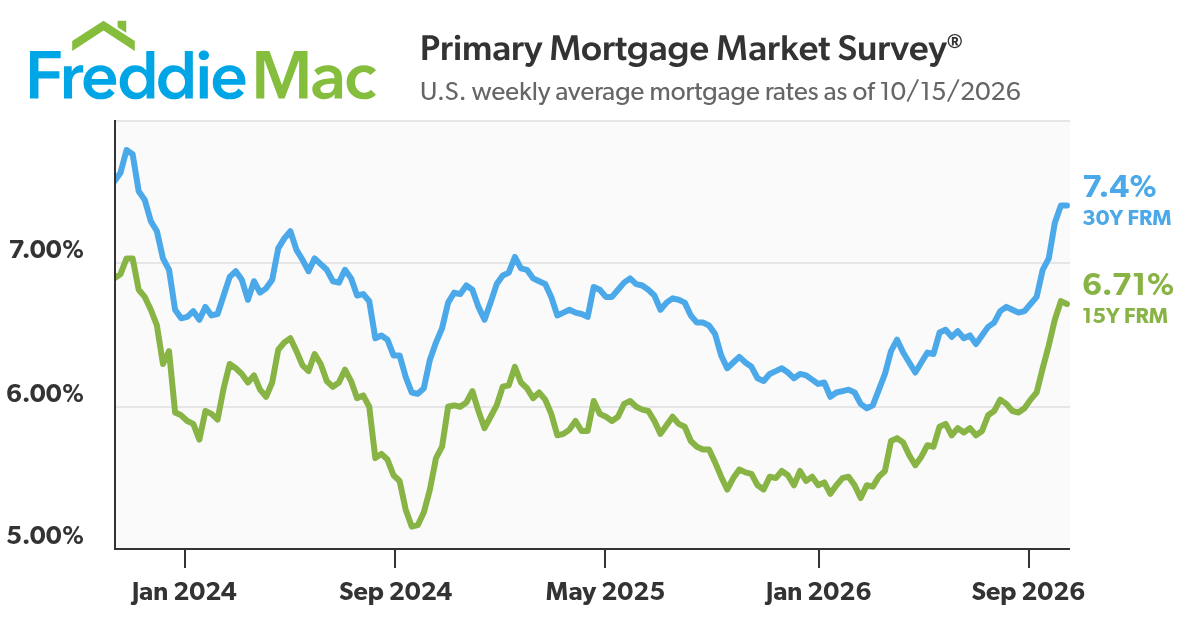
Let's take a look at an example. Assume you are purchasing a $700,000 single family residence, putting 20% down resulting in a $560,000 loan amount, and have good credit. There is no HOA. Using the 30-year fixed mortgage interest rate of 7.4% as quoted by Freddie Mac above, and estimating insurance and taxes, the following is an estimate of your monthly payment:
Principal and interest - $3,877.33
Homeowners insurance - $200
Real estate taxes - $300
Total payment - $4,377.33
So, now do you simply compare this payment to homes you can rent for $4,377 per month? Not so fast. . . there are advantages to a mortgage payment that you don't receive with a rent payment. First, a portion of each payment is applied to principal. In the above example, $424 of the first mortgage payment is applied towards principal. Second, you can deduct the interest paid on a mortgage. In the first year of this mortgage, you would pay $41,263.84 in interest on the loan. If you are in the 22% tax bracket, this results in an annual tax savings of $9,078.04, which averages to $756.50 per month. So, your effective monthly payment would be $4,377.33 minus $424 towards principal, and $756.50 in tax savings, resulting in a payment of $3,196.83. This is $1,180.50 less than the $4,377.33 payment.
If you are comparing the mortgage payment to what you can rent, you should look at rental properties listed for approximately $3,200 per month. You may find you get a bigger bang for your buck by purchasing a home. Further, depending on the market, the home could appreciate over time, thereby increasing your equity.
This same analysis can be applied on lower priced homes or higher priced luxury homes. Consider what is your comfortable payment, then work backwards to see what it results in the price of a home. If you consider the monthly principal payment and tax savings, the monthly comfortable payment could be higher, thereby resulting in a higher priced home with more bells and whistles, which you may prefer.
There are other variables that could come into play, such as mortgage insurance if you put less than 20% down, and monthly HOA payments. If you have a particular scenario you are considering, give us a call and we can walk you through these calculations. You may find that purchasing a home is still a good option, even if interest rates are above 7%.
|