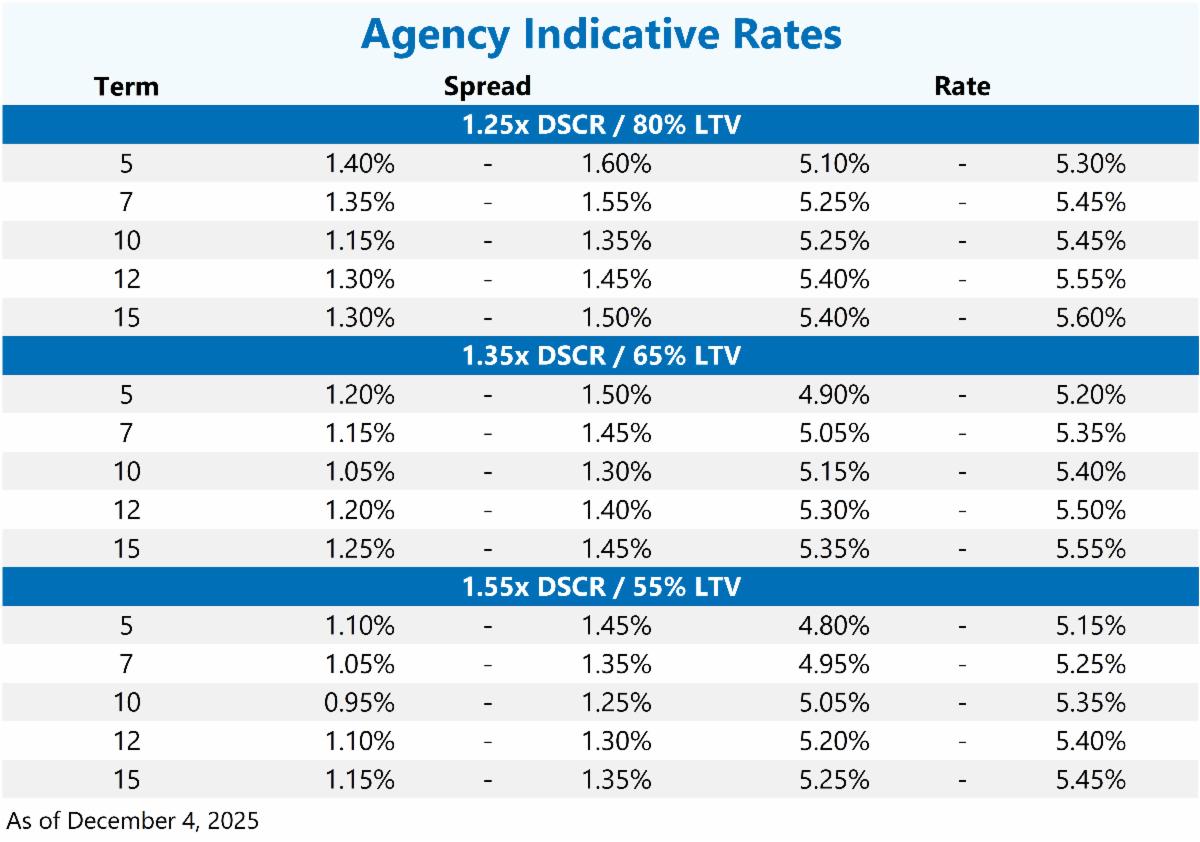
December 4, 2025 | Capital Market Updates From BWE Arizona | | | Agency | Life Company | | 5.05%
0.90% + 10 yr UST
Low leverage multifamily refinance | 5.30%
1.20% + 10 yr UST
Low leverage multifamily refinance | | | |
Federal Reserve, policy direction and market focus
- Markets enter December laser-focused on
- Next Fed Chair nomination after President Trump hinted he already knows his pick.
- Soft private labor reports have come in this week from ADP Research and Challenger, Gray, and Christmas causing risk sentiment to shift further towards employment conditions as traders consider the Fed’s next move.
- Manufacturing PMI and ISM reports, which showed headline PMI still expanding but new orders weakening, pointing to slowing demand.
- Fed is now in pre-meeting blackout, so no monetary-policy commentary expected from Powell or Bowman.
Rate cut expectations
- Markets now assign ~99% odds of a 25 bps rate cut at the December 9-10 FOMC meeting.
- This is a major shift from ~50% odds in mid-November driven by dovish Fedspeak before the blackout and continued softening in private labor indicators.
Treasury market conditions
- Despite last week’s tight range trading and brief dip below 4% on the 10-year, the Treasury experienced a sharp selloff of 5-8 bps across the curve.
- Drivers of the selloff included:
- New highs in Japanese 10-year government bond yields (highest since 2008), raising concerns of BOJ tightening.
- Large wave of U.S. corporate bond issuance as issuers rush to finalize year-end funding.
- Post-holiday, start-of-month liquidity adjustments and repositioning.
- Treasury auctions are light this week, leaving yields driven mostly by economic data releases and pre-Fed positioning.
Overall tone
- The Treasury selloff is driven not by inflation fear or Fed repricing, but by global yield pressures (Japan), big corporate supply, and portfolio realignment.
- Markets remain overwhelmingly convinced of a December rate cut even as yields rise.
- The final weeks of 2025 are shaping up to be dominated by
- Fed Chair speculation.
- Private labor data.
- Corporate issuance.
- Rapidly shifting cross-border, yield dynamics.
| | |
The FHFA announced more than a 20% increase to the lending capacity for both Fannie Mae and Freddie Mac. Their caps increased from $73 billion in 2025 to $88 billion in 2026. Since the prior week’s slowdown, new issue Fannie Mae DUS/MBS rate-lock activity has picked up the last two weeks. The Fannie Mae DUS/MBS market rate locked roughly $1.9 billion weeks ago and $1.4 billion during the holiday week.
Of note, there were multiple 5-year SARMs (rare floating rate structure in the current environment) and over 11 block-size loans ($40-120MM+) that transacted during the weeks. Agency CMBS credit/investor spreads remain near their tightest levels of the year as traders and investors recognize that Agency CMBS are priced attractively relative to other “like” investment-grade asset classes.
Bloomberg reports that November's investment-grade corporate issuance is just $6 billion away from breaking the 2012 monthly record. The Bloomberg Single-A Industrials 10-year and Markit CDX IG 5-year indices widened by approximately 1-2 basis points over the week, most likely due to the pressure from heavier-than-expected corporate issuance. Despite a strong wave of corporate debt supply hitting the market in recent months, investment-grade corporate credit spreads remain historically tight overall.
Observations
- Borrowers are pushing to lock before year-end and before the holidays, adding to volume.
- Investor spreads remained stable despite heavy supply, reflecting strong demand from money managers, hedge funds, regional banks, and REITs.
- Execution dynamics: Tightest pricing remains on
- Block-sized loans ($25MM+).
- Full-term interest-only structures.
- Interest-rate buydown transactions.
- Smaller loans (<$10MM) trading slightly better week-over-week but still command modest spread premiums vs. large blocks.
Agency Caps for 2026
- Like prior years, the Agencies will be tasked with ensuring 50% of their volume meets mission (defined as rental rates affordable at 80% of AMI in most markets).
- For loans where at least 20% of the units are restricted to 80% of AMI via the loan documents, the loan amounts are excluded from the caps. This includes loans that are executed through Freddie Mac’s Rent Preservation program and Fannie’s Sponsor Dedicated Workforce (“SDW”) or Sponsor Initiated Affordability (“SIA”) programs.
- Additional details around the caps should be coming to light in the coming weeks.
Highlight: Fannie Mae Loan
- Multifamily Acquisition in Chattanooga, TN
- $6.9 million
- 7-yr term fixed / 4.95% rate / 118 spread
| | |
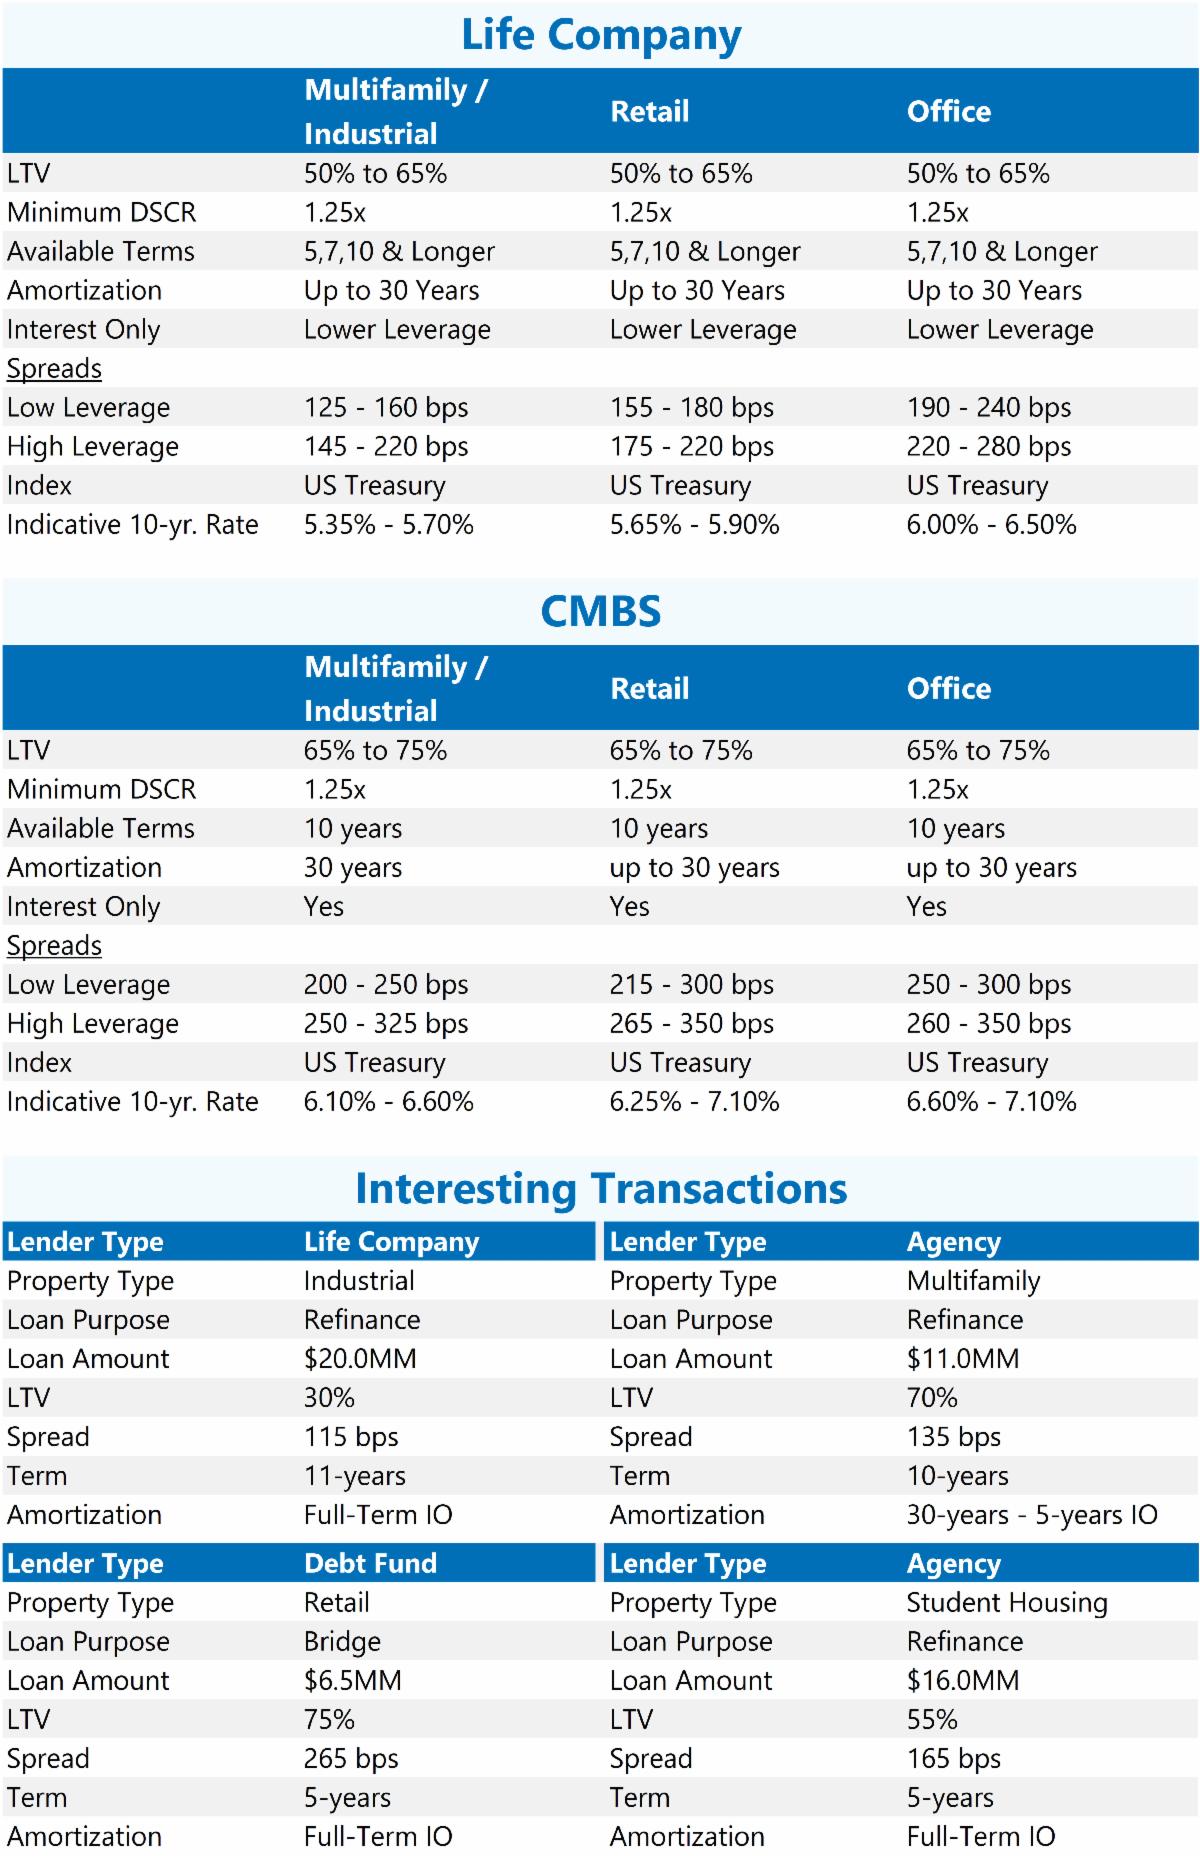
Life Company lenders are actively reviewing loan opportunities for Q1 2026 fundings. Many have reported similar production goals to their 2025 levels. All these lenders have reported a good volume for early 2026 closings.
Pricing remains steady with Life Company spreads for good quality, well located, and stable properties remaining between 150-200 basis points. Some lenders will price a little below that range to jumpstart their production and win desirable loan opportunities.
Outlier pricing for high quality, low leverage multifamily and industrial properties in primary markets with strong sponsors may price 20-40 basis points lower. Lenders are scrutinizing historical financials to a higher degree, seeking responses that explain recently higher or inconsistent expense outflows while underwriting properties in preparation for quoting.
| | |
U.S. CMBS issuance volume is $112 billion year to date, surpassing the post-GFC record of $110.6 billion from 2021. Conduit spreads found some stability in recent weeks after several months of tightening. 10-year AAA spreads are currently at approx. 79 basis points over Treasuries, which is in line with the 78-basis-point average over the past year.
Borrower spreads have remained range bound over the last several months. Full leverage 10-year CMBS loans are pricing in the range of 200-225 basis points over Treasuries, while 5-year CMBS loans are pricing in the range of low-to-mid 200s. Pricing may be as low as 140 basis points for quality, low leverage business.
Multifamily properties continue to attract strong interest from CMBS lenders, who are still offering full-term, interest-only financing. This structure allows borrowers to maximize loan proceeds, with underwriting typically supporting a 1.25x DSCR on an interest-only basis. Other asset classes, including office properties, have also benefited from full-term, interest-only structures. However, these loans generally require more conservative leverage, higher debt yield thresholds, and stricter underwriting criteria.
| | |
Opinions, estimates, forecasts and all other information contained in this document are those of Bellwether Enterprise Real Estate Capital, LLC (“Bellwether”) and should not be construed as indicating Bellwether’s business prospects or expected results. Although Bellwether attempts to provide reliable, useful information, it does not guarantee that the information or other content in this document is accurate, current, or suitable for any particular purpose. All content is provided on an “as is” basis, with no warranties of any kind whatsoever and is subject to change at any time without notice. Information in this document may not be used without permission from Bellwether. This document is not intended to be an offer to buy or sell or a solicitation of an offer to buy or sell securities, if any, referred to herein.
Bellwether Enterprise Real Estate Capital, LLC (BWE) conducts business through Bellwether Enterprise Mortgage Investments, LLC – Mortgage Banker license #BK-1007784 – the Department of Financial Institutions State of AZ (Fannie Mae transactions), as well as Bellwether Enterprise Real Estate Capital, LLC – Mortgage Banker License #BK-1007825 – the Department of Financial Institutions State of AZ (all other transactions).
| | | | |