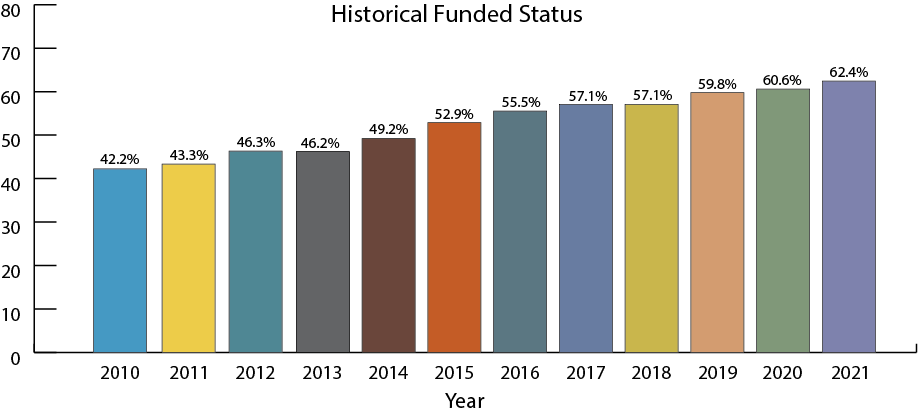The Pensioner: Looking Forward
|
|
Welcome to the digital MPERS newsletter! The Pensioner: Looking Forward contains news, updates, and important information for active employees of the Missouri Department of Transportation, the Missouri State Highway Patrol, and MPERS.
|
|
2021 was a Remarkable Year! |
|
While 2020 was a difficult year for many reasons, 2021 couldn't have been better with regards to MPERS’ financial position. During 2021, MPERS hit some truly remarkable milestones. |
|
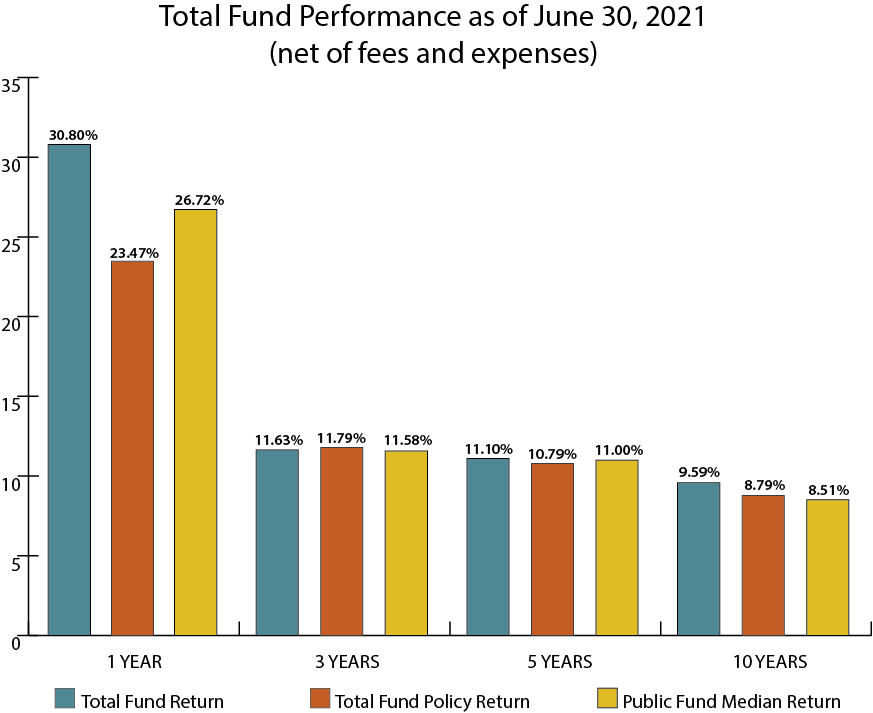
Why is this remarkable? First, we must consider the assumed rate of return approved by the Board each year. The assumed rate of return is the rate MPERS' actuary uses to generate its assumptions regarding the plan’s cost and funded status. In short, it is a goal that the Board would like the investment staff to aim for regarding overall investment portfolio returns over the long term. The current assumed rate of return is 6.5%.
Second, we compare this rate of return to previous years. Previous investment returns have been anywhere from -0.46% for the 2020 fiscal year, to upwards of 11.23% for the 2018 fiscal year. When the return for the 2021 fiscal year was finalized at 30.8%, it was impossible to call this return anything other than remarkable.
Third, the rate of return can be compared to our peer universe, which includes other public pension plans. Our 30.8% rate of return is significantly higher than the average 26.7% return that other public pension plans experienced during the 2021 fiscal year. Again, truly remarkable.
|
|
Funded Status Increased to 62.4% |
|
Why is this remarkable? A system's funded status is a good indicator of overall system health. MPERS’ goal is to be 100% funded, and we have made great strides toward that goal. As you can see in the graphic below, on the heels of the great recession, the funded status was at a low of 42.2%. Since then, the Board’s aggressive funding policies as well as the professional management of the MPERS investment staff have been integral in the increase of the funded status by over 20.2% in 11 short years.
As of June 30, 2021, MPERS’ permanent funding policy had a closed amortization period of 14 years. At the current rate under this funding policy, and everything else being equal, MPERS will reach the goal of being 100% funded in 14 years
|
|
Asset Value Surpassed Three Billion Dollars |
|
Why is this remarkable? Considering MPERS’ fund value surpassed two billion dollars about six years ago, gaining over a billion dollars in value in such a short time is incredible. While these large numbers are difficult to comprehend, suffice it to say, things are headed in the right direction.
This is a function of sound oversight by the Board, aggressive funding policies, effective implementation by staff, and kind financial markets that provided an awesome return for the last fiscal year.
|
|
In the March edition of The Pensioner: Looking Forward, the oversight formula was introduced: |
|
In the oversight formula, contributions plus investments equals benefits plus expenses. In the November edition of The Pensioner: In the Moment we explored the types of benefits that MPERS administers; retirement, disability, and death benefits. This month we will be looking at the benefit cost. |
|
|
|
In the context of the oversight formula, the “B” or “Benefits” is the driver of the other factors in the formula. That is, the cost of the benefits largely dictates the entire equation. As a result, it is critically important to value the benefits as precisely as possible. The annual actuarial valuation is the process where MPERS benefits are valued. The annual report that coincides with this process is the basis of the executive director’s annual financial update each October. The financial update covers the funded status of the plan and the required employer contribution rate for the upcoming fiscal year.
What you do not see in the report is the almost infinite level of detail the actuary reviews to arrive at the cost of the plan(s). Believe it or not, the actuary looks at every individual covered by MPERS and using a set of assumptions, projects the benefit amount each person might receive.
|
|
To explain it simply, a final salary is estimated for each member, the total amount of service is noted, a life expectancy is estimated based on mortality tables, to arrive at an overall cost for each member. Considering that MPERS has thousands of members, this is a daunting and time-consuming task. |
|
Naturally, MPERS’ staff is heavily involved with this process, first, to be sure the actuary has complete and accurate data for the process, and second, to review the output to be sure it is consistent with the data and the benefits provided by the plan. In order to validate the actuarial process, there are other important reviews that must occur. The first is a simple review that is conducted annually during the external audit of the plan. At this point, the independent actuary reviews the assumptions (i.e., projected salary, life expectancy, amount of service, etc.) for the plan to be sure the assumptions are consistent with prevailing information. |
|
A second, much more comprehensive audit is performed every 7 to 10 years where a different actuary is hired to complete another valuation (this is called an actuarial audit). In other words, this is a second opinion to validate the original valuation. This second opinion reinforces the output of the consulting actuary and clarifies any points of concern or question that could make the output better. It should be noted that precision is unattainable in this process because no one can predict the future with certainty. The goal is to have results that reasonably forecast the cost of benefits so they can be adequately funded.
At the end of the day, we rely very heavily on the high quality and detailed work of the actuary to determine the benefit cost to the System. An accurate actuarial valuation produced on an annual basis is the only clear way to calculate a precise contribution rate for the sponsoring employers.
Next month we will be covering the last component of the oversight formula: expenses.
|
|
The 2021 Annual Comprehensive Financial Report is Now Available! |
|
Check Out This Month's Benefit Bite!
|
|
If you are thinking about retirement sooner rather than later, make sure you are aware of the two-step retirement process deadlines! |
|
Step one is the Notice of Retirement which can be submitted electronically through your myMPERS account or by submitting the Notice of Retirement form found under Resources on our website. Step one must be received by MPERS no later than one month plus one day prior to your intended retirement date. For your convenience when reviewing the form, page two contains a table that provides statutory deadlines when considering your intended retirement date.
Step two is a packet that contains the Retirement Election Form. The Retirement Election Form is how you inform MPERS of your payment option, your plan choice (Closed Plan members only), and your BackDROP options, if eligible. The deadline for step two is the day prior to your intended retirement date.
Below is the retirement deadline table that is included on the second page of the Notice of Retirement. You can also view this chart and other information related to the retirement process in the Ready to Retire section under the Member Education portion of our website. |
|
2022 Board Meeting Schedule |
|
Friday, February 25
Friday, April 29 (tentative)
Thursday, June 16
Thursday, September 22
Thursday, November 17
|
|
- 24 - Christmas Eve (Christmas Day Observed)-office closed
- 31 - New Year's Eve (New Year's Day Observed) -office closed
-
31 - Deadline to submit step 1 - Notice of Retirement for February 1 retirement
|
|
We value your feedback!
What would you like to see in The Pensioner: Looking Forward?
|
|
|
|
|
|
|