|
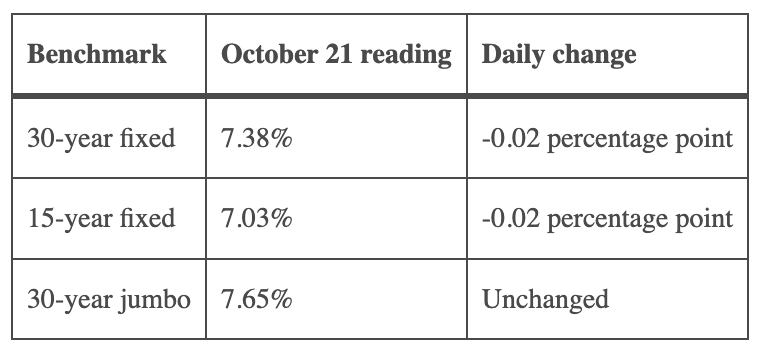
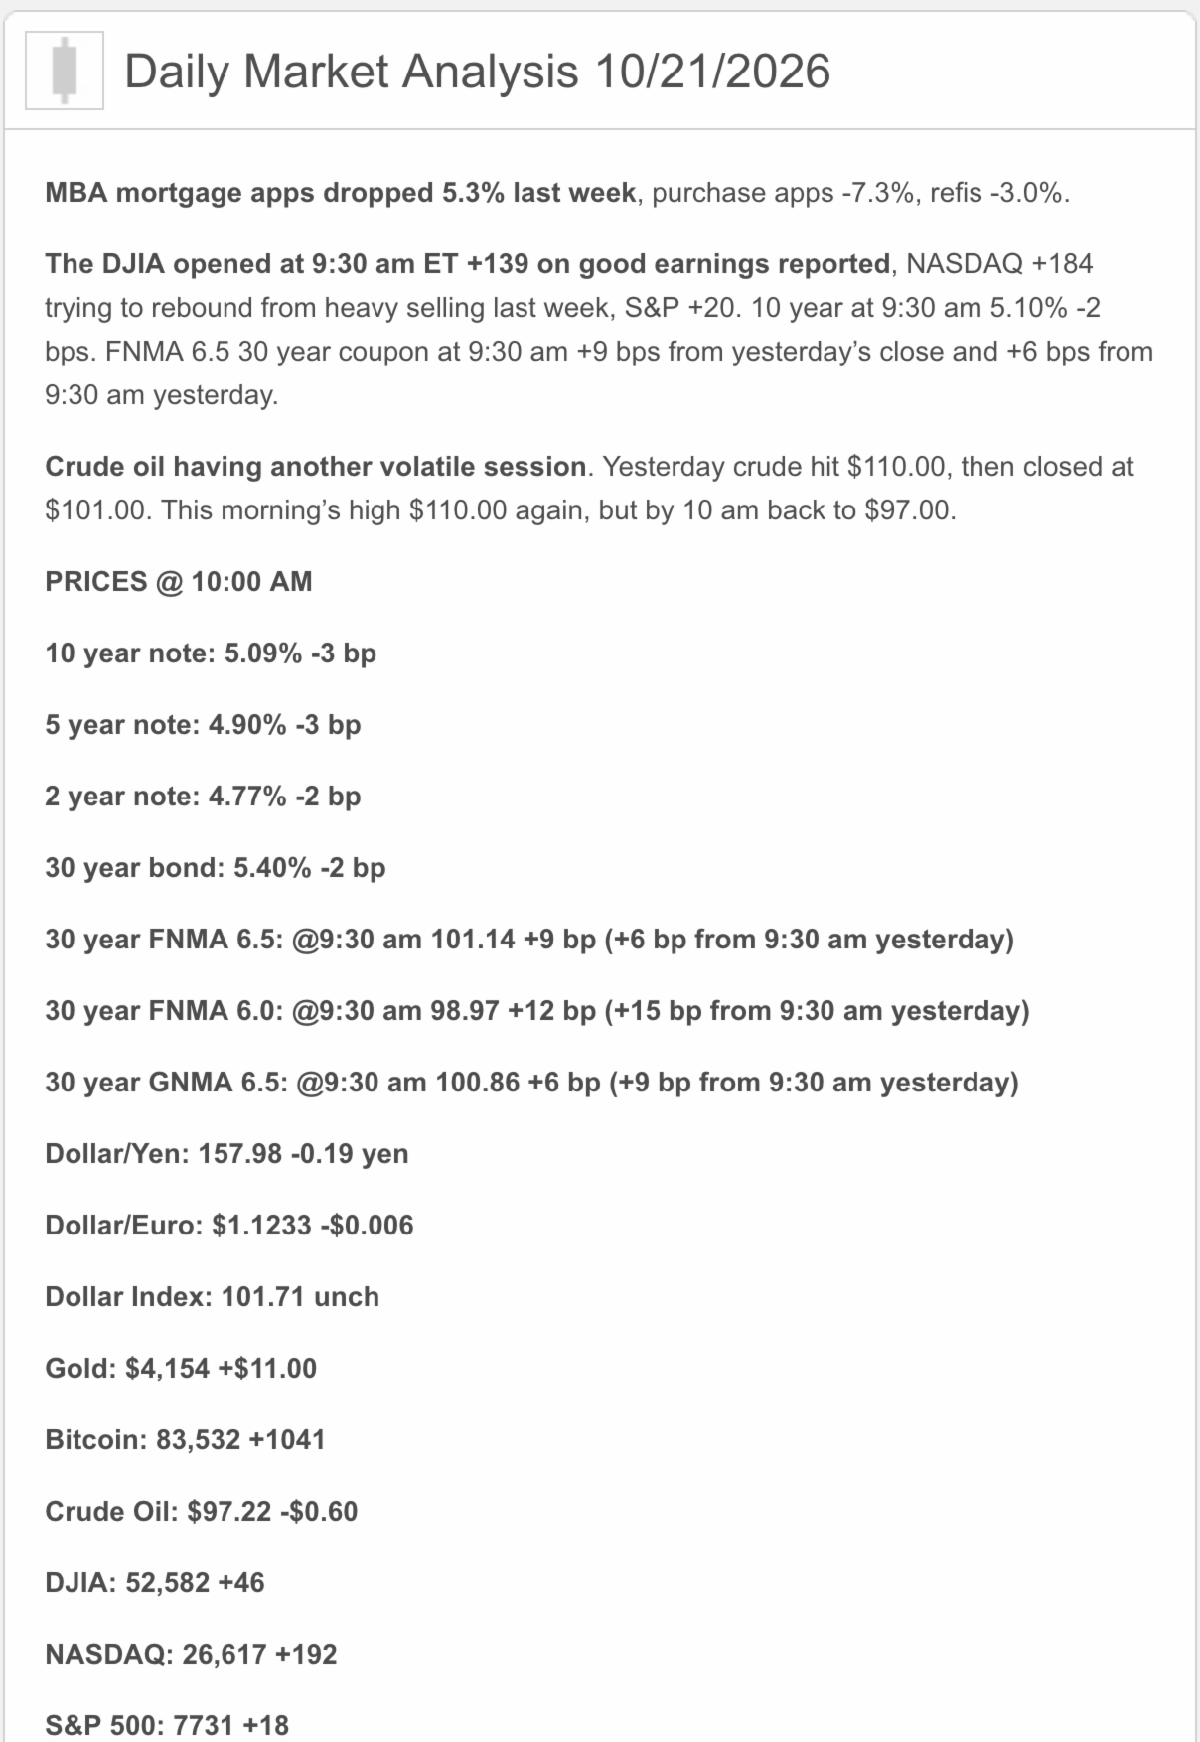
Mortgage News Daily's national index shows modest improvement. Its intraday Treasury display was near 5.11%; that is a snapshot, not a closing yield. Exact quote time was not supplied. These are market benchmarks, not personalized loan offers; actual pricing depends on borrower qualifications, loan terms and points.
Housing & Economy: Relief Hasn't Reached Demand
Today's MBA report, covering the week ended October 16, showed applications down 5.3%. Purchase applications fell 7% weekly and were 18% below a year earlier, according to HousingWire's coverage.
My read: a small rate decline helps at the margin, but buyers still need a workable total payment. Slower activity can create negotiating room; it does not guarantee a bargain in every neighborhood.
Markets: Bonds Catch Their Breath
MND describes bonds trading sideways after last week's rally, with technology-sector concerns, economic data and Fed policy shaping the next move.
For borrowers, a quieter market is a chance to compare options without assuming the calm will last. No crystal ball required—just a good worksheet.
Fed Watch: Expectations Are Not Decisions
In Reuters' October 16–20 poll, 94 of 100 economists expected the Fed to hold its 3.75%–4.00% policy range at the October 27–28 meeting. That is a forecast, not an announced decision.
Mortgage rates also respond to longer-term bond pricing; a Fed pause would not promise lower mortgage rates.
Politics: Heating Costs Meet Election Season
The administration is offering loans of up to 315,000 barrels from the Northeast heating-oil reserve, with deliveries due by November 13. Reuters reports energy costs are an issue ahead of the November 3 midterms.
My takeaway: fuel costs touch household budgets and inflation expectations.
A policy announcement alone does not establish how much consumers will save.
Put Today's News to Work
-
Buyers: Compare the full payment, cash to close and reserves—not just the headline rate.
-
Agents: Model a price reduction against an eligible seller credit or rate buydown.
-
Homeowners: Check refinance costs against monthly savings and your likely holding period.
Lock vs. Float
For closings within 15–30 days, my bias is modestly toward locking a payment that works. Float only with room in the budget and a clear trigger to lock.
Farther out, build the financing plan first and revisit pricing as the closing date approaches.
|