There’s been a lot of talk of an AI bubble. From our vantage point, we see something very different. – Jensen Huang, Nvidia CEO, November 19, 2025


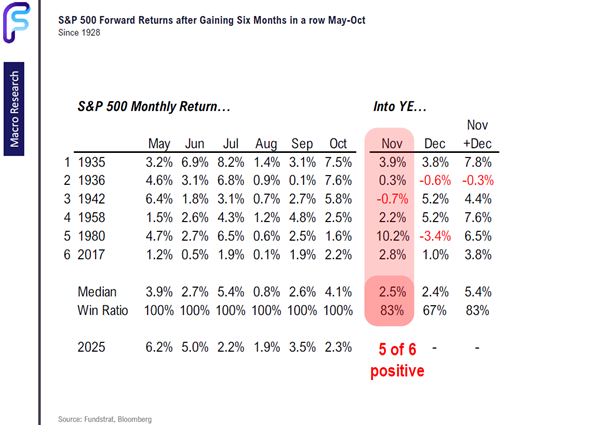
Over the last few weeks, markets have seen a notable spike in volatility. The VIX (volatility index) is up more than 50% for the month of November while the S&P 500 is down more than 3.5%. This move is coming on the heels of six consecutive months of positive returns for the broader markets. Historically, when the S&P 500 has posted six consecutive positive months, the market has tended to finish the year strong. We’ve seen this happen six times since 1928, and in five of those instances, November and December finished positive.

While history is not a guarantee, it is a helpful guide. Despite six months in a row of positive gains, the market has found itself staring at a wall of worry influenced by the following underlying factors.


  • Elevated Stock Valuations – Since the inception of the current bull market in October 2022, the S&P 500 is up nearly 90%. Since 2019, the market is up more than 175%. This has been driven in large part by just a few sectors, with artificial intelligence related tech stocks leading the way. This type of run inevitably leads to talk of a “bubble.” 


  • A Hawkish Federal Reserve – Jerome Powell continues to emphasize the Fed’s commitment to keeping inflation under control, even if that means maintaining higher rates for longer. After initiating a 0.50% rate cute in September of 2024, just weeks before a Presidential election, this is quite a shift in tone for the Fed.


  • Supreme Court Tariff Ruling – The Supreme Court has expressed skepticism over the legality of President Trump’s sweeping tariffs enacted earlier this year. Per Treasury Secretary Scott Bessent, this could result in a repayment of nearly $750 billion in tariff revenue.


  • NYC Mayoral Race and Political Friction – With the election of Zohran Mamdani in New York City, a self-proclaimed Democratic Socialist will be running the city that has long been the hub of American Capitalism. Cause for concern.


  • Crypto deleveraging, private credit stress, repo market stress, and other factors will continue to create noise that will contribute to the wall of worry.


Even with these crosscurrents, the economic backdrop remains constructive. Nvidia’s earnings report last night delivered strong results, with the company beating expectations and raising guidance on both revenue and earnings. CEO Jensen Huang highlighted sustained demand and a long runway for continued growth. Adding to the positive data, this morning’s jobs report came in significantly stronger than expected. That combination initially pushed the S&P 500 up more than 1.5% and the Nasdaq up more than 2%.


By this afternoon, however, those gains were erased as the market reminded us that, at least in the short term, we remain in a “risk-off” environment.

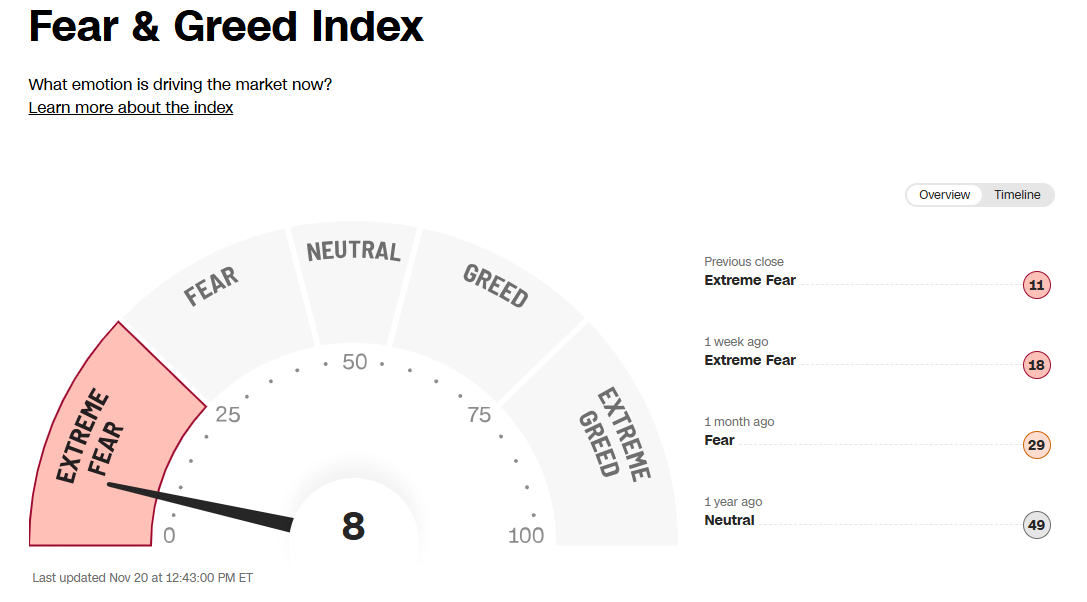
The Fear & Greed Index, a gauge of market sentiment that tracks indicators such as momentum, breadth, volatility, options activity, and safe-haven demand, currently reflects “extreme fear.” Historically, markets often climb during periods like this, when skepticism is elevated but economic data continues to surprise to the upside.


As always, we are closely monitoring these developments and managing your portfolio with an active, disciplined approach.


Please don’t hesitate to reach out if you’d like to discuss any of these topics in more detail.


Kent

Kenneth C. Brace, CIMA® 

Vice President, Investments / Crescent Wealth Management

Address: 124 Verdae Blvd., Ste. 105, Greenville, SC 29607

Direct: 864.900.4905 Office: 864.464.9626

Email: kent@crescentwm.com   Website: www.crescentwm.com

Advisory services offered through NewEdge Advisors, LLC, a registered investment adviser. Securities offered through NewEdge Securities, LLC. Member FINRA/SIPC. NewEdge Advisors, LLC and NewEdge Securities, LLC are wholly owned subsidiaries of NewEdge Capital Group, LLC. 


NOTICE: This email communication including all attachments transmitted with it may contain confidential information intended solely for the use of the addressee. If the reader or recipient of this communication is not the intended recipient, or you believe that you have received this communication in error, please notify the sender immediately by return email and PROMPTLY delete this email including all attachments without reading them or saving them in any manner. The unauthorized use, dissemination, distribution, or reproduction of this email, including attachments is strictly prohibited and may be unlawful.