In their continued efforts to turn the tide on inflation, the Federal Reserve raised the federal-funds rate 0.75 percentage points for the third consecutive time.
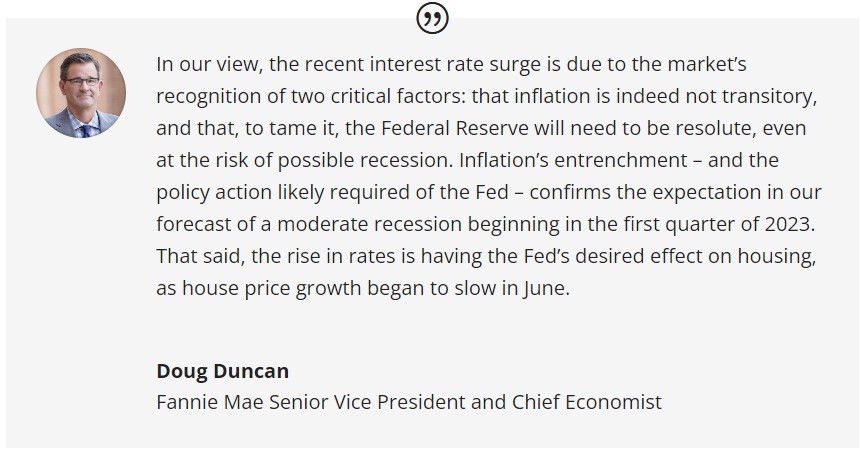
With that — and with mortgage rates rising above 6% (for a 30-year-fixed) — the latest Fannie Mae report shows forecast changes for the 2022 and 2023 housing market.
Here’s what’s changed and what it could mean for you and your clients.
THE FEDERAL RESERVE’S DECISION
By a unanimous vote, Fed officials lifted their benchmark federal interest rate to a range between 3% and 3.25%, a level not seen since early 2008.
By the end of this year, nearly all voting officials expect to raise rates to a range between 4% and 4.5% and project continued raises into 2023. Last June, they expected the federal funds rate to rest at 3.8% by the end of 2023. That figure is now 4.6%.
With the Fed raising rates at the fastest pace since the 1980s, consumers are understandably worried about the impact on the economy, specifically the housing market.
ECONOMIC INDICATORS POINT TO RECESSION IN 2023
The latest Fed projections have the unemployment rate rising to 4.4% next year, up from 3.7% in August and 3.5% in July. Historically, a jump of that size in that span of time has coincided with an economic recession.
While Fed officials expect economic growth to continue during the second half of 2022, they pointed to three factors likely to effect a modest recession in 2023:
- High inflation
- Monetary policy tightening (by the Fed)
- Slowdown in the housing market
On a full-year basis, the ESR Group forecasts 0.0% real GDP growth for 2022. But for 2023, the group revised its projection downward by one-tenth of a percentage point to a negative 0.5%.