President’s Message

When I look across Iowa, I see partners in homeownership and communities bound by purpose and a commitment to excellence. Each of you in the mortgage world brings unique experience, insight and energy. When you engage together, your voices strengthen our collective cause. I encourage you to learn, share bold ideas, seek collaborators and challenge the status quo.


Unity is Our Strength


Overall, homeownership in Iowa remains strong, yet the affordability gap continues to widen. In a world where change is constant, our best defense is solidarity. We are stronger when we move forward together. Mortgage professionals face challenges not isolated to one company or region, so solutions are the responsibility of everyone. The Homebuyers Privacy Protection Act (H.R. 2808) was passed into law late this past summer and will be implemented by March 2026, putting an end to abusive practices known as “trigger leads.” Members of the IMA hold a common bond by sharing high standards and integrity. We must build on this with a spirit of collaboration, not competition, and with a mindset of “us” more than “me.” Lift each other up rather than question each other’s motives. When one succeeds, all benefit — not just in business, but also in the reputation and impact of our profession.


Looking Ahead


Continue learning about trends in lending, innovation in technology, compliance and the changing economic landscape. Stay connected to your peers and empower each other to commit to mutual support. As your president, I pledge to listen, represent and facilitate our shared success. This pledge is only meaningful if each of you commits to active engagement, open-mindedness, collaboration and unity. May we spark fresh ideas, strengthen bonds and inspire each other to greater heights for service to Iowa homeowners.


Terry Gearhart


Neighborhood Finance Corporation


Association Updates

Thank You for Attending the IMA Fall Conference

Thank you to everyone who attended the IMA Fall Conference this year. From an opening reception to a powerful closing session by Jack Stahlmann, who encouraged attendees to look at the upside of life, nearly 150 mortgage professionals gathered to learn and network. Through informative sessions on artificial intelligence in mortgage lending, an economic update, a credit report update, home insurance trends and setting mortgage sales strategies, attendees gained valuable insights and new skills to excel as mortgage professionals.

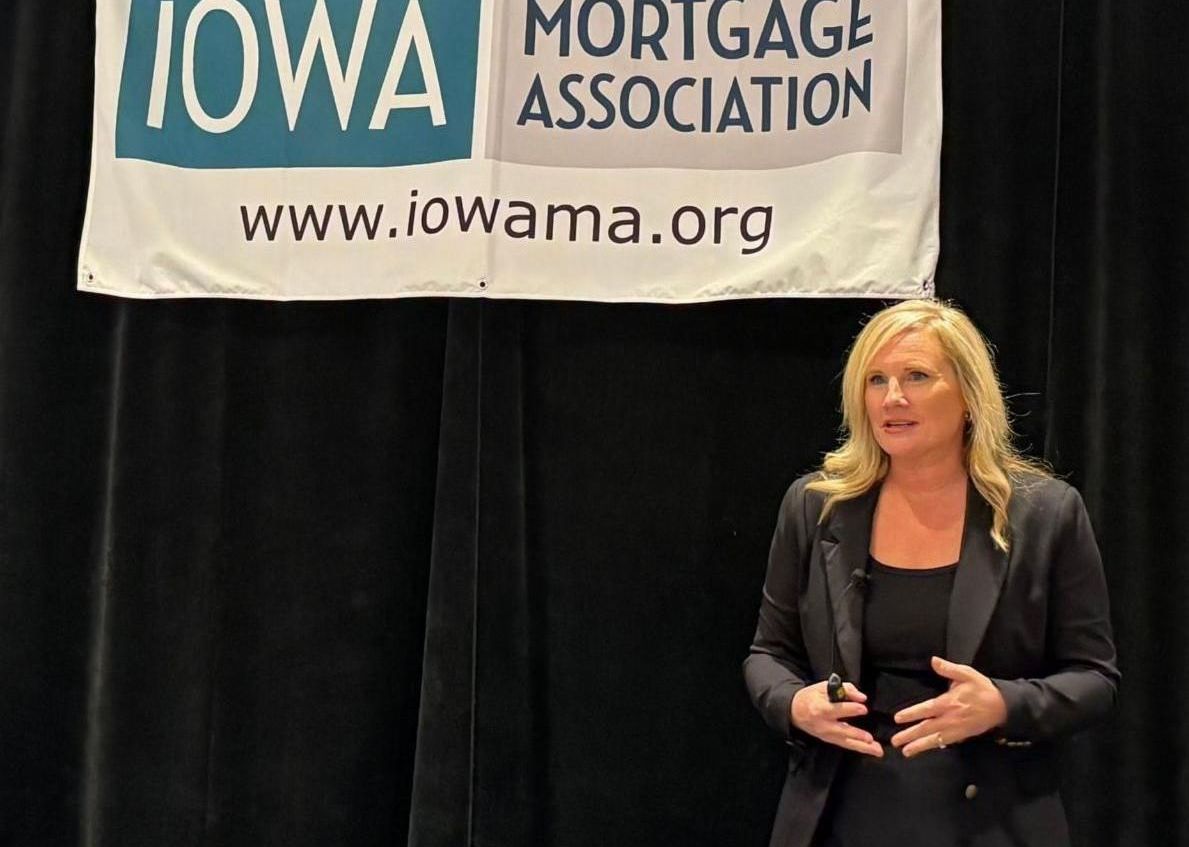
Pictured above is past IMA President Laura Kay Sheely opening the conference with a session on her “52 Mindset.” She shared her story and highlighted the Iowa mortgage professionals in the room who guided her along the way, while explaining how to set a mortgage sales strategy one week at a time.


Many thanks to the sponsors and exhibitors who helped make this event possible.

Sponsors


Arch Mortgage Insurance

CBMS

Essent Guaranty

FICO

Iowa Title Guaranty

MGIC

NewRez

Exhibitors


AlekCO Insurance

Arch MI

CBMS

Credit Information Systems | Star Appraisal Management Company

Enact MI

Essent Guaranty

FIPCO

Flat Branch Mortgage Services

Guild Mortgage

Heartland Credit Restoration

Iowa Bankers Mortgage Corporation

Iowa Title Guaranty

National Mortgage Insurance

Pennymac TPO


IMA Elects New Leadership

The IMA recently elected officers and directors to serve on its 2025-26 board of directors. These leaders assumed their roles during the annual IMA Fall Conference. Officers of the IMA Executive Committee include:


  • Terry Gearhart, president, Neighborhood Finance Corp.
  • Casey Purcell, president-elect, Kind Lending
  • Derek Carter, vice president, Community 1st Credit Union
  • Nick Mundorf, secretary/treasurer, Flat Branch Home Loans
  • Travis Eagle, past-president, Ohnward Bank & Trust


Officers were nominated and approved by IMA member organizations from across the state. The IMA Executive Committee leads the board of directors, which is responsible for setting policy and overseeing the general operation of the IMA. Also serving on the 2025-26 IMA board of directors are:


  • Jay Borbeck, CBMS
  • Charlie Chedester, Midwest Family Lending Corp.
  • Krystal Frederick, Dupaco Credit Union
  • Brianna Gaunt, Community 1st Credit Union
  • Jason Hutchison, American Bank & Trust Co.
  • Matt Klein, Central Bank
  • Dave Lewis, Halo Capital
  • Rachel Pierce, Benchmark Home Loans
  • Megan Severson, Essent Guaranty


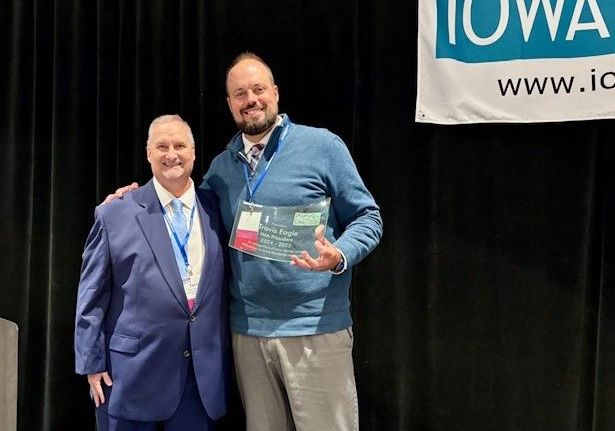
Pictured above is incoming IMA President Terry Gearhart presenting a plaque of appreciation to outgoing IMA President Travis Eagle. 


Industry News

Trigger Lead Bill Signed into Law

On Sept. 5, President Donald Trump signed into law H.R. 2808, otherwise known as the Homebuyers Privacy Protection Act. This bill limits the circumstances in which credit reporting agencies may provide consumer credit reports to third parties in connection with residential mortgage transactions. These provisions take effect 180 days after the bill’s enactment.


Specifically, the bill prohibits a credit reporting agency from providing a consumer’s credit report to a third party in connection with a residential mortgage transaction, unless the transaction consists of a firm offer of credit or insurance and the third party either provides documentation certifying the consumer’s consent or has originated a mortgage on behalf of the consumer, is a current mortgage loan servicer to the consumer, or has a current specified banking relationship with the consumer.


As a reminder, Iowa lawmakers passed House File 857, a state-specific bill related to use of prescreened trigger lead information, which went into effect July 1, 2025.


AVM Quality Control Standards Requirement

Originators are reminded the interagency final rule requiring implementation of quality control standards for the use of Automated Valuation Models (AVMs) went into effect on Oct. 1, 2025. Mortgage originators and secondary market issuers who use AVMs to determine the collateral value of a mortgage secured by a consumer’s principal dwelling are subject to the requirements. Under the final rule, institutions that engage in certain credit decisions or securitization determinations based in whole or in part on AVM values must adopt policies, practices and control systems designed to:


  • Ensure a high level of confidence in estimates
  • Protect against data manipulation
  • Seek to avoid conflicts of interest
  • Require random sample testing and reviews
  • Comply with nondiscrimination laws


The final rule implements a Dodd-Frank Act provision, which adds a subsection to Reg. Z under valuation independence and a new subpart to agency appraisal rules.


Published by Iowa Mortgage Association.

View the archives.


Join our email list.